
Global equity markets started the week on the back foot as an AI valuation wobble collided with a fresh energy shock, leaving investors with little appetite to add risk ahead of a heavy central bank calendar. MSCI Asia Pacific fell 0.6%, dragged down by a 2.8% slide in South Korea’s Kospi, as the region’s semiconductor complex came under pressure. SK Hynix and Samsung Electronics both dropped more than 3.5%, while SoftBank Group slumped 13% in Tokyo after OpenAI’s Sam Altman confirmed there would be no IPO this year. Western futures echoed the risk-off tone, with Nasdaq 100 contracts down 1.2% and S&P 500 futures easing 0.5%.
The trigger for the tech reset was a sharp change in AI market psychology. Leading AI executives agreed to slow development of advanced models in order to implement additional regulatory and safety measures, forcing investors to reassess the speed, scale and monetisation timeline of the sector’s capital expenditure boom. After months of one-way enthusiasm, the market is now asking whether AI leadership can continue to carry global equity indices if earnings delivery is pushed further out and valuations remain stretched.
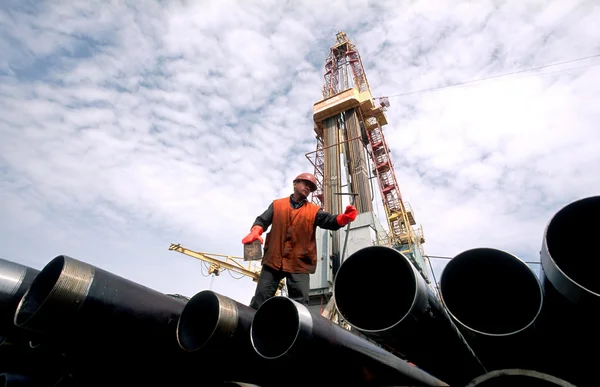
At the same time, energy markets delivered another stagflationary jolt. Brent crude surged 2.5% to $107.30/bbl after Saudi Arabia halted flows through its major East-West oil pipeline following drone strikes near key pumping stations. The disruption was compounded by the postponement of a planned diplomatic meeting between Iran and Gulf neighbours over a temporary Hormuz shipping corridor, adding a fresh geopolitical premium to crude. With Brent now firmly above $107/bbl, the inflation impulse from energy is again threatening to dominate the macro narrative.
Fixed income remains under pressure, with the US 10-year Treasury yield hovering around 5.00% after last week’s broad selloff. August US CPI landed in line with expectations at 3.4% year-on-year, but sticky core measures, firmer inflation expectations and a hawkish Jackson Hole message from Fed Chair Kevin Warsh have reinforced the case for another tightening step. Money markets now price roughly an 87% probability of a 25 bps hike at Wednesday’s FOMC meeting, leaving duration vulnerable to any signal that rates may need to stay higher for longer. In FX and metals, the Dollar retained a modest bid as higher real yields continued to do the heavy lifting. The US Dollar Index rose 0.2%, while spot Gold slipped 0.4% to $4,330/oz, with bullion struggling to attract safe-haven demand against a backdrop of elevated real rates and a firmer greenback.
The week ahead is dominated by a dense G10 central bank schedule, with the Federal Reserve on Wednesday, the Bank of England on Thursday and the Bank of Japan on Friday. The BoE is expected to hold rates this week, but investors are watching for another £50bn reduction in gilt holdings under quantitative tightening. With both the Fed and ECB tightening financial conditions, short sterling futures are fully pricing a 25 bps BoE hike by November. The BoJ, meanwhile, faces growing pressure to raise rates on Friday as policymakers attempt to lean against Yen weakness and energy-driven import inflation.
Macro to Micro, the collision between an AI valuation reset and an oil-driven inflation shock creates a difficult backdrop for multi-asset portfolios. Brent above $107/bbl and sovereign yields near multi-year highs leave central banks with limited room to cushion volatility, while stretched equity multiples reduce the margin for disappointment. For traders, the immediate task is risk control into Wednesday’s FOMC decision. The key question is whether the AI pullback proves to be a healthy rotation after an extended rally, or the first stage of a broader cross-asset deleveraging event.
Overnight Headlines
Oil Gains As Shutdown Of Saudi Pipeline Deepens Energy Crisis
Saudi Pipeline Outage Threatens Loss Of 4% Of Global Oil Supply
New Attacks In Hormuz And Saudi Arabia Worsen Oil Disruption
Hormuz Meeting With Iran And Gulf Nations Postponed, Oman Says
Trump Demands Ukraine Halt Refinery Strikes As Diesel Surges
Fed And BoJ Expect Rate Hikes As US Bond Market Flails
Goldman Sachs Flips Forecast, Now Sees September Fed Rate Hike
Warsh, Trump On Collision Course As Investors Expect Fed To Hike
Oil Price Surge Revives Prospect Of Bank Of England Rate Rise This Year
Dollar Steady, Yen Near Seven-Month High Ahead Of Fed, BoJ Meetings
China’s Economy Enters Critical Phase Determining 2026 Stimulus
Canada Seeks EU ‘Associate Member’ Status As US Trade Talks Collapse
Trump Downplays AI Concerns As CEOs Call For Slowing Pace
SoftBank Gets Upsized $11.9B Loan In OpenAI Funding Push
Anthropic Said To Choose Nasdaq For Much-Anticipated IPO
OpenAI's Sam Altman Won't Do IPO This Year Because Of Safety Fears
FX Options Expiries For 10am New York Cut
(1BLN+ represents larger expiries and is more magnetic when trading within the daily ATR.)
EUR/USD: 1.1620 (EU1.18b), 1.1800 (EU1.16b), 1.1600 (EU1.15b)
USD/JPY: 161.00 ($1.33b), 157.50 ($1.08b), 160.00 ($754.8m)
AUD/USD: 0.6850 (AUD744.1m), 0.6700 (AUD612.3m), 0.7200 (AUD476.7m)
USD/CAD: 1.3690 ($479m), 1.4030 ($350m), 1.4385 ($342m)
USD/KRW: 1400.00 ($1.05b), 1360.00 ($860m), 1440.00 ($727.5m)
USD/CNY: 6.6960 ($300m), 6.6910 ($300m)
EUR/GBP: 0.8700 (EU325.5m)
USD/MXN: 17.09 ($306.2m)
NZD/USD: 0.5750 (NZD619.5m), 0.5550 (NZD303.2m)
GBP/USD: 1.2700 (GBP521.7m), 1.4000 (GBP516.4m)
CFTC Positions as of 11/9/26
Equity fund speculators increase S&P 500 CME net short position by 29,085 contracts to 336,643
Equity fund managers cut S&P 500 CME net long position by 19,683 contracts to 907,770
Speculators trim CBOT US 5-year Treasury futures net short position by 113,020 contracts to 1,267,493
Speculators trim CBOT US 10-year Treasury futures net short position by 74,492 contracts to 834,783
Speculators increase CBOT US 2-year Treasury futures net short position by 46,589 contracts to 929,107
Speculators trim CBOT US UltraBond Treasury futures net short position by 24,171 contracts to 345,140
Speculators increase CBOT US Treasury bonds futures net short position by 1,016 contracts to 200,517
Bitcoin net long position is 1,524 contracts
Swiss franc posts net short position of -29,985 contracts
British pound net short position is -58,836 contracts
Euro net short position is -42,616 contracts
Japanese yen net long position is 10,796 contracts
Technical & Trade Views
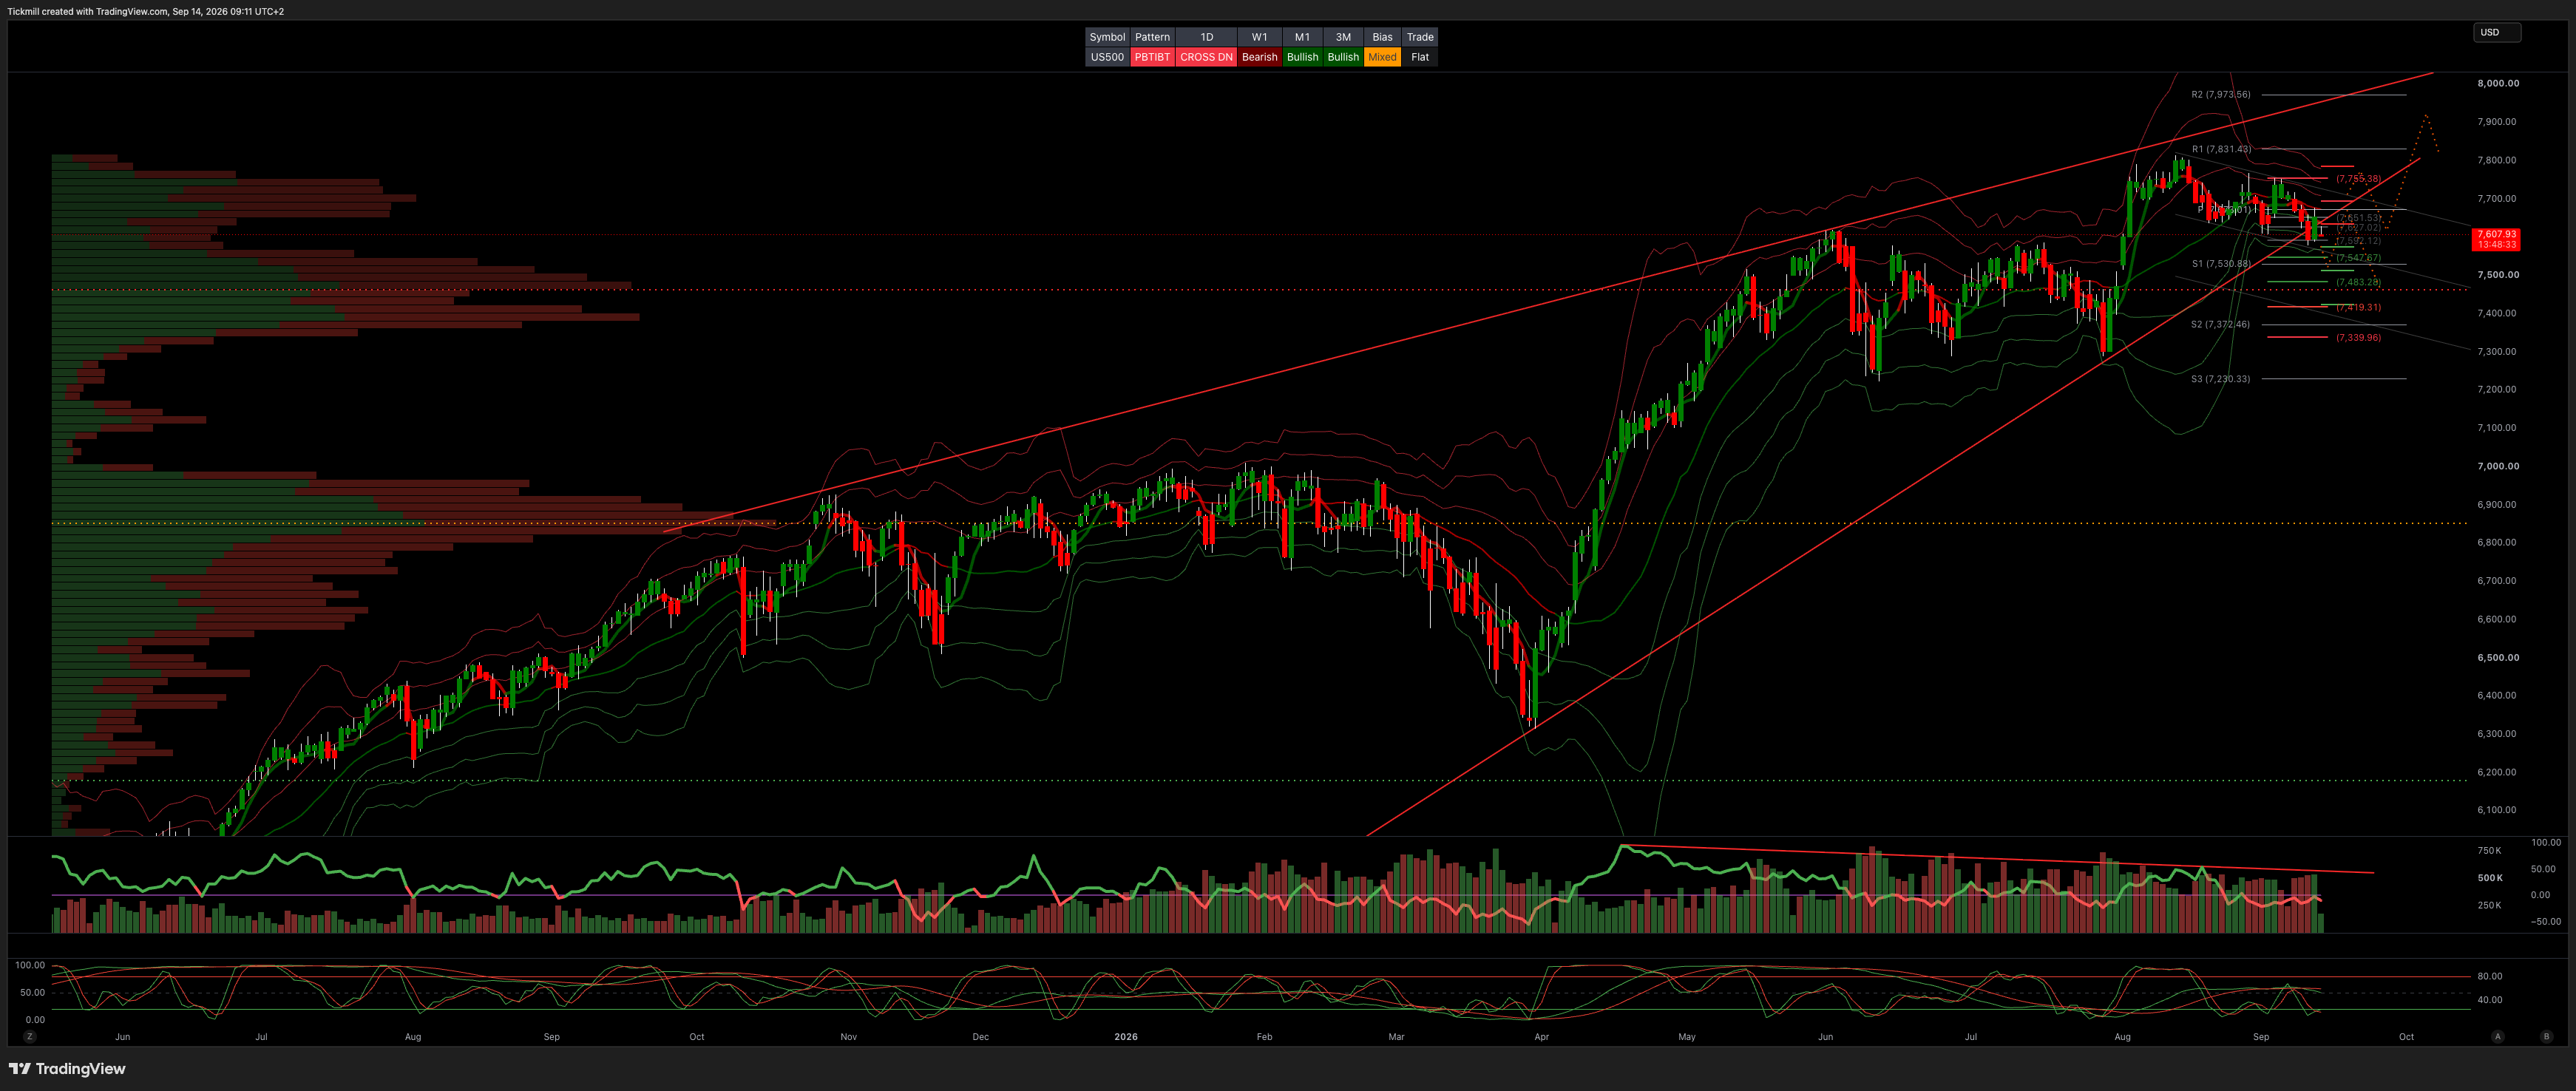
SP500 - 7700 weekly bull/bear level
Daily VWAP Bearish
Weekly VWAP Bearish
Above 7700 Target 7800
Below 7580 Target 7545
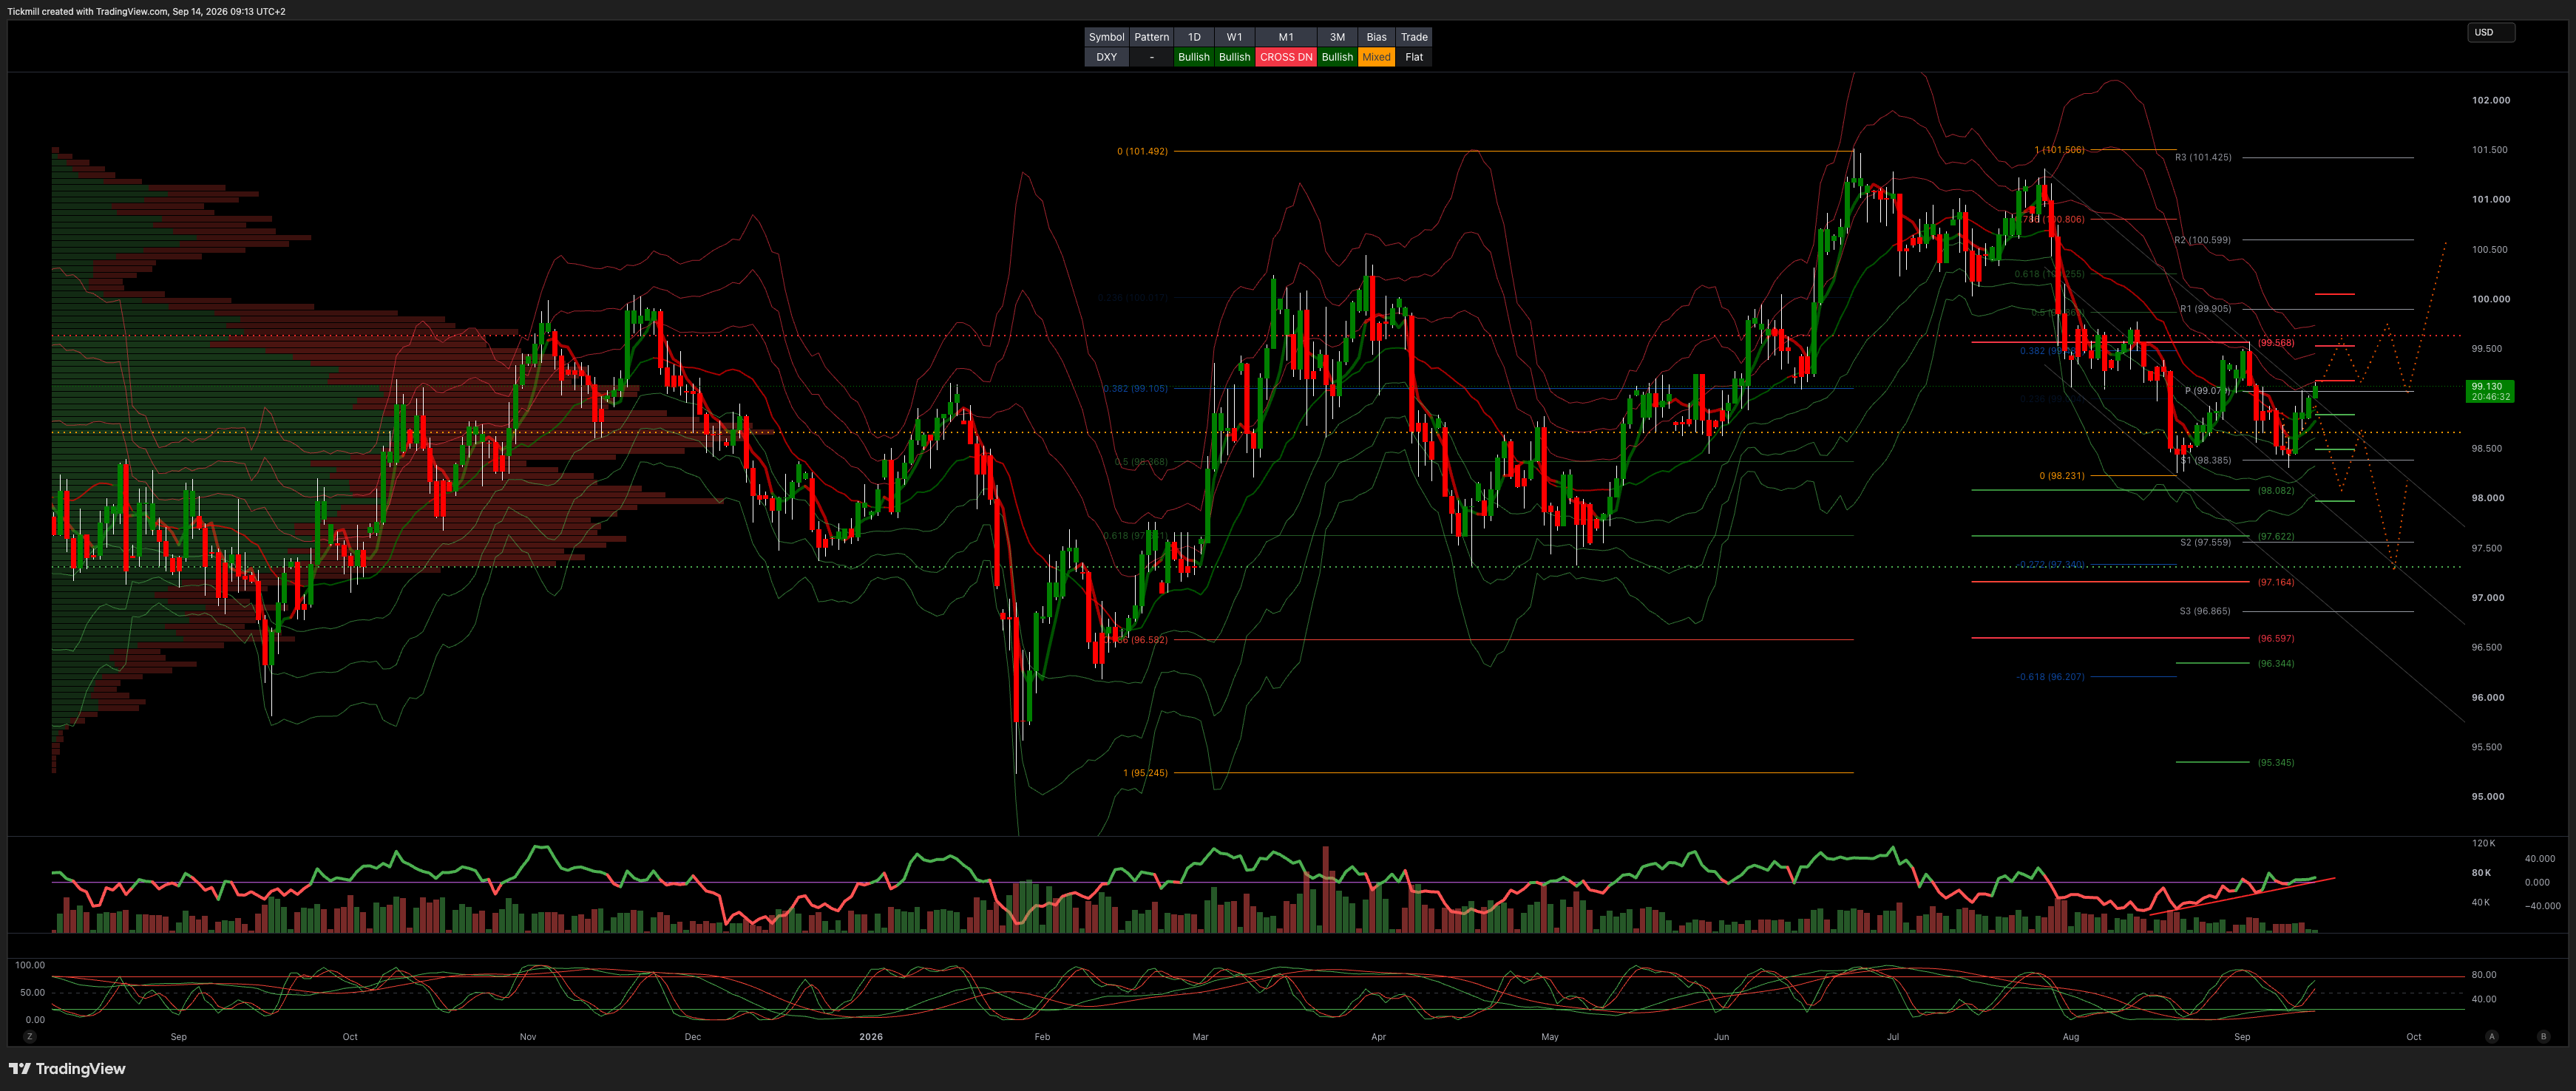
DXY - 99 weekly bull/bear level
Daily VWAP Bullish
Weekly VWAP Bullish
Above 99.20 Target 99.75
Below 99 Target 97.50
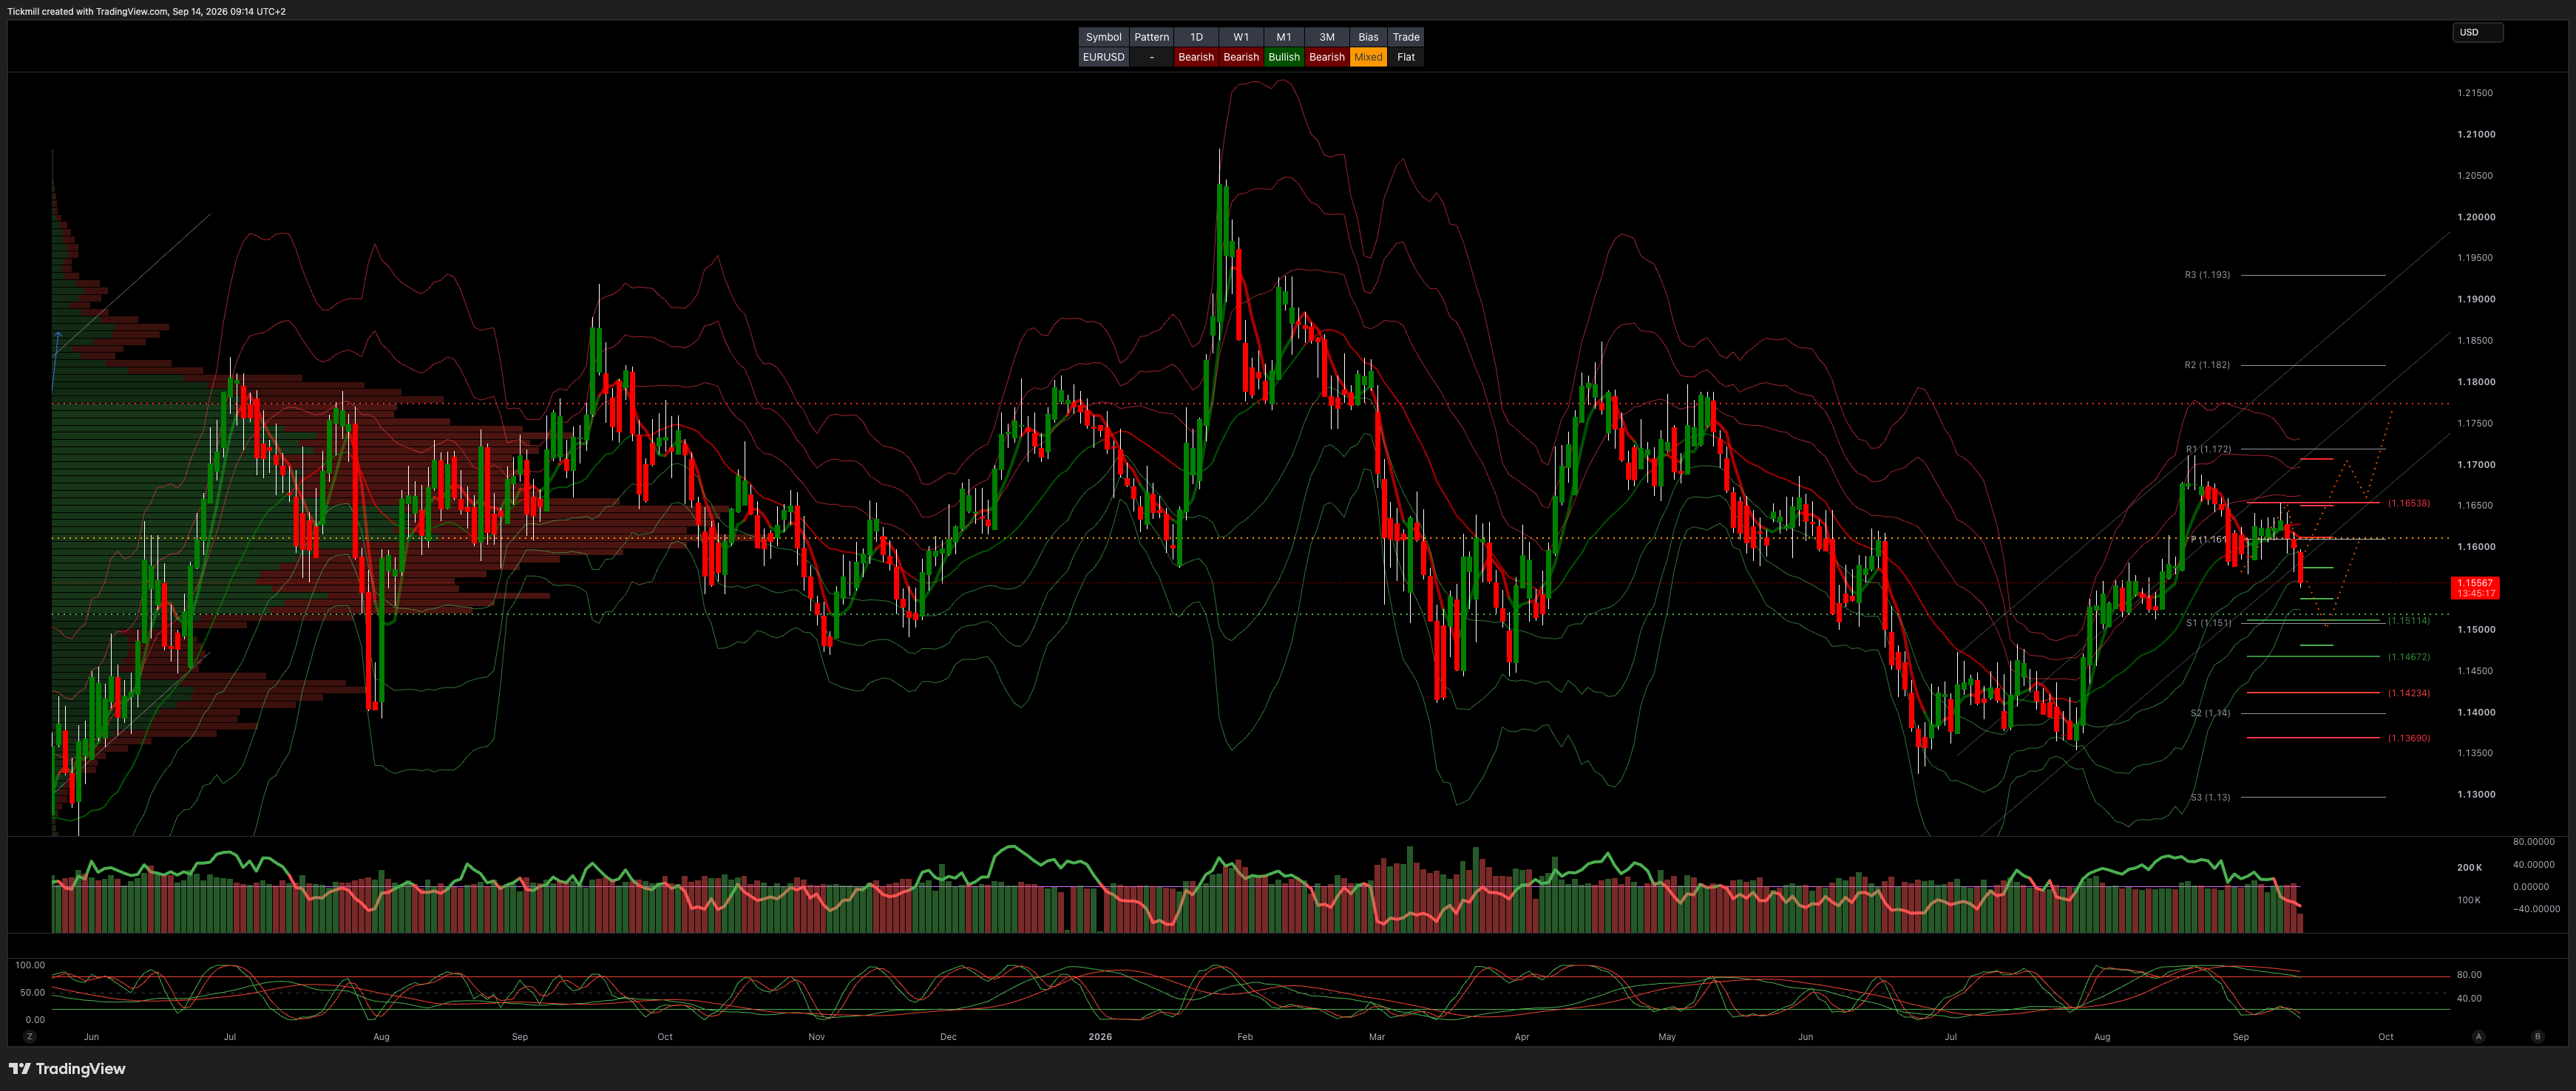
EURUSD - 1.16 weekly bull/bear level
Daily VWAP Bearish
Weekly VWAP Bearish
Above 1.16 Target 1.1750
Below 1.1550 Target 1.15
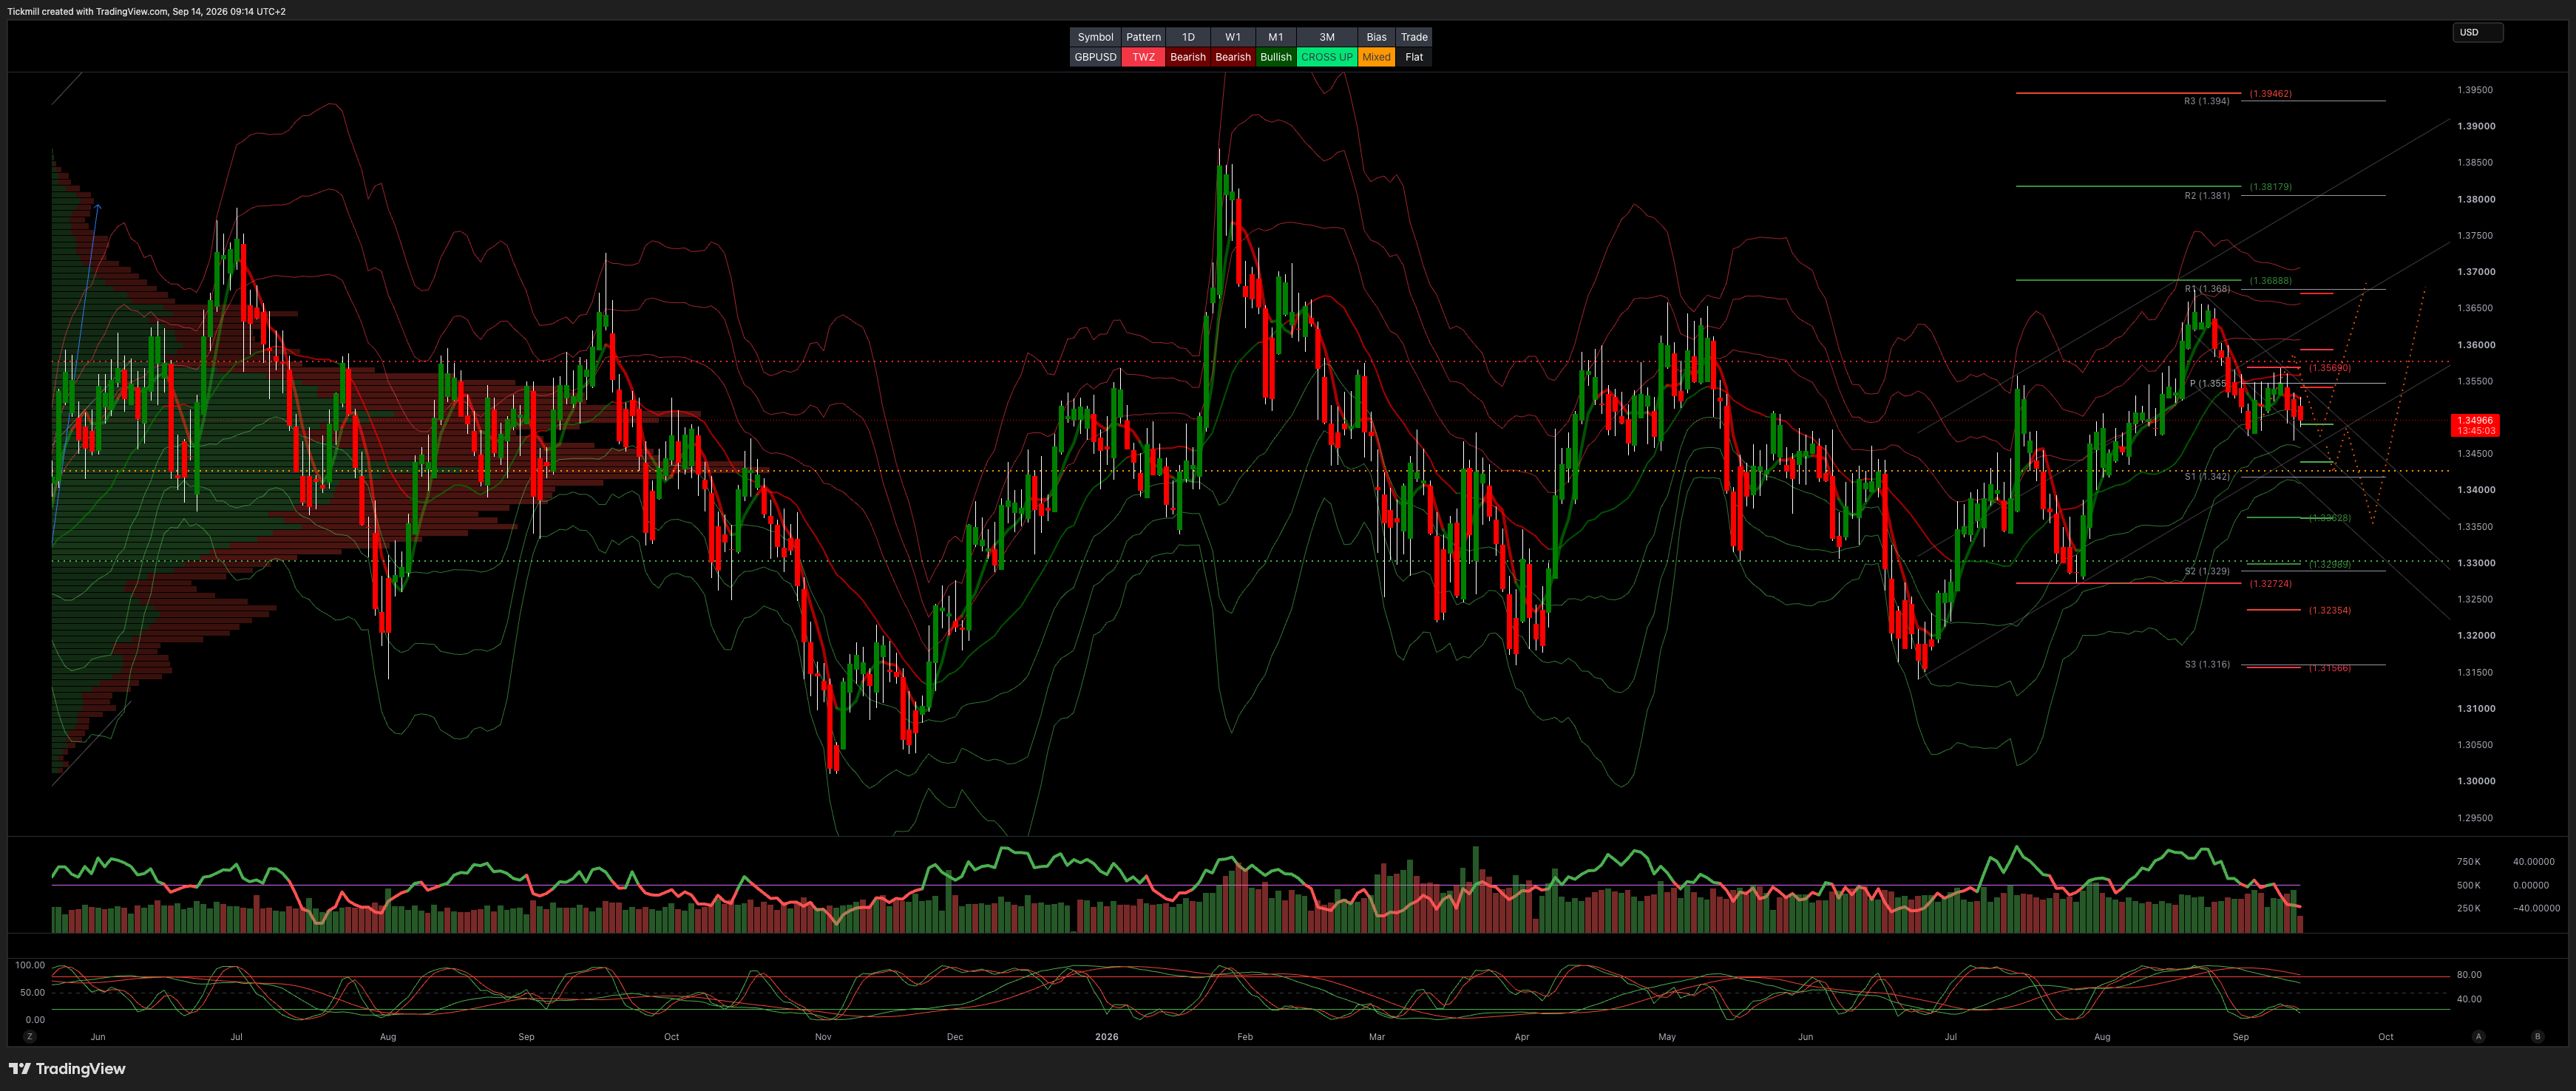
GBPUSD - 1.3460 weekly bull/bear level
Daily VWAP Bearish
Weekly VWAP Bearish
Above 1.3460 Target 1.3690
Below 1.3430 Target 1.33
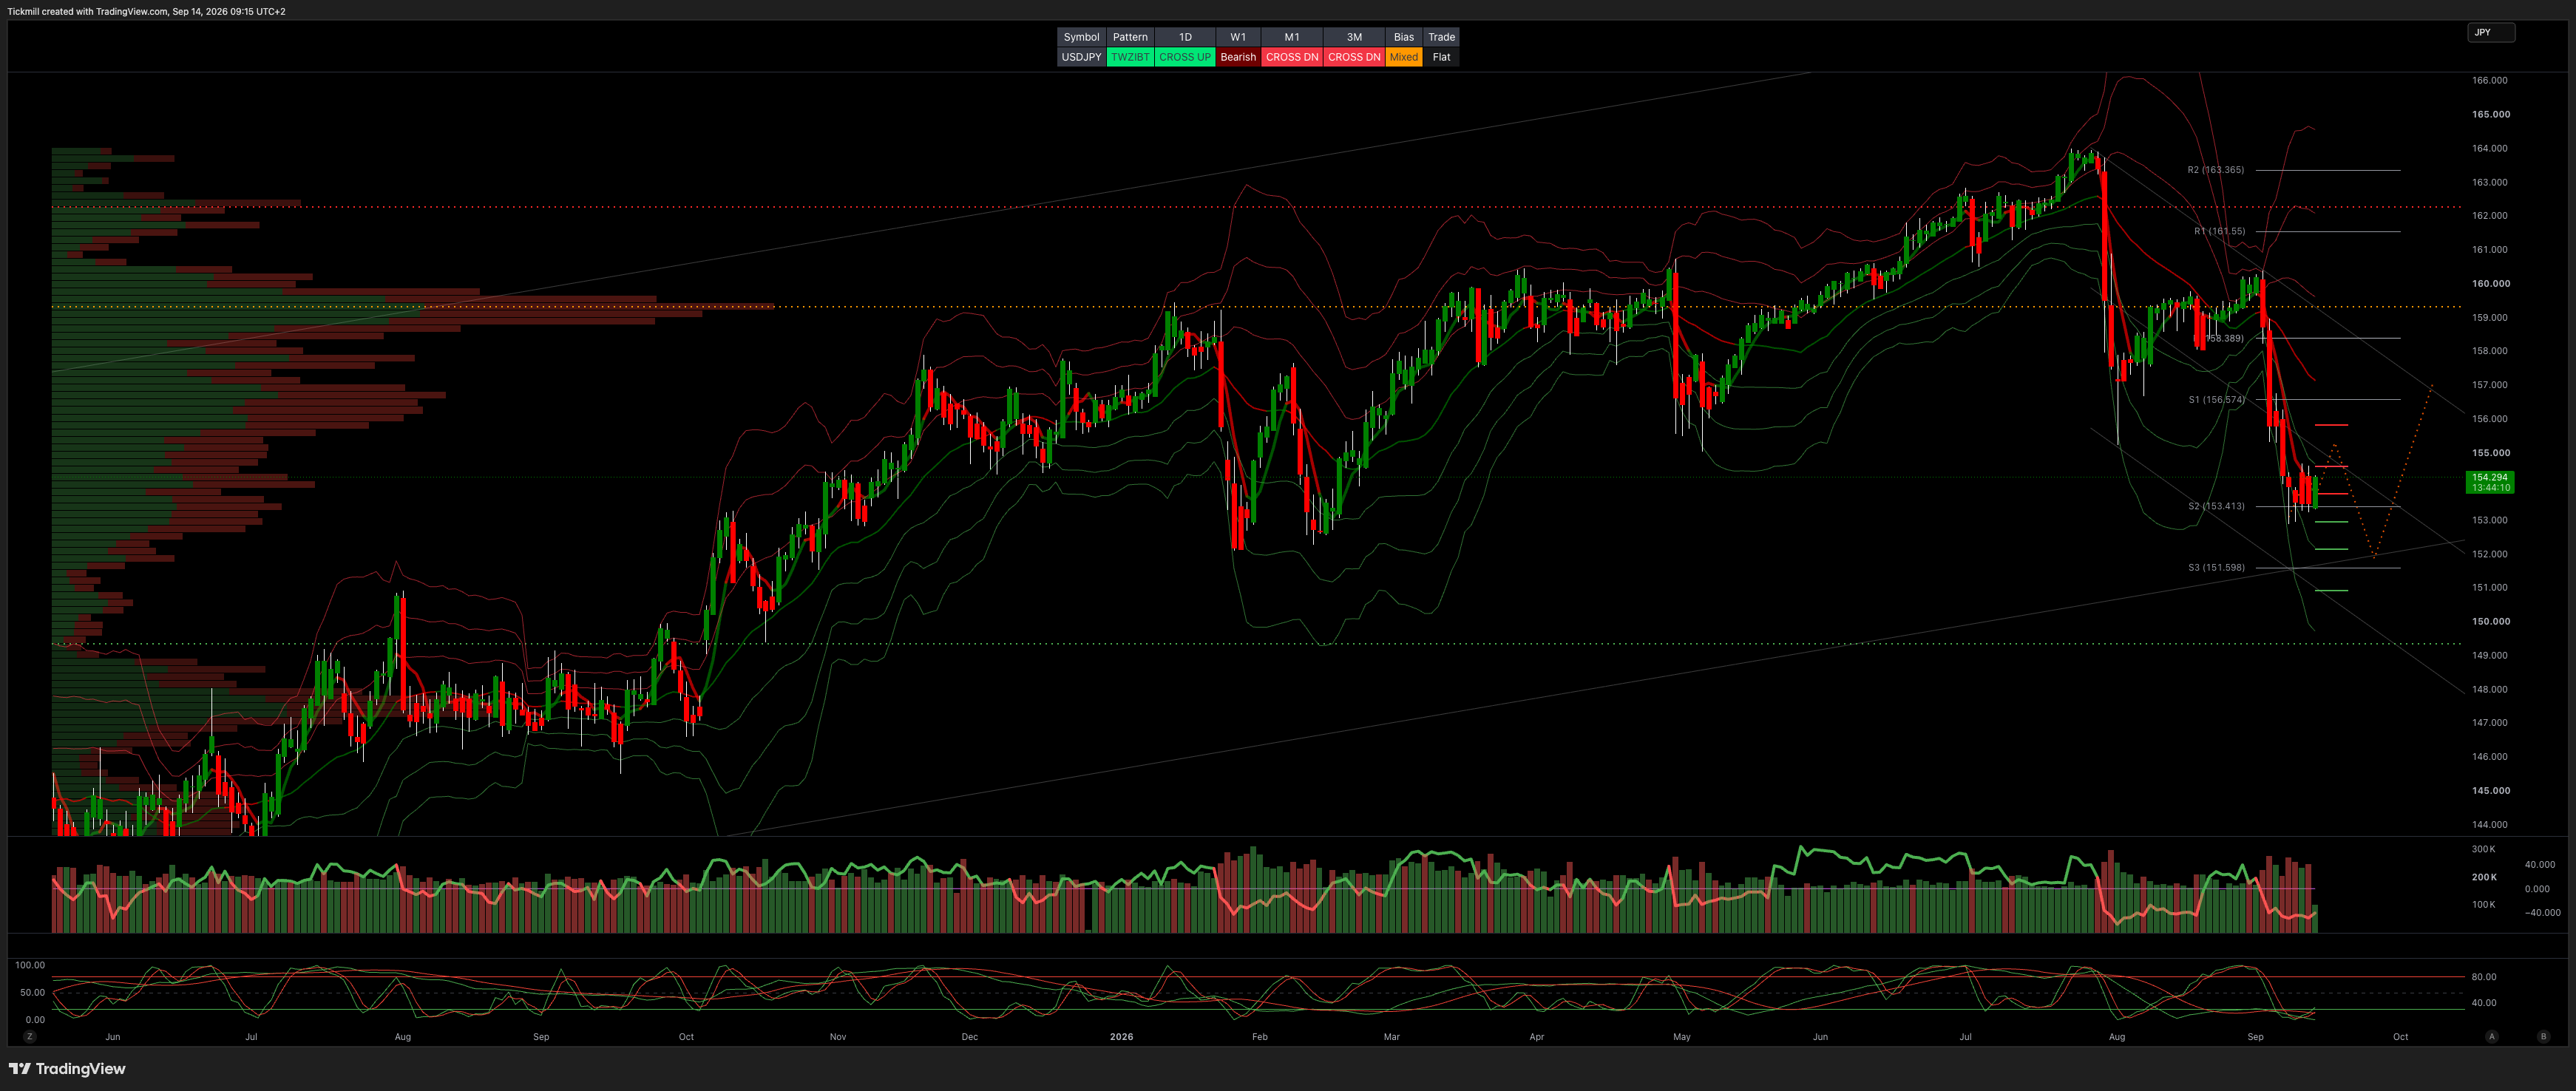
USDJPY - 155 weekly bull bear level
Daily VWAP Bearish>Bullish
Weekly VWAP Bearish
Above 155 Target 160
Below 155 Target 152
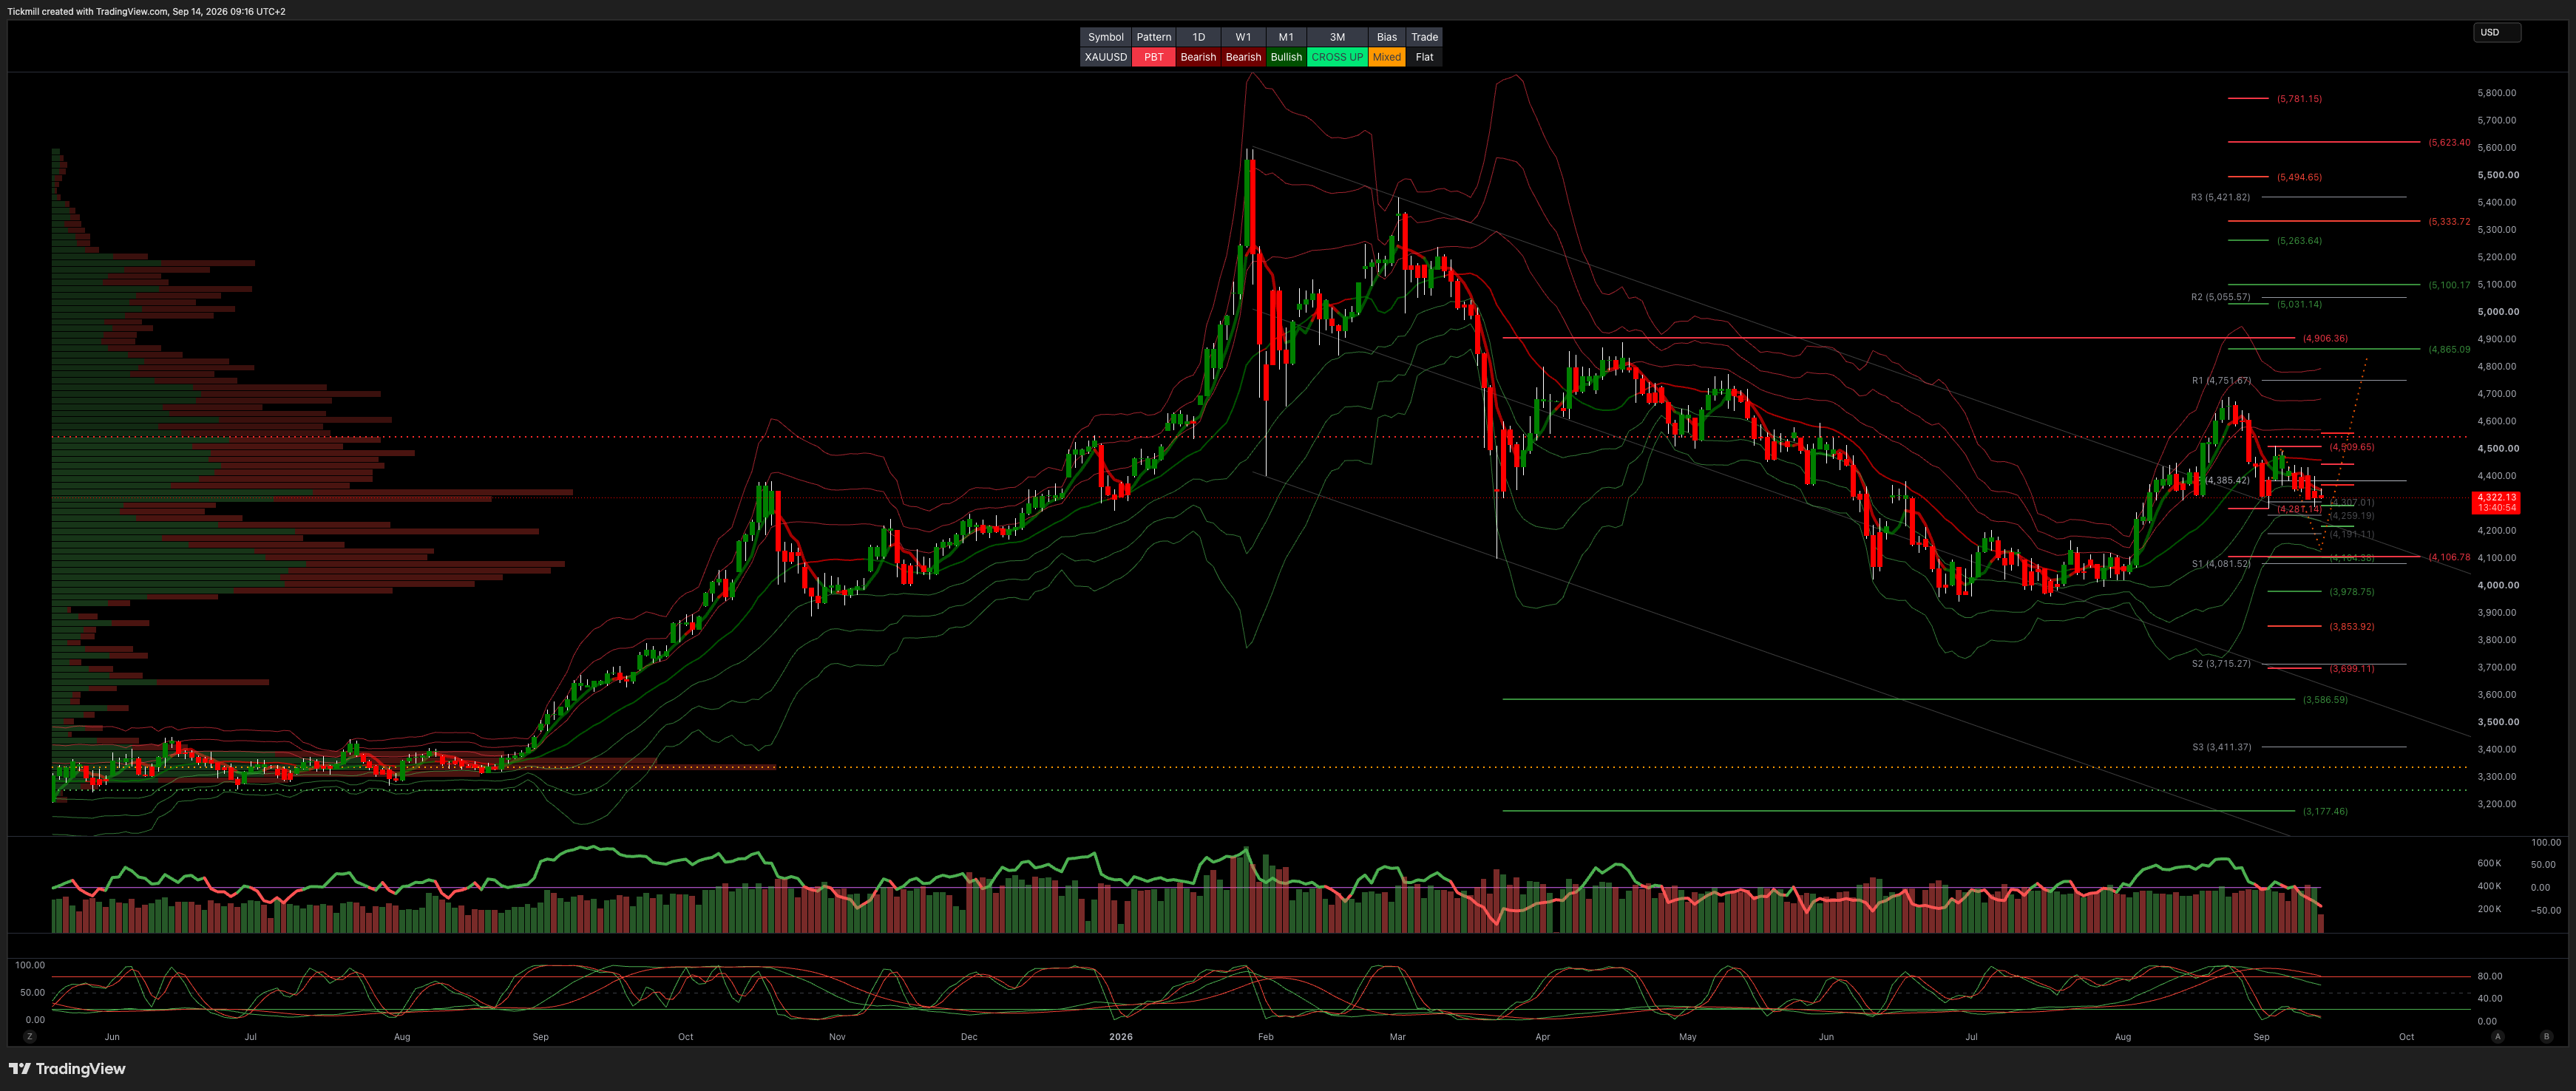
XAUUSD - 4510 weekly bull bear level
Daily VWAP Bearish
Weekly VWAP Bearish
Above 4500 Target 4655
Below 4500 Target 4100
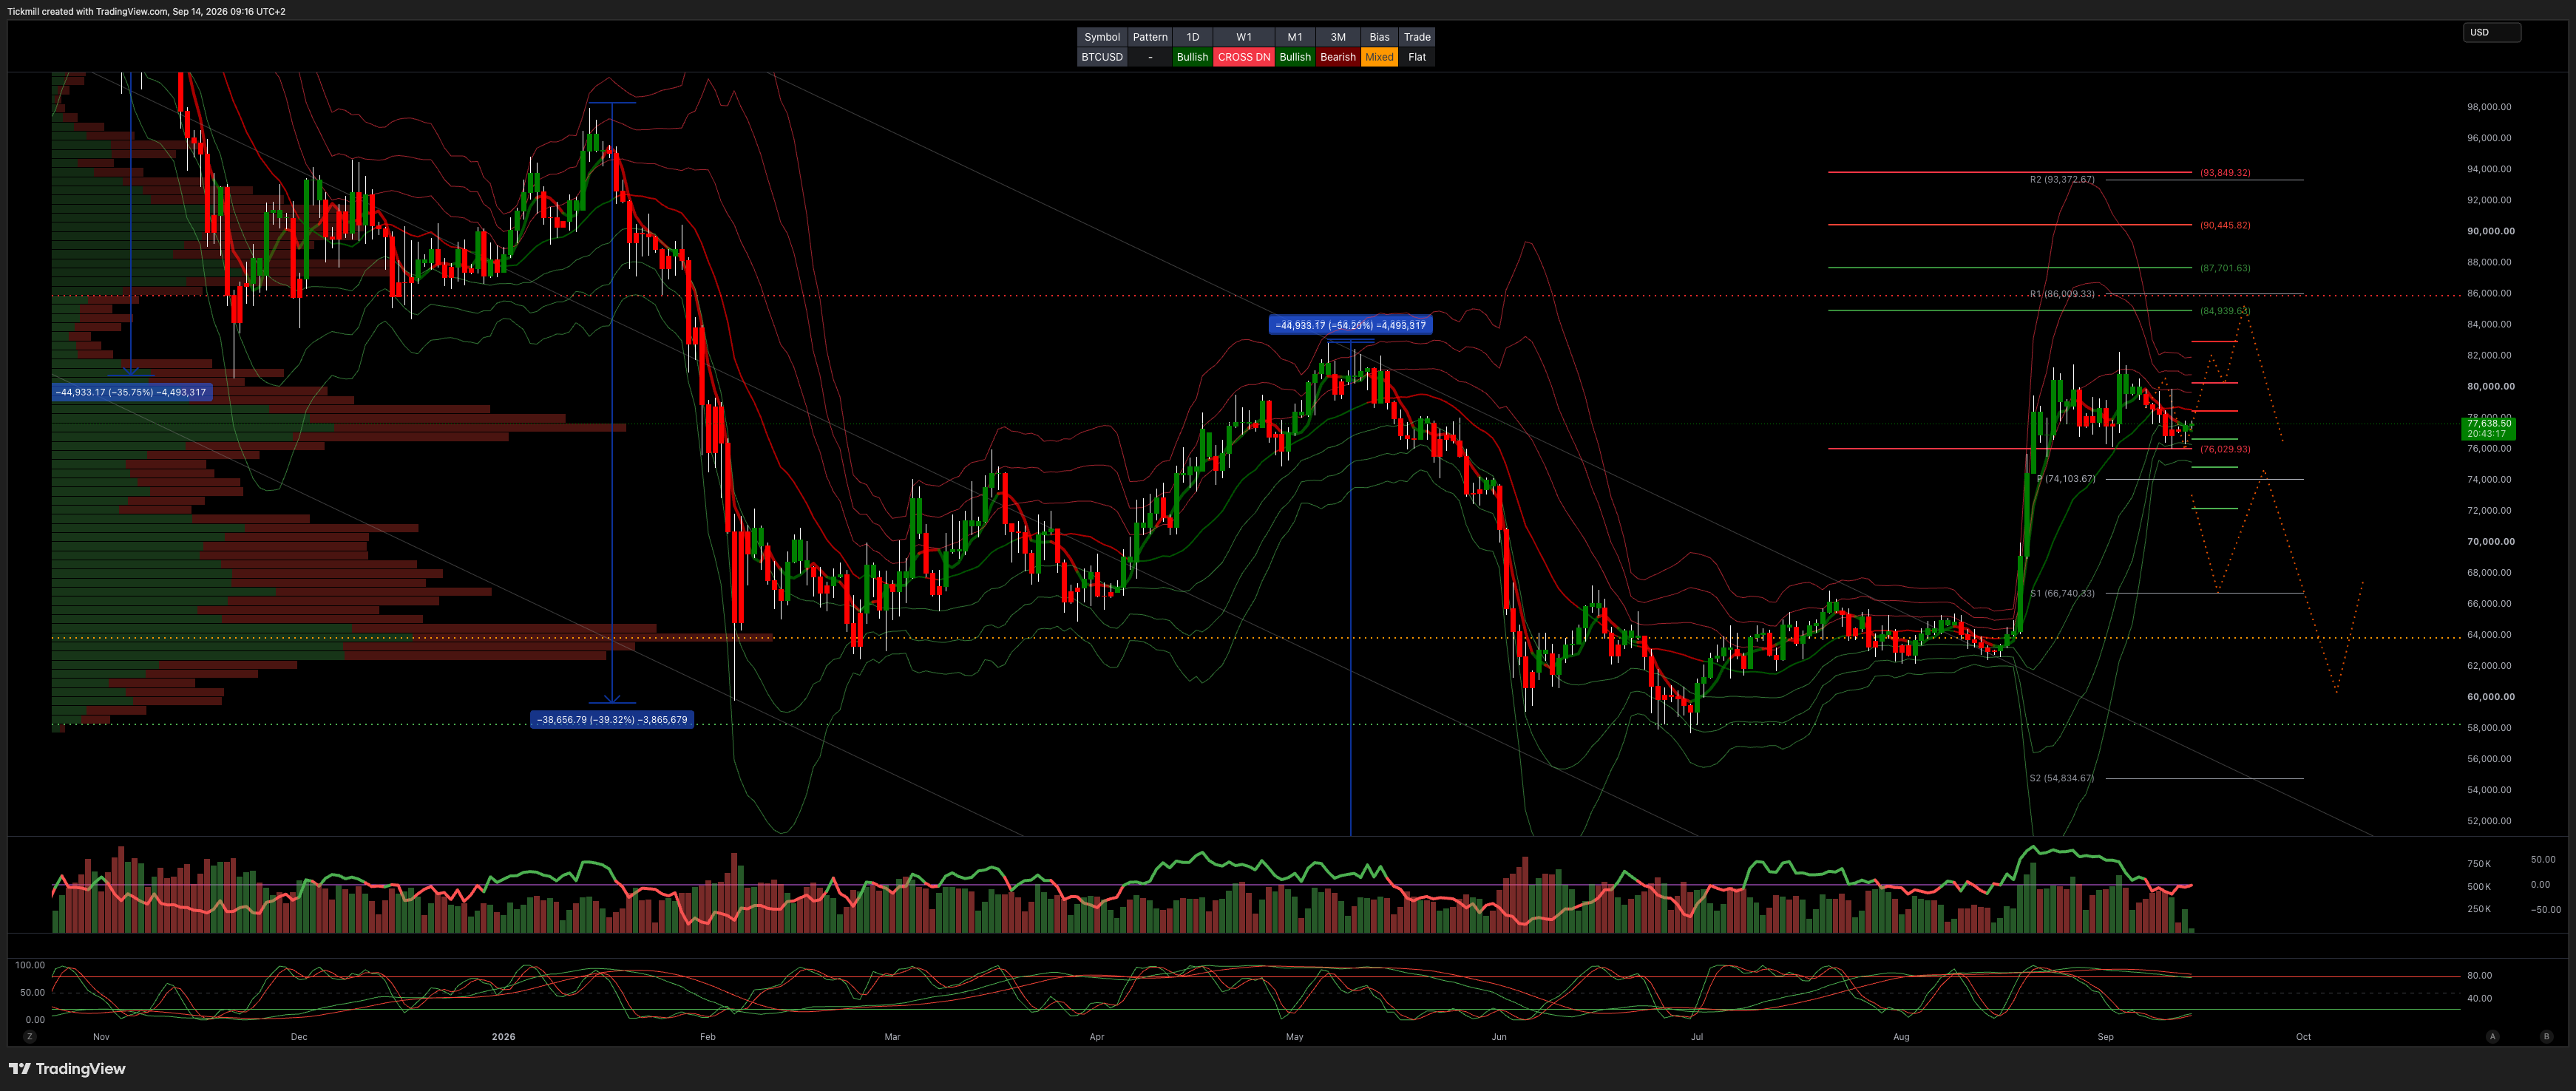
BTCUSD - 76k weekly bull bear level
Daily VWAP Bullish
Weekly VWAP Bullish>Bearish
Above 76k Target 85k
Below 74k Target 66.8k
Comments
Log in or sign up to join the conversation.