
The crypto market arrives at the weekend with its headline intact but its internal support fading. Total capitalization has held its ground while gains have concentrated near the top. A broad advance has become a market where a few large names are doing most of the lifting most of the field is lower.
Bitcoin remains modestly positive, while AAVE has separated sharply from the rest of its group. BCH has given back prior-week strength, and SUI no longer reads as a clear weekly leader. The coming sessions will test whether those pockets of resilience attract wider participation or remain isolated.
Why Crypto’s $2.89T Market Cap Hides a Weaker Market
A week ago the market carried momentum and matching breadth. That combination has separated. Total crypto market capitalization sits near $2.892 trillion, while the reconstructed rolling seven-day cap-weighted screen is +0.20%.
Among the top 100 assets by market cap, 37 are positive over seven days and 63 are negative. A tighter screen of 40 established risk assets returned 15 positive and 25 negative, with a -1.62% median and a +0.21% cap-weighted result. Larger assets are holding the weighted figure above the typical return while most of the field retreats.
Bitcoin dominance sits at 58.92%, down 0.14 percentage point over 24 hours. BTC gained +0.64% over seven days, while Ethereum fell -0.12%. Bitcoin's size helps explain how the aggregate can remain firm while the typical asset is lower.
The sector screens are mixed but still weak outside two pockets. The DeFi and oracle basket posted a +0.30% median, with AAVE at +17.28%, LINK at +0.30%, and UNI at -6.45%. The large layer-one basket returned +0.55%. Payments and value-transfer assets returned -2.61%, established memes -2.67%, and privacy assets -10.83%.
USD-pegged stablecoin supply moved from $310.086 billion on September 27 to $311.893 billion on October 3, a rise of about $1.807 billion or 0.58%. The series can revise, and the timing does not show that the additional supply moved into risk assets. Liquidity expanded while breadth deteriorated, leaving the relationship unresolved.
Notable price action
AAVE Leads DeFi as the Rest of the Sector Stays Split
AAVE is the clearest performance leader in this week's screen. At the time of writing, TradingView shows $182.24 and a week-to-date gain of +16.83%. CoinMarketCap's rolling seven-day field is +17.28%. Coinbase's seven completed daily candles from September 27 through October 3 show +16.66% and a range of $143.83 to $187.23.
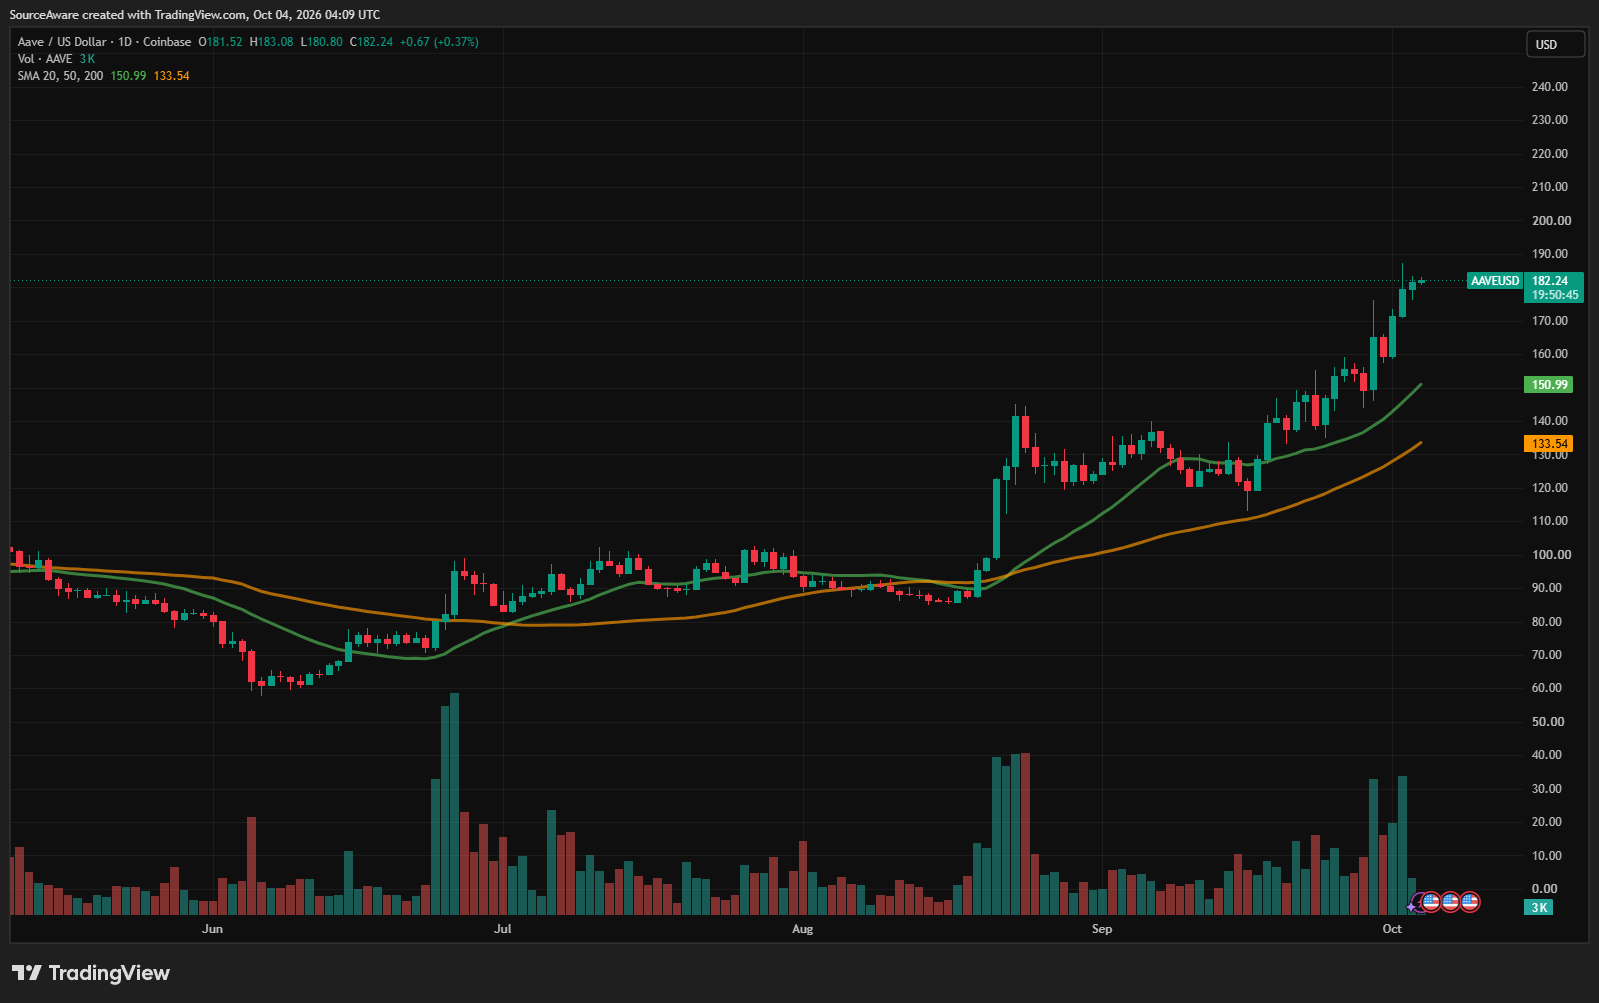
That gap leaves the 20-day simple moving average near $150.99 and the 50-day near $133.54. AAVE's move stands apart from LINK at +0.30% and UNI at -6.45% on CoinMarketCap's rolling field. Its gain does not establish a durable DeFi rotation while the small basket remains split. The retreat from the $187.23 period high also leaves the next test below that recent extreme.
SUI Holds Its Structure but Falls Short of Market Leadership
SUI finished positive across the refreshed windows, though the size of the gain depends on the source. TradingView shows $1.175 and a week-to-date return of +1.48%, while CoinMarketCap's rolling seven-day figure is +1.19%. Coinbase's seven completed daily candles show +1.87% and a range of $1.0972 to $1.2949. The modest gains support relative resilience rather than broad weekly leadership.
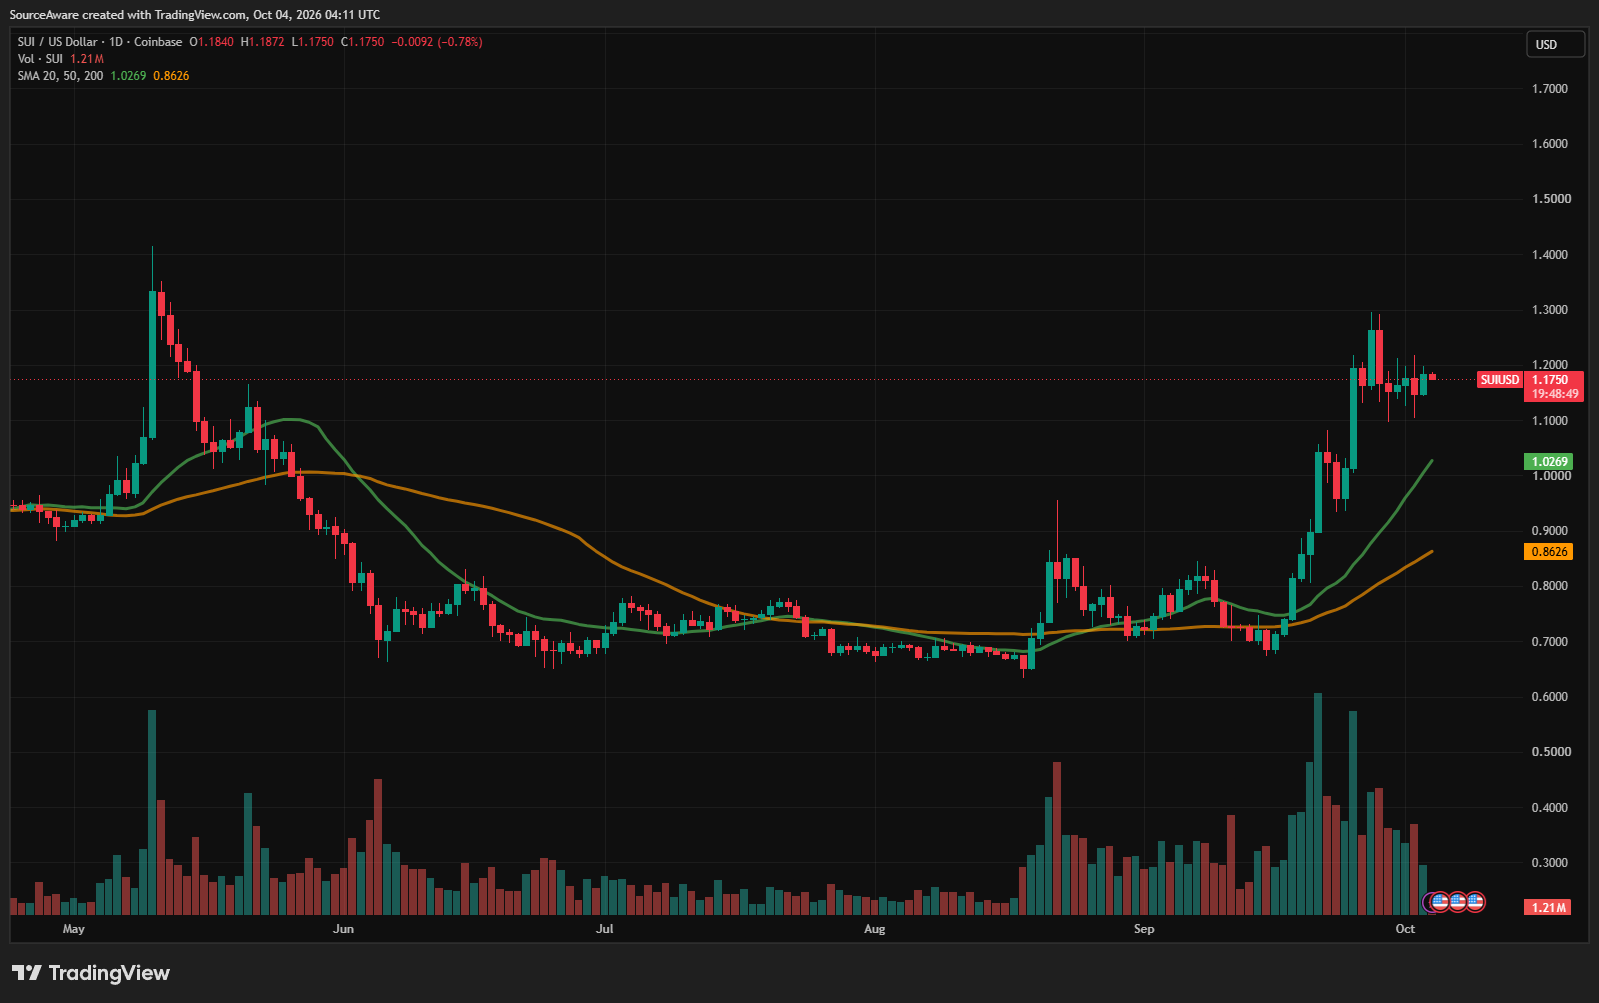
That structure leaves the 20-day moving average near $1.0269 and the 50-day near $0.8626, both below the current price. SUI is holding above those averages while the large layer-one basket posted a +0.55% median. That leaves SUI stronger than the median asset but far behind AAVE's outlier gain. Its role is one of relative structural resilience, but the $1.2949 window high remains well above the current price.
BCH Retreat Highlights Pressure on Payments Tokens
By contrast, BCH shows the other side of the dispersion. TradingView shows $316.72 and a week-to-date decline of -4.95%. CoinMarketCap's rolling field is -4.89%. Coinbase's seven completed daily candles show -4.83% and a range of $296.79 to $347.41.
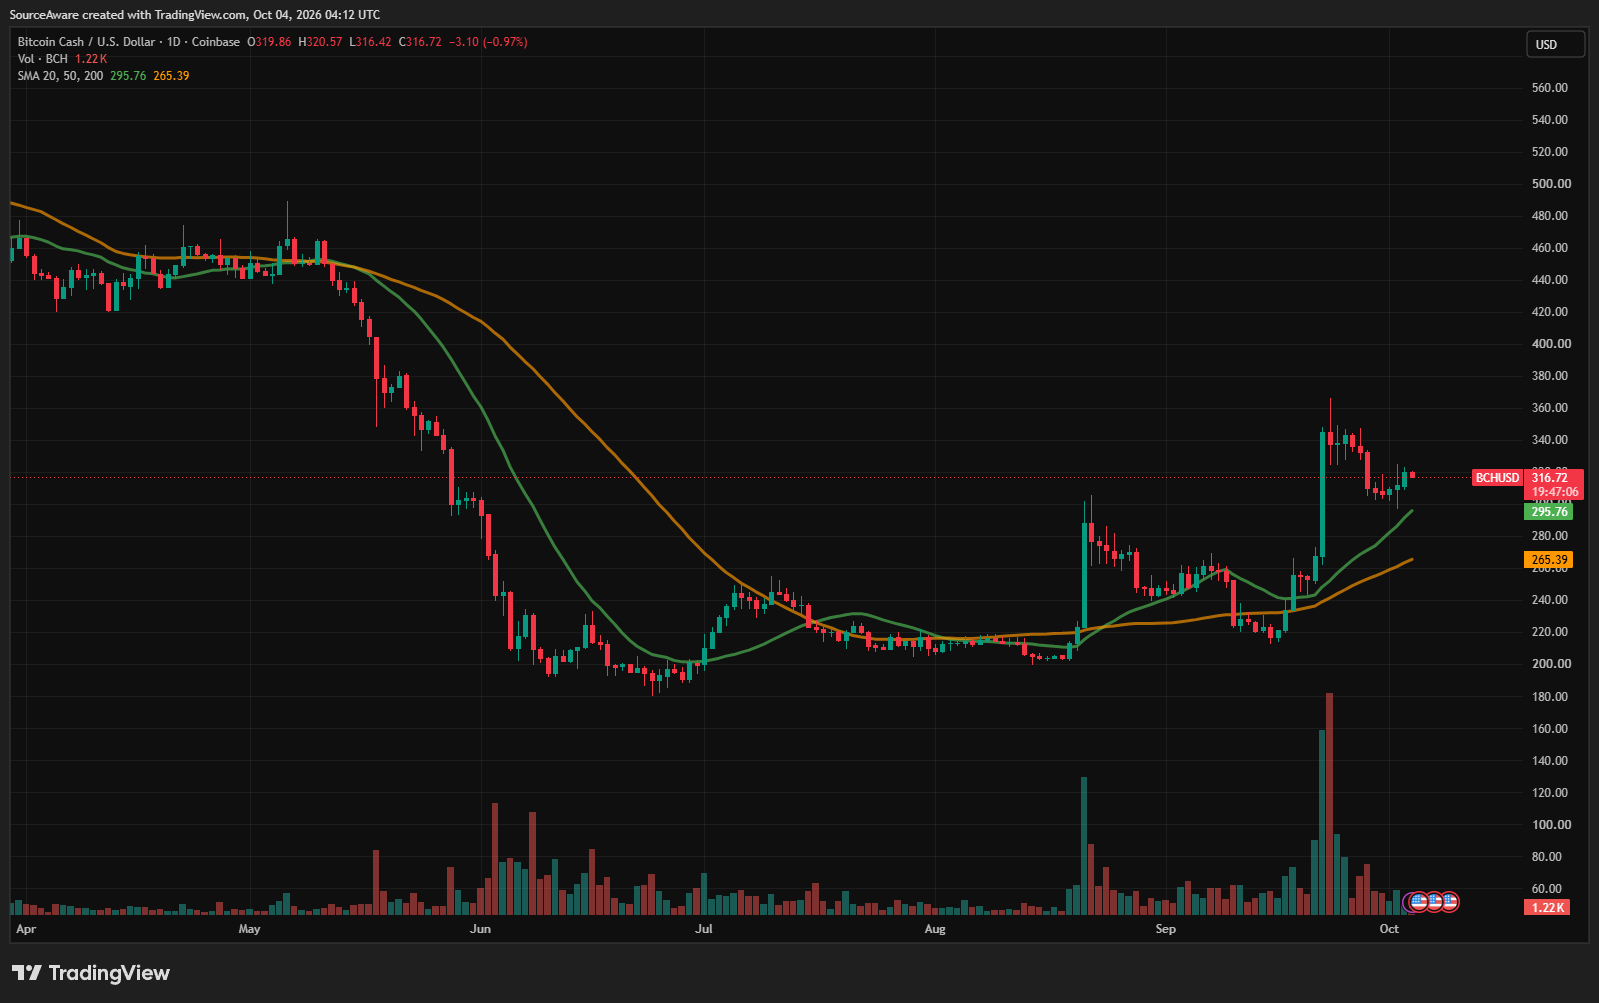
The 20-day moving average sits near $295.76 and the 50-day near $265.39. BCH remains above both despite the weekly decline, leaving its medium-term moving-average structure intact. The payments basket posted a -2.61% median, and BCH's deeper retreat shows that the prior period's leadership did not carry forward. Its role is relative weakness inside an already weak group. Its bounce from the $296.79 window low has not repaired the weekly loss.
Bitcoin’s Weight Keeps the Headline Market Stable
Bitcoin holds 58.92% of total crypto market capitalization. CoinMarketCap's rolling weekly return is +0.64%, while TradingView shows $84,799 and a week-to-date gain of +0.50%. Coinbase's seven completed daily candles show +0.40%, with a range of $82,510 to $87,249.
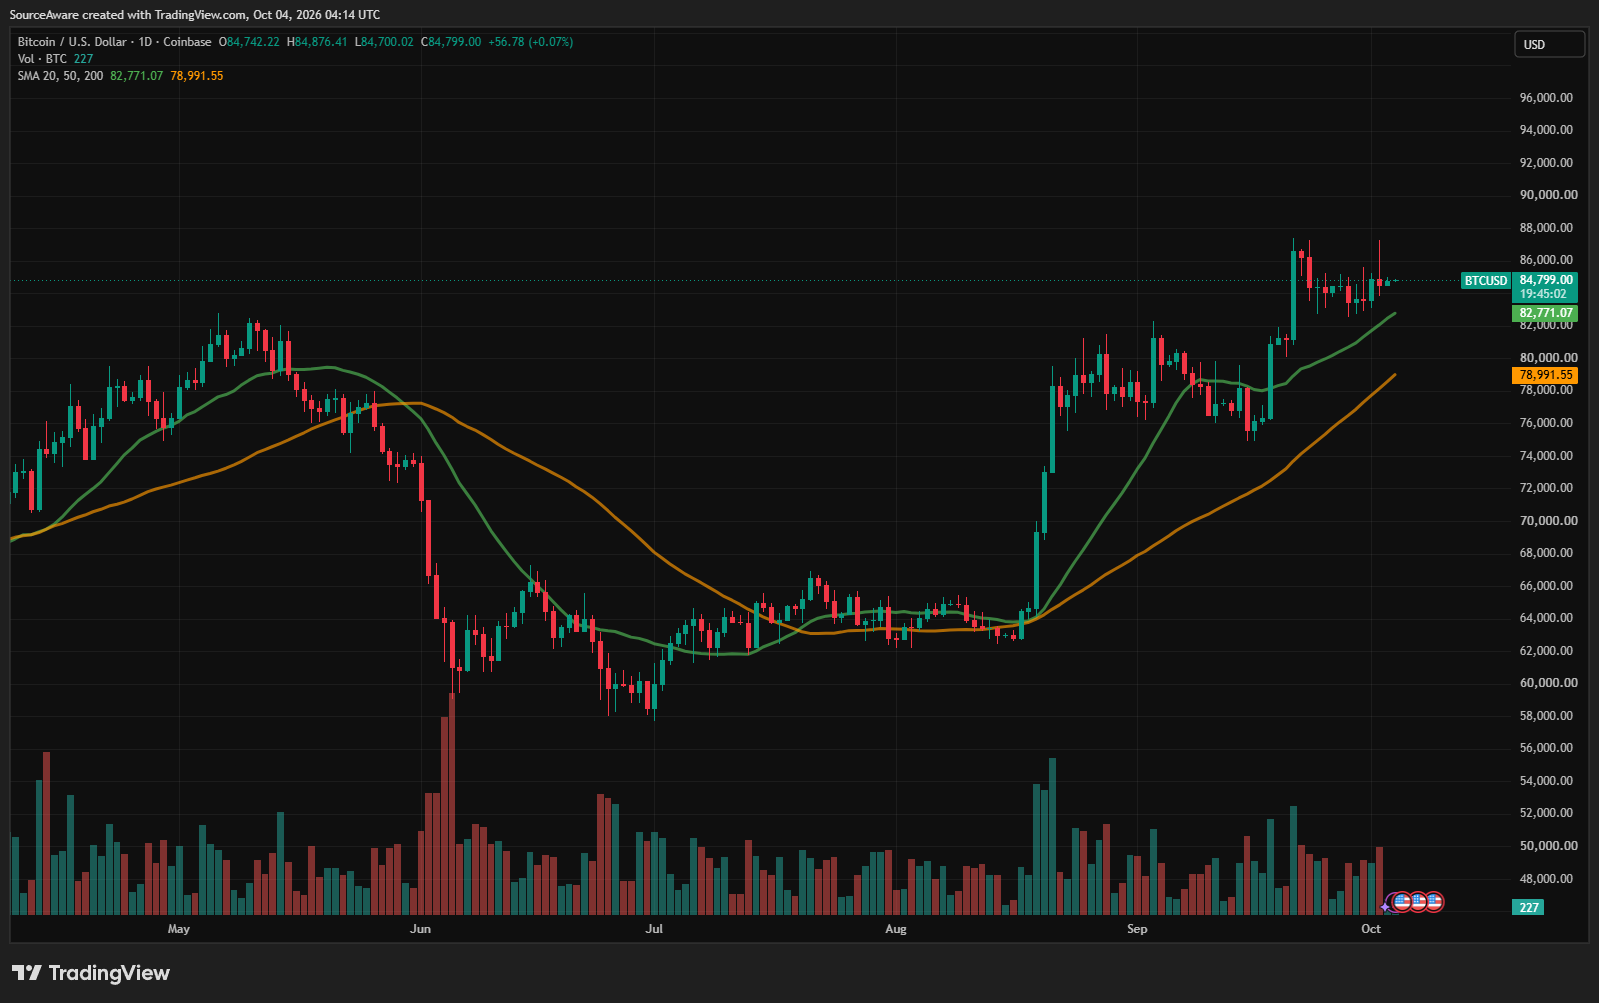
The 20-day simple moving average sits near $82,771 and the 50-day near $78,991. Its modest positive return carries unusual weight because of its market share, helping keep the cap-weighted screen positive while the median asset falls. Bitcoin is the market's high-share benchmark here, rather than its performance leader. The current price remains inside the $82,510 to $87,249 seven-candle range and above both averages.
What Could Confirm—or Challenge—the Breadth Warning
The main friction is the gap between the capitalization headline and the breadth beneath it. A $2.892 trillion market that rose 0.59% over 24 hours and remained slightly positive on the reconstructed weekly screen appears stable in isolation. A market where 63 of the top 100 assets are lower, with a -1.62% clean-screen median, is much more selective.
If the large assets supporting the cap-weighted result encounter resistance, the rest of the market offers no obvious replacement. Payments, established memes, and privacy assets have the week's weakest sector medians, and no second cluster shows comparable positive momentum.
SUI also shows why a positive weekly result can still require restraint. Its post-close gains are modest across all three source windows, while its recent range remains wide. Stablecoin growth creates a similar interpretive trap: the supply series rose, but its timing does not establish deployment into risk assets. Both cases reward restraint over a cleaner but unsupported story.
Can Narrow Leadership Broaden Into a Wider Crypto Recovery?
The constructive case starts with capitalization holding near $2.892 trillion and the reconstructed weekly screen remaining positive at +0.20%. BTC is above both key moving averages, and AAVE has produced genuine individual strength. The market has become more selective without losing its aggregate footing.
The weaker case rests on breadth. The clean-screen median is -1.62%, negative names still outnumber positive names, and BCH's retreat joins losses across payments, memes, and privacy assets. Continued concentration would leave the headline dependent on a narrow group holding firm.
Breadth could narrow further, or stabilization in the largest assets could eventually draw participation wider. This week's data identifies divergence without resolving which path follows.
This leaves the coming sessions with an unresolved test. The headline market cap is stable, and a few names have made large moves. But 63 of the top 100 are lower, weakness remains concentrated in payments, memes, and privacy assets, and the performance holding the aggregate together is narrow. Bitcoin's large share sets the scale of the market; it does not determine what the assets that diverged most sharply from it do next.
Comments
Log in or sign up to join the conversation.