
We expect a 7-2 vote to hike rates this week and, barring a collapse in energy prices, we think a follow-up move in February is likely too. However, market pricing for the Bank of England still looks extreme
The Bank of England is set to raise rates by 25bp to 4% on Thursday.
Higher energy prices set to push inflation above 4%
The Bank of England has so far managed to avoid a rate hike since the start of the Iran war, but that’s about to change. We, like most, expect a hike at its 5 November meeting, and think a follow-up move in February is more likely than not.
Why now? Until now, the Bank would argue it’s been on “active hold”. It was set to cut rates by upwards of 50 basis points this year, so simply not doing that amounted to de facto tightening. By that logic, the Bank has added a similar amount of policy restriction as the European Central Bank, which has lifted its deposit rate twice.
But the worsening energy crisis has made it much harder for the Bank not to act. The spike in natural gas prices means inflation is set to take another leg higher into winter. A circa 25% rise in the regulated cap on household energy bills in January is all but baked in.
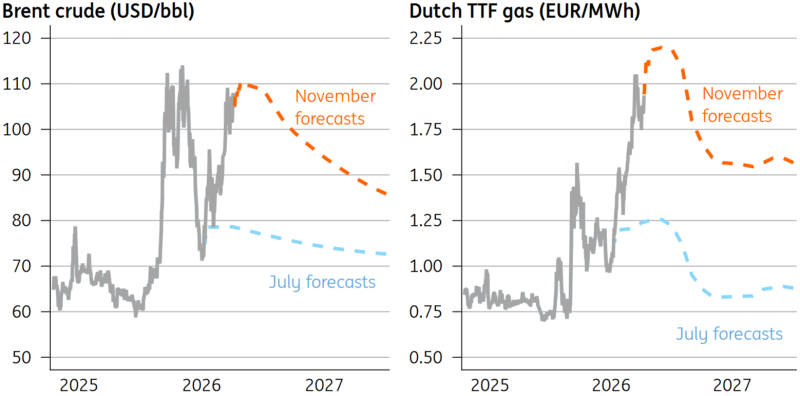
We expect headline CPI to peak a touch above 4% early next year, and we think the BoE's new forecasts will show this too. The Bank’s July projections had inflation reaching 3.2% in late 2026, based on oil below US$80/bbl and natural gas at around half its current level.
Energy prices have risen significantly since the Bank's July forecasts
The Bank is set to hike rates for insurance purposes
4% is an important line in the sand for the BoE. Last summer, the Bank set out research suggesting that second-round effects become more likely once inflation surpasses this level. We suspect this is still front of mind for many officials.
Then again, there is essentially no sign of these much-feared second-round effects so far. Away from motor fuel, inflation has been in line with the Bank’s July forecasts. Our measure of 'energy-intensive' inflation has actually fallen this year, even after accounting for one-off changes in water bills and car tax.
One of the Bank’s favoured measures of ‘core services’ inflation, which strips out volatile and indexed categories, is well-behaved too. And though it has likely bottomed out, private-sector wage growth at 3.4% year-on-year is hardly problematic. Despite signs of stabilisation in the jobs market, there’s little evidence wage pressures are set to build.
True, growth has been much better than feared. But then the Bank has often taken a more sceptical view of the GDP numbers, preferring to look at more benign survey-based measures of activity.
This all leaves the Bank in a strange situation: hiking not because the economic data is telling it to, but because of the risks presented by sharply higher energy prices. The energy crisis has reached sufficient depth and longevity that officials likely feel they, reluctantly, have to act.
'Energy-intensive' inflation hasn't picked up
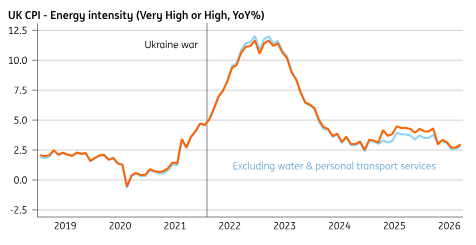
Based on data from the ONS categorising the inflation basket by energy intensity
The key things to watch
So what should we watch at the November meeting?
First, the vote split. We know there are two doves, Swati Dhingra and Alan Taylor, who are deeply sceptical of the need for higher rates. But we suspect the other seven committee members will back a hike. Could there be more dissenters? Governor Andrew Bailey hasn’t sounded hugely enthusiastic about hiking, though a governor has only dissented twice since 1997 and both times in the financial crisis.
So if there is extra dissent, Sarah Breeden looks the most likely candidate, having stressed that most businesses are absorbing the energy shock rather than raising prices. Dave Ramsden is another, less likely, candidate.
Second, there’s the forward guidance. We think the Bank will be as non-committal as possible. Something like: “The Committee will carefully assess the extent to which higher energy prices are propagating into wage and price-setting. The timing and pace of any further increases will depend on the evolution of the inflation outlook. Monetary policy is not on a pre-set path.”
That’s a clever way of saying: we could hike again, but it’s not inevitable.
If there’s going to be a hawkish surprise, it would be if the Bank says something like “some further tightening in monetary policy is likely to be appropriate over the coming months”.
Another rate hike in February seems to be the growing consensus – and our own view too. There’s little precedent for ‘one-and-done’ rate rises. But it’s one thing thinking that, another saying it out loud. There’s a lot that can happen between now and February. And having made a hawkish misstep all the way back in March, when the Bank sounded open-minded about tighter policy, opening the floodgates for markets to price in rate hikes, it’ll want to tread carefully here.
A more dovish formulation would be if the Bank makes further hikes explicitly contingent on second-round effects: one hike as an insurance move, but anything more requiring solid data. For example, “If there were evidence of more persistent second-round effects in wage and price-setting, further tightening in monetary policy would be required”.
Finally, watch the individual member paragraphs tucked away in the minutes. Does anyone formally push back against market pricing, which has more than four hikes priced by this time next year? Even Chief Economist Huw Pill, one of the hawks, has recently indicated that such pricing looks unlikely.
The impact on rates markets
Even if the Bank does choose to push back, will markets listen?
A simple model of two-year swap rates against oil, natural gas, equity markets and the equivalent USD and EUR rates shows that these global factors are explaining less of the daily movement in sterling rates than they were over the summer.
Global factors are explaining less of GBP rates moves
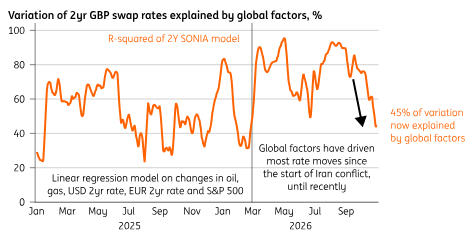
Indeed, the dovish repricing that we’ve seen for the Federal Reserve and European Central Bank has not been mirrored in the UK. Perhaps it’s because Britain lacks a story like France has or, in America’s case, AI fears. But robust UK growth data may also be playing a role. Economic surprise indices have been touching multi-year highs.
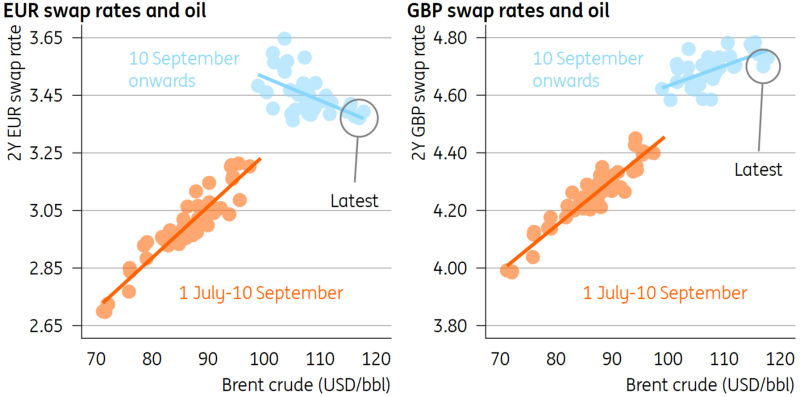
Still, UK swap rates remain deeply correlated with oil prices. And barring a big surprise, and with more than 100bp of hikes already priced, it’s hard to see the Bank triggering a substantial repricing of rate expectations at this meeting.
GBP rates remain positively correlated with oil - unlike EUR rates
The impact on the pound
Sterling is trading reasonably well, helped by the view that high energy prices leave the Bank of England no alternative but to hike rates on Thursday.
Upside economic surprises, UK fiscal policy seemingly heading in the right direction and warmer ties with the EU all seem to be helping sterling too. Notably, speculators are still running reasonably large short positions in sterling, which suggests this period of sterling outperformance can continue.
EUR/GBP has come a long way very quickly – a near 4% drop in a little over a month. Some consolidation is probably due. But with high energy prices likely to keep expectations of higher UK policy rates in place until early next year and French budgetary problems unresolved, it is too early to expect a significant low in EUR/GBP.
Comments
Log in or sign up to join the conversation.