
AutoZone, Inc. (AZO) generated strong FCF margins for fiscal Q4. As a result, AZO stock could be too cheap - 28% undervalued - based on analysts' forecasts, price targets, and its historical P/E.
AZO is at $2,850.96 on Sept. 24, but it's well off its 3-month peak of $3,218.15 on July 1. Recently, the stock bottomed out on Sept. 21 at $2,803.25, right before its Sept. 22 Q4 earnings release.
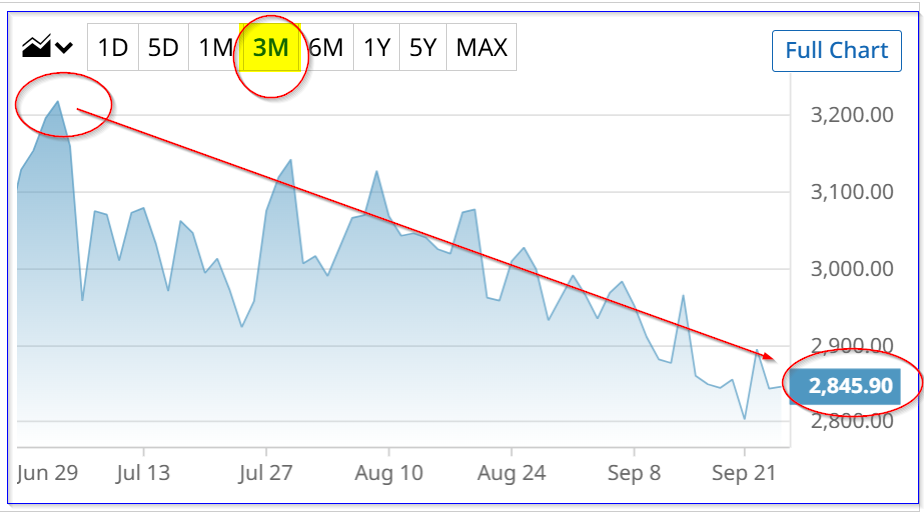
AZO stock - last 3 months - Barchart - Sept. 24
Strong Q4 Results
This earnings report for the quarter ending Aug. 29, 2026 should give investors some comfort, as sales rose 5.6% YoY, including 1.5% same-store sales growth. Moreover, Q4 diluted earnings per share (EPS) rose 17.5% YoY, and fiscal-year EPS was up 5.3%.
In addition, AutoZone generated strong cash flow. Its operating cash flow (OCF) was $1.183 billion, up 19.5% YoY, and free cash flow (FCF) was $684.0 million, +33.8% YoY ($511.12 million).
Moreover, that FCF represented 10.37% of its Q4 revenue, 25.6% over its prior-year Q4 FCF margin of 8.19%. In other words, with higher sales, AutoZone has squeezed out even higher cash flow.
That is seen in its full-year FCF margin. In FY 2026, it generated $1.8066 billion in FCF ($3.303b OCF less $1.496b capex taken from the earnings release), on sales of $20.339 billion, or an 8.88% FCF margin. (Note: these are not final figures as the company has not yet produced a cash flow statement.)
That is much better than $1.79 billion in FCF (i.e., a 9.45% FCF margin, according to Stock Analysis data).
As a result, AutoZone is still generating strong cash flow. Given that analysts have higher revenue and earnings forecasts, this could lead to a higher valuation and price targets for AZO stock.
Higher AZO Price Targets
There are three ways to value AZO Stock. The first is an FCF model, the second is analysts' price targets, and the third uses historic P/E metrics.
FCF Model. For example, analysts now forecast revenue for the year ending August 2027 will be $21.84 billion, up +7.38% YoY. Moreover, for the next year, they forecast $23.39 billion, up another 7.1%.
The bottom line is that people still want to take care of their cars. After all, the value of used cars is climbing, and they are a major asset of most households.
As a result, if same-store sales keep climbing, and AutoZone maintains an 8.88% FCF margin, FCF should reach $1.92 billion (i.e., $21.84b x 0.088) this coming year and $2.06 billion in the following year.
As a result, the market will likely value the FCF at at least a 3.5% FCF yield, its existing metric:
2027: $1.92b / 0.035 = $54.86 billion fair market value (FMV)
2028: $2.06b / 0.035 = $58.86 billion FMV
Today, its market cap is $46.16 billion, according to Yahoo! Finance. That implies its price target is anywhere from 18.8% to 26.3% higher, or 22.55% on average:
$2,848 pr x 1.2255 = $3,490 price target (PT) +22.6%
Analysts' PT. For example, Yahoo! Finance's survey of 27 analysts is for an average PT of $3,715.70, and Barchart's mean survey PT is $3,708.23. Those PTs are 30.6% and 30.2% higher than today's price.
P/E Averages. Over the last five years, AZO has had an average 5-year forward price/earnings (P/E) ratio of 20.65x, according to Seeking Alpha. Morningstar reports that the average 5-year ratio has been 19.29x. These both average 19.97x, higher than its present forward P/E ratio.
For example, analysts project EPS this coming year of $171.35 and $191.97. That puts AZO stock on a forward P/E of just 16.6x and 14.85x.
So, applying a 20x multiple, AZO is worth between $3,427 (i.e., $171.35 x 20) and $3,838 per share, or $3,632.50 on average. That's 32% over today's price.
Summary and Conclusion
AutoZone is generating strong same-store sales, operating cash flow, and higher FCF margins. As a result, it should be worth more over the next year. Based on an FCF model, it's worth 22.5% more; analysts have 30.4% higher PTs, and its average P/E implies it should be worth 32% more.
So, on average, AZO has at least 28.3% upside, or a PT of $3,656 per share.
Comments
Log in or sign up to join the conversation.