
Australia: RBA expected to hike rates by 25bp
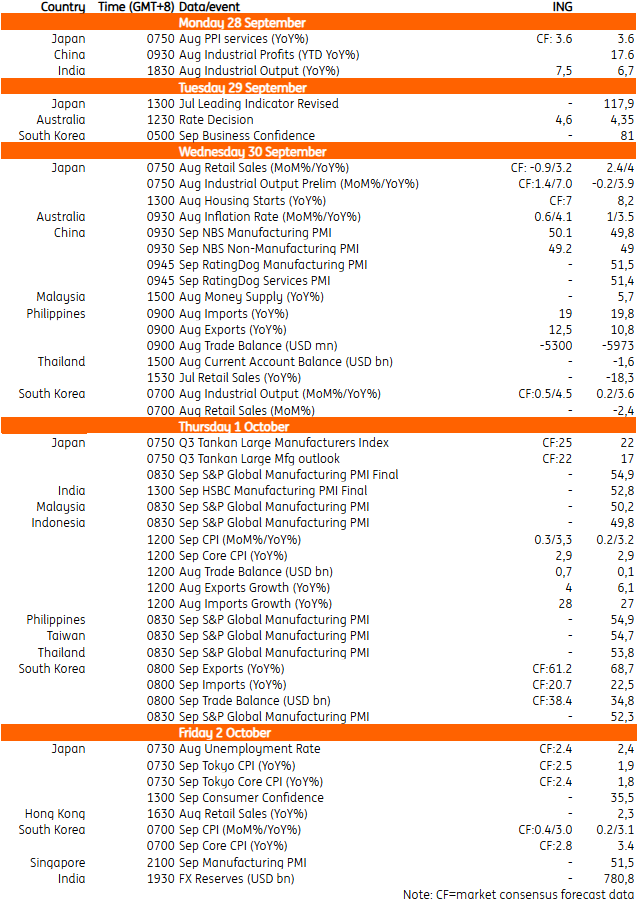
We expect the Reserve Bank of Australia RBA to deliver a decisive 25bp rate hike on Tuesday, reflecting an economy that continues to run hot across multiple fronts. Labour market conditions remain tight, second-quarter GDP growth surprised to the upside, and recent inflation readings came in stronger than expected. While the housing market shows signs of cooling, we expect the RBA to emphasise that risks remain tilted to the upside and further vigilance is required to ensure prices return sustainably to target.
Separately, August CPI data is likely to accelerate further to 4.1% year-on-year, driven primarily by higher diesel and food prices, alongside persistent underlying core inflation pressures.
China: PMIs expected to slow a modest recovery
China releases September purchasing managers’ index data on Wednesday. We look for the National Bureau of Statistics to report a slight recovery in its official manufacturing and non-manufacturing PMIs to 50.1 and 49.2, respectively. The RatingDog PMI, which has generally outperformed lately because of its more export-oriented sample, is out the same day. Industrial profits data is out Monday. Growth in the series has been moderating over the past 3 months, even as overall profits have improved from previous years.
Japan: Activity and inflation data in focus
Japan releases its August services PPI on Monday. Market consensus is for services inflation to remain unchanged at 3.6% YoY, indicating that price pressures in the sector remain firm. Retail sales growth is expected to moderate to 3.2% YoY, from 4.0% in July. Sales are forecast to decline 0.9% month-on-month after the previous month’s 2.4% increase. Industrial production is expected to rebound 1.4% MoM, lifting annual growth to 7.0% YoY from 3.9%. The quarterly Tankan survey is expected to show improvement in business sentiment among large manufacturers. The index is expected to rise to 25 from 22, while the outlook is seen rising to 22 from 17.
Tokyo inflation data will be released on Friday. Market consensus is for headline inflation to accelerate to 2.5% YoY, from 1.9%, while core prices rise to 2.4%, from 1.8%. This pickup would suggest that price pressures remain elevated.
South Korea: Trade surplus to widen as inflation eases
South Korea releases August industrial production data on Wednesday. Market consensus expects industrial production growth to accelerate to 4.5% YoY, from 3.6% in July. Monthly output is forecast to rise 0.5%. September trade data, out Thursday, is expected to show a moderation in both export and import growth to 61.2% YoY and 20.7% YoY, respectively. Despite slower growth, the trade surplus is forecast to widen to $38.4bn, supported by continued strength in technology and semiconductor exports. Headline CPI inflation is expected to ease to 3.0% YoY in September, from 3.1% in August. Core inflation is forecast to slow more sharply to 2.8% YoY, from 3.4%.
Indonesia: Inflation set to accelerate on food pressures
We expect Indonesia’s CPI inflation to accelerate to 3.3% YoY, as El Niño drives further increases in food prices. Rising rice prices should remain a key driver, while spillovers from higher food costs are also likely to add to core inflation.
Key events in Asia next week
Comments
Log in or sign up to join the conversation.