
Philippine GDP is the highlight of the week, alongside China’s inflation and trade data, Taiwan’s trade figures, and Japan’s household spending and price indicators.
Philippines: GDP growth to rebound on public spending and manufacturing strength
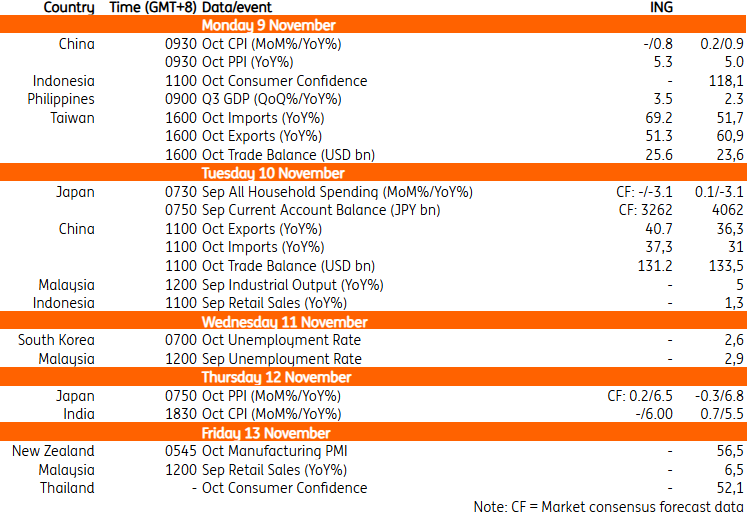
We expect GDP growth to recover to 3.5% year-on-year in the third quarter. This will be driven by a gradual normalisation in government spending and continued strength in the manufacturing sector, which is also reflected in robust electronics export growth. However, private consumption is likely to remain subdued as consumer sentiment stays weak amid still-soft public spending and elevated inflation, particularly from higher energy prices. While external demand and manufacturing should provide support to growth, the recovery in domestic demand is likely to be more gradual.
China: Trade to remain strong as inflation edges lower
China will release October inflation and trade data. We expect CPI inflation to edge down to 0.8% YoY, from 0.9% in September, suggesting that consumer price pressures remain subdued amid continued weakness in domestic demand. By contrast, PPI inflation is expected to rise further to 5.3% YoY, from 5.0%, driven mainly by elevated energy and commodity prices.
Export and import growth are expected to accelerate to 40.7% YoY and 37.3% YoY, respectively amid resilient external demand for technology-related and manufactured goods and increased commodity imports. The trade surplus is expected to narrow slightly to $131.2bn, from $133.5bn in September, as import growth accelerates.
Taiwan: Technology demand supports strong trade
Taiwan releases October trade data on Monday. We expect export growth to moderate to 51.3% YoY, from 60.9% in September. Even so, growth should remain exceptionally strong, supported by demand for semiconductors and other AI-related products. Imports are expected to accelerate to 69.2% YoY, from 51.7%, reflecting strong demand for semiconductor equipment, components and advanced materials. Despite faster import growth, the trade surplus is forecast to widen to $25.6bn, from $23.6bn in September, highlighting the continued strength of Taiwan’s technology export cycle.
Japan: Household spending, current account and producer prices in focus
Japan will release September household spending and current account data. The market expects household spending to remain weak, falling 3.1% YoY, unchanged from August, highlighting continued pressure on domestic consumption. The current account surplus is forecast to narrow to JPY 3262bn, from JPY 4062bn.
Japan’s October PPI will be released on Thursday. Market consensus expects producer price inflation to moderate to 6.5% YoY, from 6.8% in September. Prices are forecast to rise 0.2% month-on-month following a 0.3% decline. This suggests that upstream price pressures are gradually easing, though they remain elevated, keeping expectations for further BoJ policy normalisation firmly in focus.
Key events in Asia next week
Comments
Log in or sign up to join the conversation.