
Rate decisions take center stage, with Bangko Sentral ng Pilipinas expected to raise rates while Bank Indonesia and the Bank of Korea are likely to stand pat. Markets will also closely watch China's GDP and Japan's inflation figures.
Indonesia: Bank Indonesia expected to hold rates
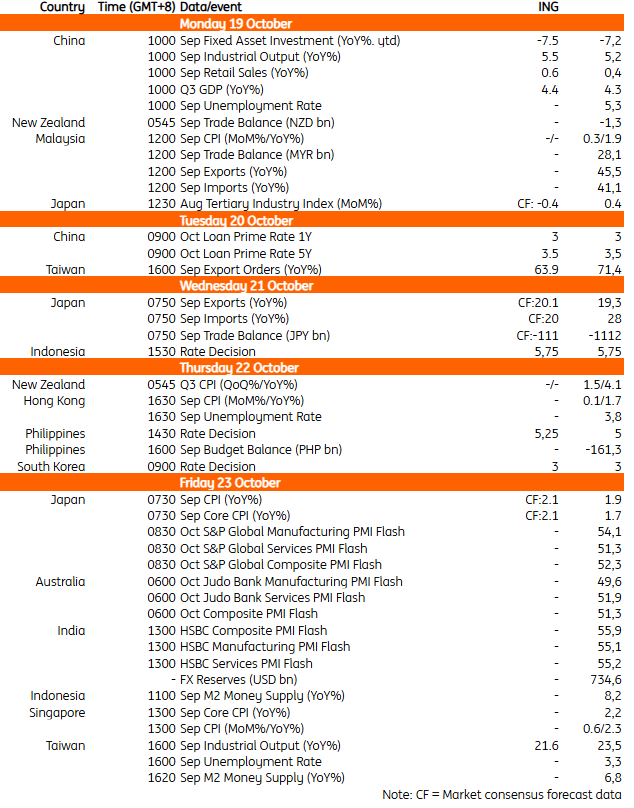
We expect Bank Indonesia to leave the policy rate unchanged at 5.75% on Wednesday given recent exchange-rate stability. Although improving sentiment has eased near-term pressure on policymakers to hike, the underlying balance-of-payments picture hasn’t improved materially. At the same time, upside risks to inflation from higher fuel prices and a severe El Niño could add to domestic price pressures. We therefore still expect one more 25bp rate hike before year-end.
Philippines: BSP expected to hike rates by 25bp
We maintain our call for Bangko Sentral ng Pilipinas to hike rates by 25bp on Thursday. Strong September inflation shifted the balance in favour of an earlier October hike. The outlook remains skewed to the upside amid uncertainty over El Niño-related food supply disruptions, elevated energy prices, PHP weakness, and potential second-round effects from higher wages and food costs. BSP is likely to err on the side of caution and maintain a tightening bias to tame inflation expectations until it’s confident prices are on a path back to target.
Korea: BoK expected to hold rates
We expect the Bank of Korea to keep its policy rate unchanged at 3.0% on Thursday. However, the pause is unlikely to mark the end of the tightening cycle. Inflation remains above target and economic growth is relatively resilient. The market will focus on the BoK’s updated outlook and guidance on whether it will hike rates again before year-end.
China: Third quarter GDP and activity data in focus
China has a busy week ahead, starting with key data releases on Monday. The highlight will be China’s third-quarter GDP. We look for growth of around 4.4% year-on-year. We’ll also get September domestic activity data. We expect retail sales and industrial production to recover slightly to 0.6% and 5.5%, respectively. But fixed asset investment is expected to continue contracting to -7.5% YoY ytd. The 70-city property price data for September will also be released. We’ll be watching whether price stabilisation in tier-1 cities continues and spreads further. On Tuesday, the loan prime rates will be announced. We expect no change once again, with 1- and 5-year LPR unchanged at 3.0% and 3.5%, respectively.
Japan: Trade and inflation data in focus
Japan releases data on services activity, trade and inflation. Market consensus expects the tertiary industry index to decline 0.4% month-on-month in August. September export growth is forecast to edge up to 20.1% YoY, while imports slow to 20.0% YoY, narrowing the trade deficit sharply to JPY111bn from a revised JPY1,112bn in August. Headline and core CPI are both expected to accelerate to 2.1% YoY. A firm inflation reading would support expectations for further Bank of Japan policy normalisation.
Key events in Asia next week
Comments
Log in or sign up to join the conversation.