
Last week, a supertanker loading crude in the Gulf of Oman was fixed at $1.01 million a day for a voyage to Asia, with another deal reportedly agreed at $1.16 million. Bloomberg Intelligence says the benchmark rate for these very large crude carriers, or VLCCs, hit a record $907,635 a day on October 6 and could cross $1 million before the month is out.
Back in March, I wrote that shipping stocks had caught a windfall as freight markets went vertical. Like most, I expected the conflict with Iran to be intense but brief. It’s lasted far longer than I or most of Wall Street anticipated, and the windfall has grown into one of the most profitable stretches the shipping industry has seen.
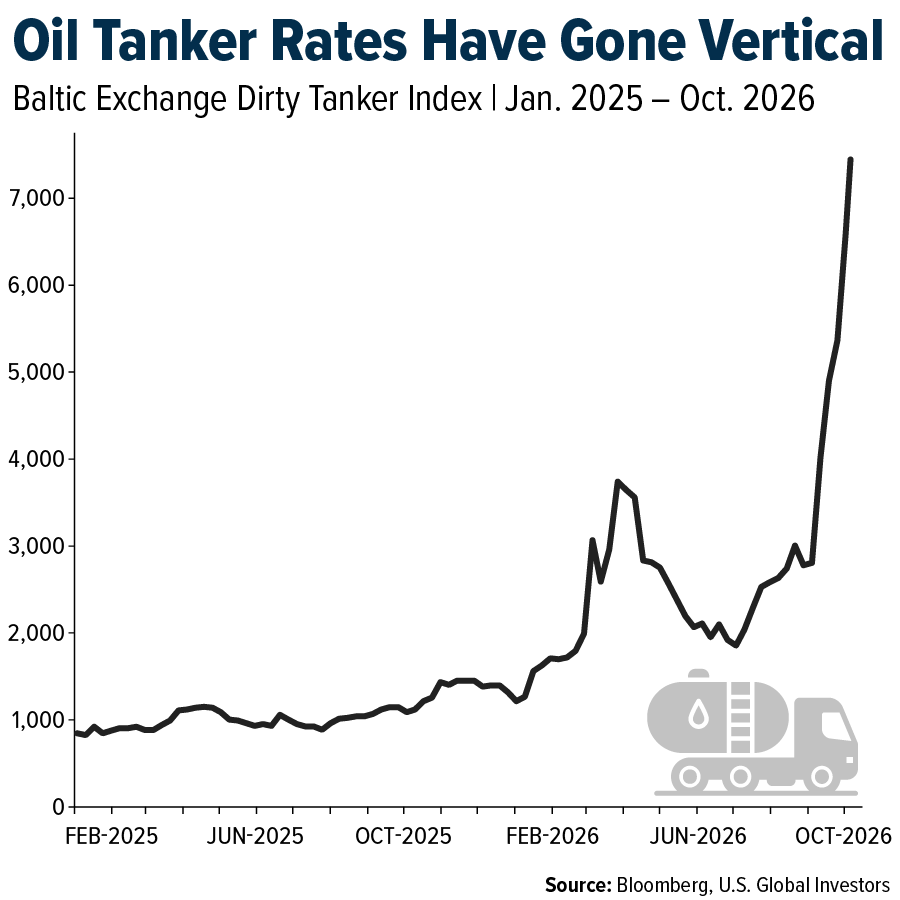
The Baltic Exchange Dirty Tanker Index, which tracks the cost of shipping crude oil across dozens of routes, stood at 7,444 last Tuesday. That’s more than six times where it was a year ago and the highest reading in Bloomberg data going back to 2010.
Every Detour Takes a Ship Off the Market
So what’s driving this? In a word, inefficiency.
Both of the Middle East’s key checkpoints, the Strait of Hormuz and the Bab el-Mandeb, remain under active threat. Much of the crude leaving the Persian Gulf is now shuttled out in smaller tankers under the protection of U.S. naval forces, then transferred onto supertankers in the Gulf of Oman. Many vessels are still sailing the long way around Africa.
These detours can keep a ship at sea for days or weeks longer than the trip would normally take, and a ship that’s stuck at sea or waiting at anchor can’t haul the next cargo. C.H. Robinson (CHRW) estimates that roughly 12% of global container ship capacity is currently tied up by port congestion alone.
Factories and Ports Are Running Hot
If disruption were the whole story, I’d be skeptical this boom could last. But demand is strong too.
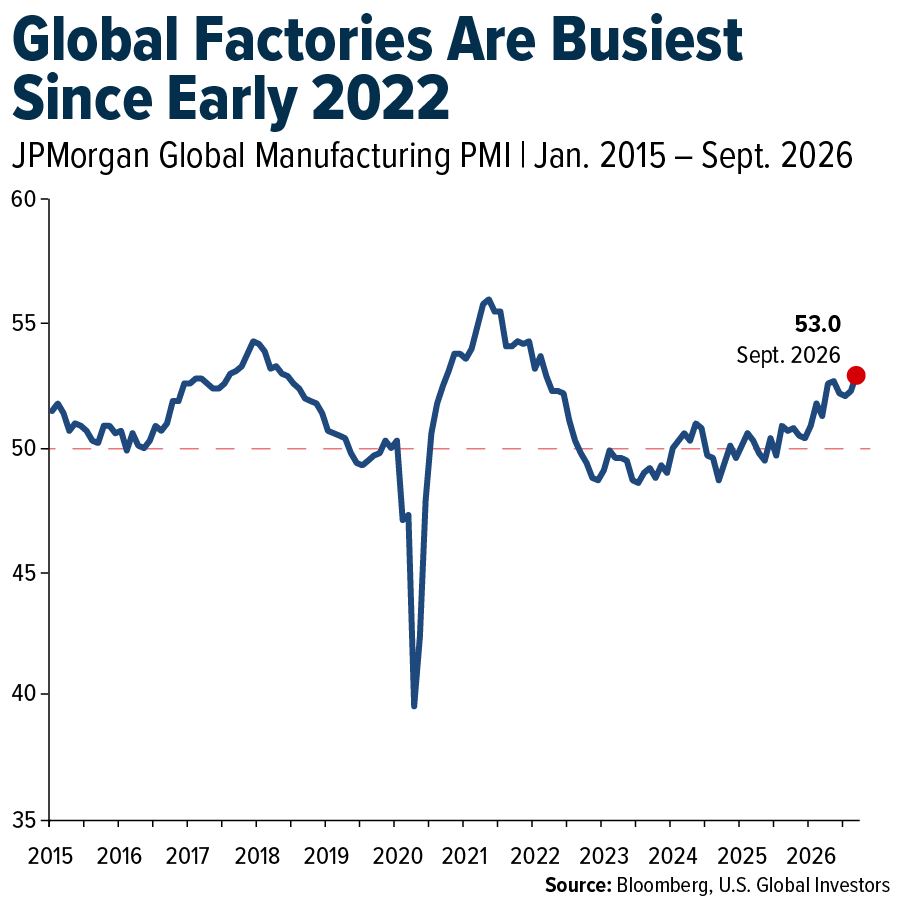
The JPMorgan Global Manufacturing PMI rose to 53.0 last month, its highest level since February 2022. S&P Global credits spending on AI infrastructure and defense equipment, along with companies building inventory out of fear of further supply disruptions. Across the broader economy, new export business grew at the fastest pace in more than five years.
As I’ve said many times before, the PMI has historically been a useful leading indicator of demand for goods and commodities, and right now it’s flashing green.
Trade data tell the same story. Global goods trade grew faster in the first half of 2026 than in any half-year in the past 15 years apart from the post-Covid rebound, according to DHL. AI-related goods such as semiconductors accounted for 76% of that growth in the first quarter.
That demand is showing up at America’s ports, even with consumer confidence sitting at a 12-month low. The Port of Los Angeles just wrapped up the busiest three-month stretch in its history, and import volume headed for Long Beach over the next three weeks is running roughly 50% above year-ago levels.
Container Rates Are Near Records on Routes to America
The Shanghai Containerized Freight Index, a broad measure of spot rates for ships leaving China, has more than tripled over the past year. It’s still about 28% below the record it set in January 2022.
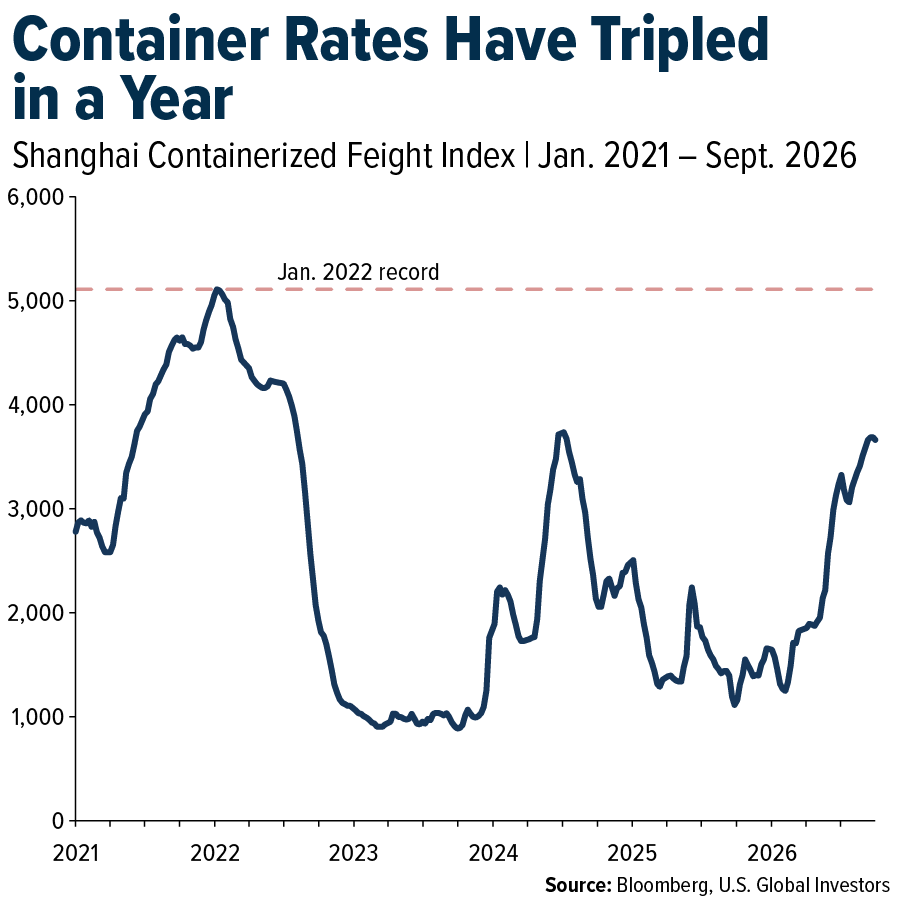
The index hides a split, though. Rates on routes to Europe are cooling as some services return through the Suez Canal. Drewry’s World Container Index shows the cost to ship a 40-foot container from Shanghai to Rotterdam has fallen about 31% since July.
Routes to the U.S. are going the other way. That same container from Shanghai to New York now costs $10,428, up 78% since mid-June, and rates on the route between North Asia and the East Coast of the U.S. are within about $200 of their all-time high set in April 2022.
Interestingly, shipping a 40-foot container from Shanghai to L.A. costs $7,835, but shipping it back costs only $791, roughly a tenth as much.
Record Profits Across the Industry
Elevated rates are a tide that lifts all boats, and carriers’ earnings guidance shows it. Hapag-Lloyd (HPGLY) started the year forecasting anything from a $1.3 billion loss to a $400 million profit. The company has since raised its outlook twice and now expects 2026 operating earnings (EBIT) of $1.25 billion to $1.75 billion.
Zim (ZIM), Maersk (AMKBY), Ocean Network Express and Matson (MATX) have all raised their outlooks this year as well.
Tanker owners are cashing in too. Teekay Tankers (TNK) reported record second-quarter adjusted net income of $193.6 million, or $5.56 per share, and ended June with more than $1.2 billion in cash and short-term investments.
High Rates Are the Cure for High Rates
As many of you are aware, shipping is a cyclical business, and boom times like this have a way of planting the seeds of the next bust.
Shipowners are flush with cash right now, and they’re spending it on new vessels. According to Hellenic Shipping News, some 198 VLCCs have been ordered so far this year, compared with 89 in all of 2025. The tanker orderbook now equals 37% of the existing fleet. The container orderbook has reached 13 million TEUs, or roughly 37% of the global fleet’s current capacity of 34.8 million TEUs, according to Alphaliner. That’s more than the combined fleets of Maersk, CMA CGM and COSCO.
Those ships won’t all arrive at once, but they will arrive. Tanker supply growth is expected to outpace demand starting in 2027. And whenever the Red Sea and Hormuz fully reopen, the vessels now sailing the long way around will be freed up for other work, effectively adding capacity overnight.
Wall Street appears to see this coming. Consensus estimates for tanker owners show quarterly earnings peaking this quarter and drifting lower through mid-2027, according to Bloomberg.
For investors, I believe this argues for staying engaged with the sector while keeping a close eye on the orderbook. Cash flows are extraordinary right now. But the cure for high rates is high rates, and the world’s shipyards are already busy filling that prescription.
Comments
Log in or sign up to join the conversation.