
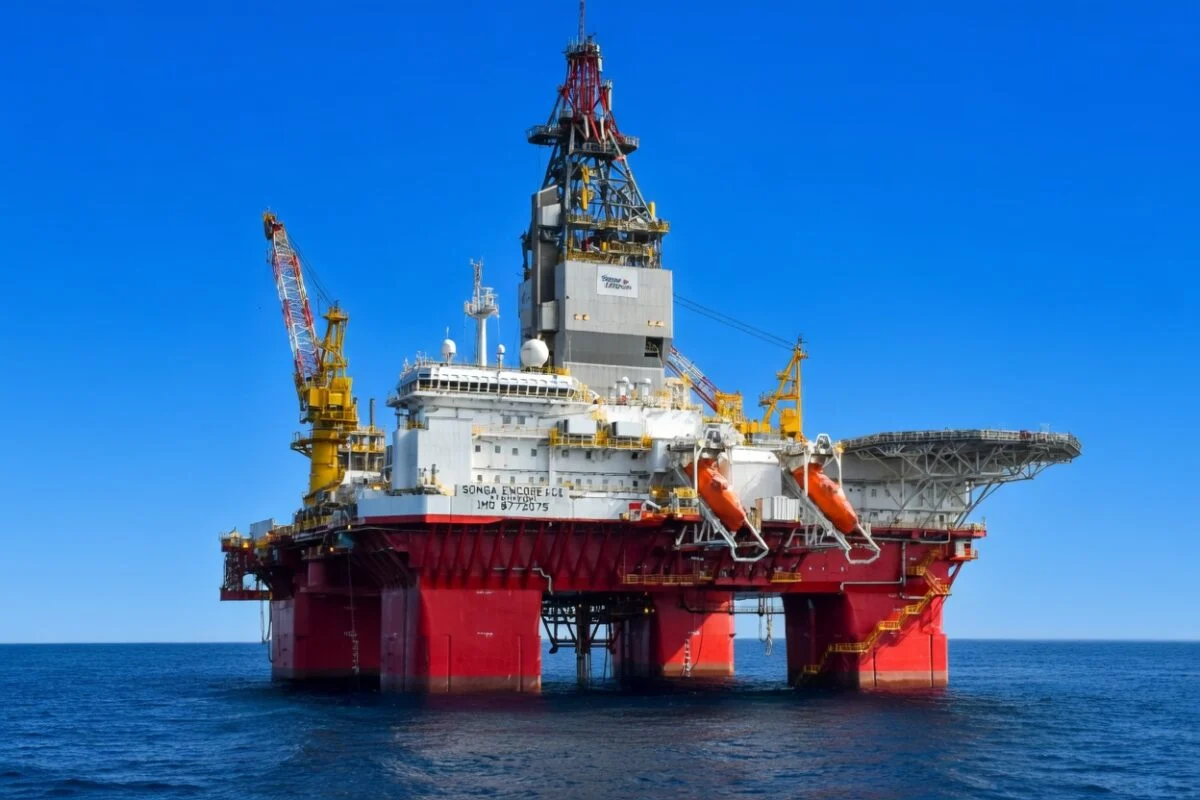
Oil stocks are back in focus this September as crude prices stay elevated and geopolitical tensions continue to disrupt global energy markets. Brent crude was trading around $103 a barrel on September 17, while West Texas Intermediate held close to $100.
Prices have eased from recent highs as Saudi Arabia redirects supplies. However, concerns around Middle East production and shipping routes are keeping the market tight.
For investors, the key question is which energy companies have the balance sheets, production growth and shareholder-return policies to perform over the longer term. Three names stand out: Chevron (CVX), Exxon Mobil (XOM) and ConocoPhillips (COP).
Chevron: Record Output and Strong Earnings
Chevron has emerged as one of the strongest large-cap energy companies heading into the final months of 2026. The company reported $12.1 billion in second-quarter earnings.
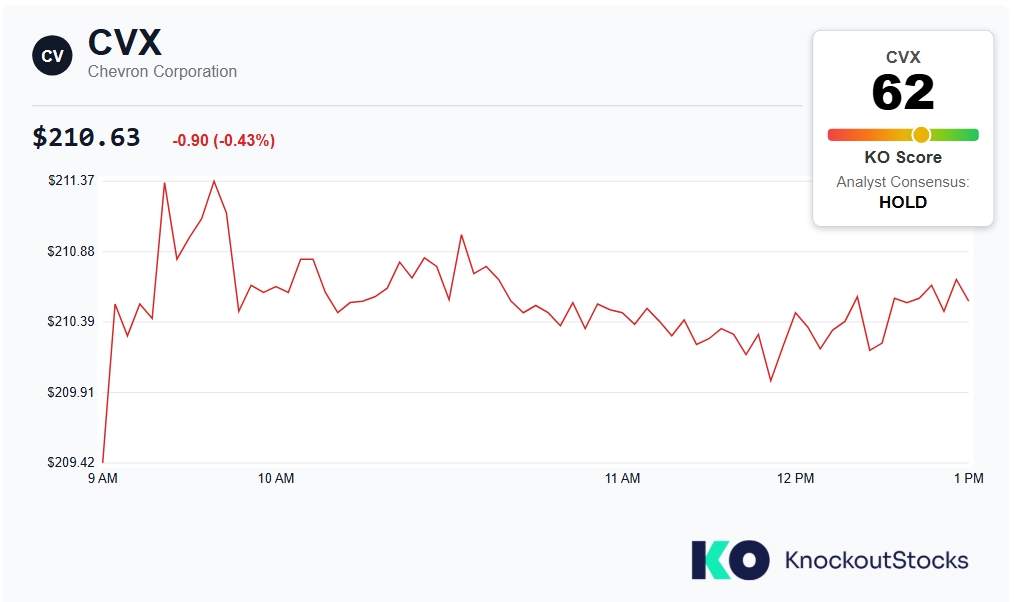
Worldwide production increased 20% year over year. Chevron also achieved record U.S. production and record crude throughput at its American refineries.
Those numbers matter because Chevron is not relying solely on higher oil prices to grow earnings. The company has been growing production while continuing to invest in major international oil and natural gas projects.
That combination of volume growth and strong cash generation puts Chevron in a solid position heading into Q4. Investors have taken note of the company’s ability to perform even as prices fluctuate.
Exxon Mobil: Scale and Downstream Strength
Exxon Mobil remains one of the largest integrated energy companies in the world. Its scale gives it an edge in both upstream production and downstream refining operations.
The company has continued to benefit from elevated crude prices in 2026. Its refining business adds a layer of earnings stability that pure-play producers do not have.
Exxon has also maintained a focus on returning cash to shareholders through dividends and buybacks. That policy has made it a consistent choice for income-focused investors.
ConocoPhillips: Lean and Focused on Returns
ConocoPhillips takes a different approach. The company operates without a downstream refining business, keeping its focus entirely on exploration and production.
That lean model means ConocoPhillips is highly sensitive to oil prices, but it also runs with lower overhead costs. When crude prices are elevated, the company generates strong free cash flow.
ConocoPhillips has built a reputation for disciplined capital spending. It has consistently prioritized shareholder returns over aggressive expansion.
With Brent crude above $100, the conditions are favorable for all three companies. Each brings a different risk and return profile, giving investors options depending on their strategy.
Oil market conditions can shift quickly, but for now the fundamentals support a constructive outlook for large-cap energy stocks heading into the end of 2026.

Comments
Log in or sign up to join the conversation.