
Nike Earnings Preview
Nike will release Q1 fiscal earnings on October 1.
The athletic apparel maker is expected to report EPS of $0.44, down around 10% year on year, and revenue of $11.35 billion, down around 2.6% annually. The share price trades at its lowest level since 2014.
A key concern centres around North America, where wholesale revenue grew 14% in fiscal 2026, even as total sales remained flat. Such a divergence masks a troubling dynamic: retailers are receiving more products than consumers are actually buying.
China also needs to become a growth engine. For Nike, this has become a major source of concern. Greater China sales fell 17% on a constant-currency basis in Q4. Nike's reduction in partner online sales will likely cause promotional pressures through the second quarter as well. Competition is intense.
With sales under pressure, Nike's earnings and outlook increasingly depend on gross-margin expansion and cost control, creating downside risk if execution falls short.
The sector as a whole has seen a wave of negative signals. Lululemon Athletica lowered its fiscal 2026 guidance early this month due to a changing market environment. Under Armour also cut its full-year revenue outlook due to weak demand in North America and Asia Pacific. Meanwhile, Swiss sportswear company On Holding recently unveiled its medium-term financial targets, reaffirming its 2026 outlook.
Analysts across Wall Street are growing increasingly sceptical about Nike's near-term prospects, with analysts lowering their price targets. Five analysts have downgraded Nike since the beginning of August. Of the 44 analysts covering the stock, 26 maintained a hold rating.
The share price has come under relentless pressure, falling 44% year to date against a 12% gain for the S&P 500.
How to Trade NKE Earnings
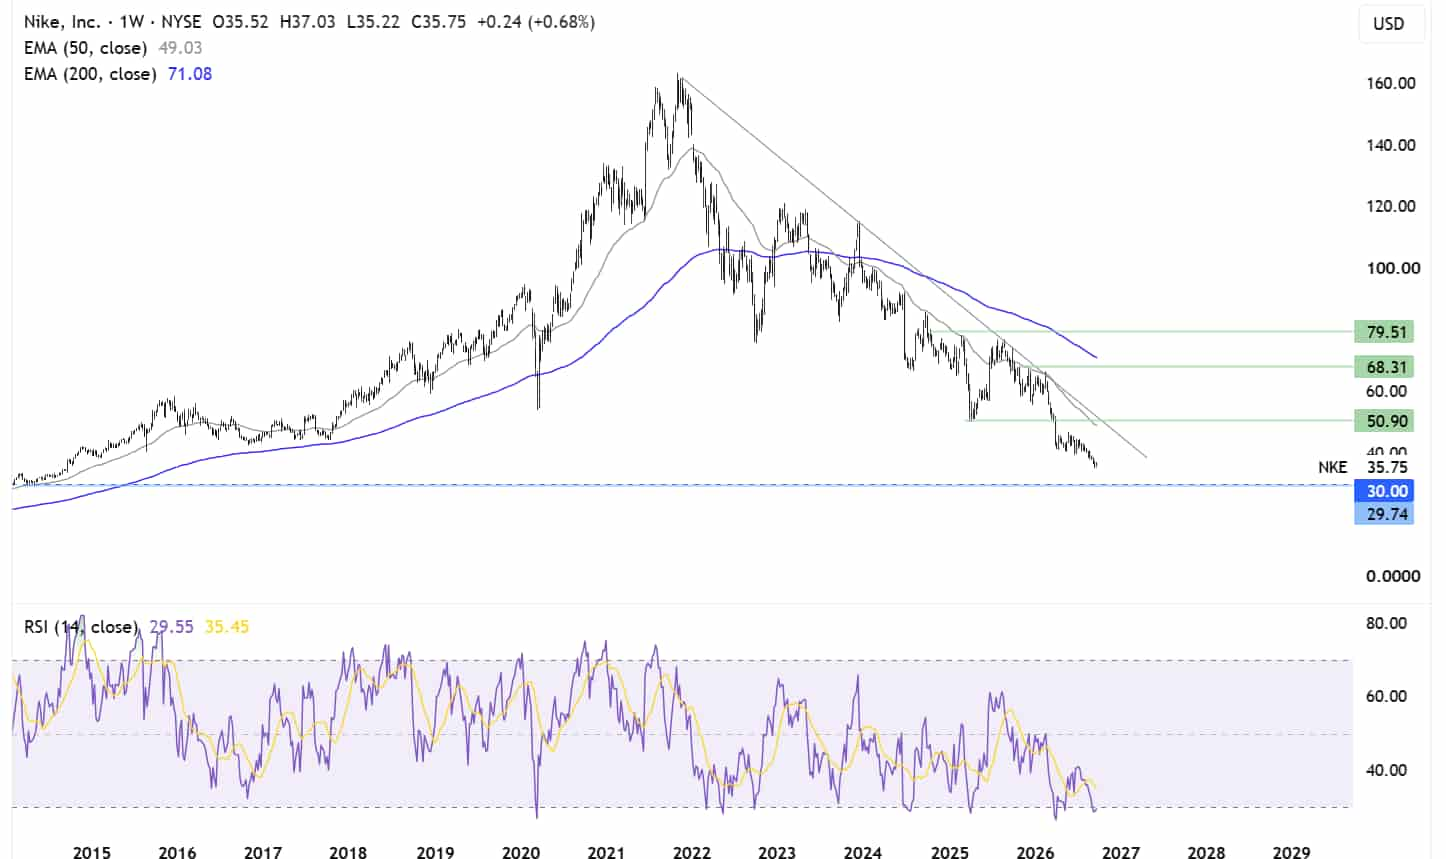
Nike's share price has fallen to $35, a level last seen back in 2014. The price trades on the weekly chart below its falling trend line, with the 50 and 200 EMAs also pointing to a bearish picture.
Sellers will look to extend declines towards $30 as the next logical target.
On the upside, buyers would first need to retake the 50 MA and the falling trendline resistance at $51, which also coincides with the April 2025 low. A rise above here exposes $68, the 2026 high.
It would take a rise above the 2025 high to create a higher high and change the structure of the chart.
Micron Technology earnings preview
Micron will release fiscal Q4 2026 earnings on September 30 after the market close.
Looking back to the release of fiscal Q3 results, the share price surged 15% following the release, as the favourable operating environment translated into strong growth.
Micron is expected to benefit from ongoing strength in its data centre business. In addition, higher average selling prices should translate into strong margin expansion and earnings growth, supporting the share price.
Demand for memory products continues to exceed supply, and this dynamic is expected to keep pricing conditions favourable in the near term.
Micron's data centre revenues surpassed $25 billion in fiscal Q3, implying an annualised run rate of above $100 billion. Momentum in this area is expected to continue into Q4 and beyond as AI drives significant data centre growth.
In Q3, the company reported revenue of $41.5 billion, a 74% sequential increase and a 346% year-over-year increase. Expectations are for Q4 revenue of around $50 billion, marking a sequential increase of around 20%.
AI is key to the outlook, with the rapid expansion of AI computing increasing demand for high-performance memory in data centres. At the same time, supply has not kept pace with demand, creating conditions that allow memory manufacturers to lift prices and improve margins.
Micron projects a Q4 gross margin of 86%, compared with 84.9% in Q3, and margin expansion is expected even as the pace of memory price increases moderates.
How to Trade MU earnings?
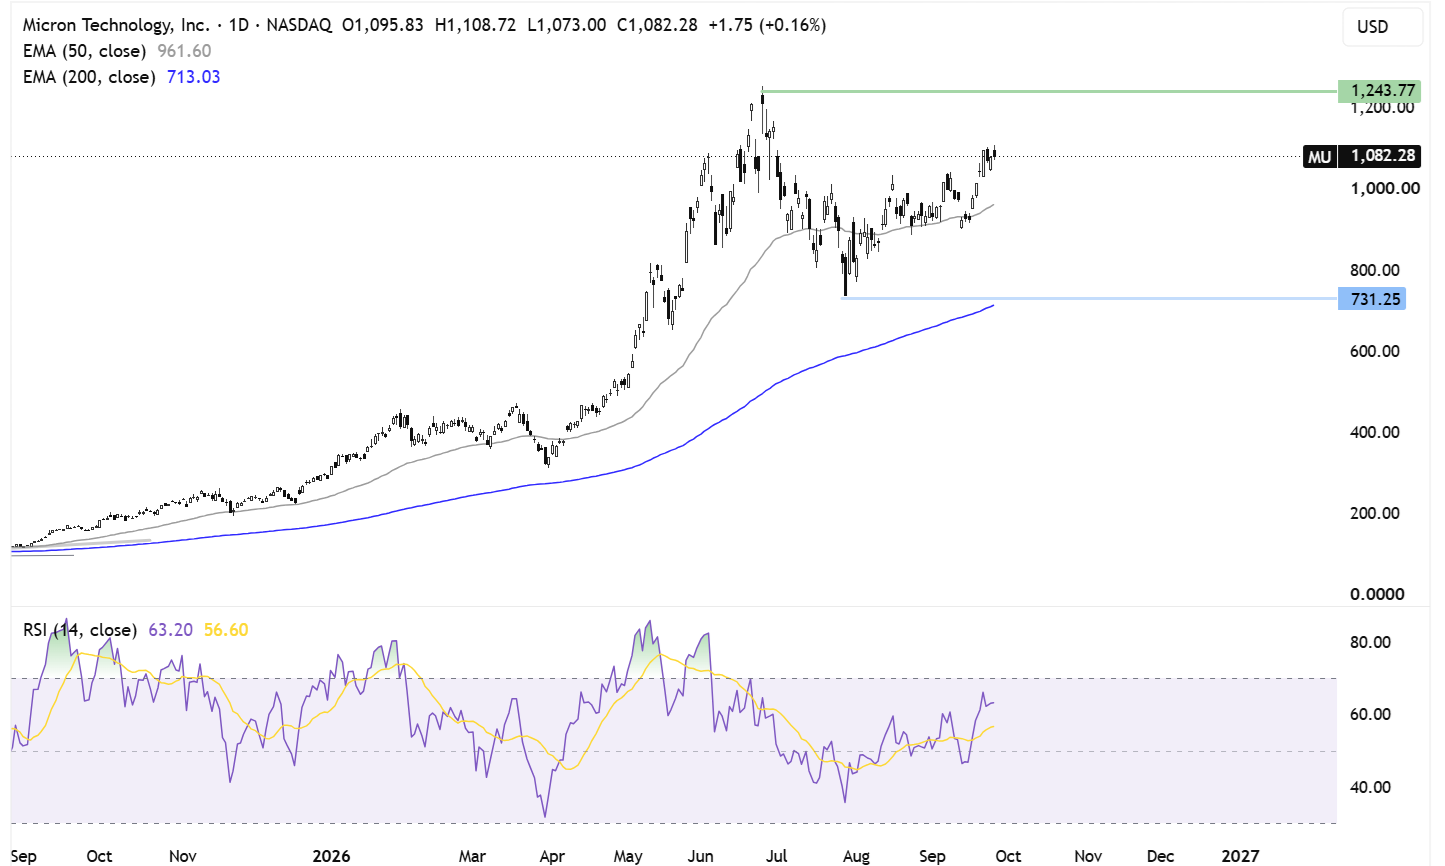
After reaching a record high of 1,255 in June this year, the price slumped to a low of 737. From here, there has been a steady recovery, with the price retaking the 50 EMA and rising to 1,080, where it trades now.
Supported by momentum, buyers will look to extend gains back towards 1,240, the record high.
On the downside, immediate support is the 50 EMA at 960, ahead of 905, the September low. A break below here turns attention back towards 730, the July low and the 200 EMA.
Carnival Q3 earnings preview
Carnival, the largest cruise company in the world by passenger capacity and fleet size, will announce third-quarter results on September 29.
Expectations are for EPS of $1.36, marking a 4.9% decline compared with the same quarter a year earlier.
Earnings come at a time when the operation's execution is being overwhelmed by variables beyond Carnival's control. The Middle East conflict has not only disrupted Mediterranean itineraries, but it has also lifted oil prices.
Oil prices have risen significantly since March due to the ongoing conflict in the Middle East. Analysts at Jefferies expect fuel prices per tonne to rise 1%, 8%, 8%, 7% and 2% from the third quarter of 2026 through to the third quarter of 2027.
Even when the war eventually ends, global reserves will need to be refilled, likely keeping crude prices elevated.
Expectations are also for lower revenue per passenger in Q3 and Q4 of 2026 and fiscal 2027, as analysis shows Carnival's advertised fares trailing for several months.
Slower pricing could be partly offset by higher occupancy as consumers continue to respond favourably to Carnival's value proposition.
How to Trade CCL earnings?
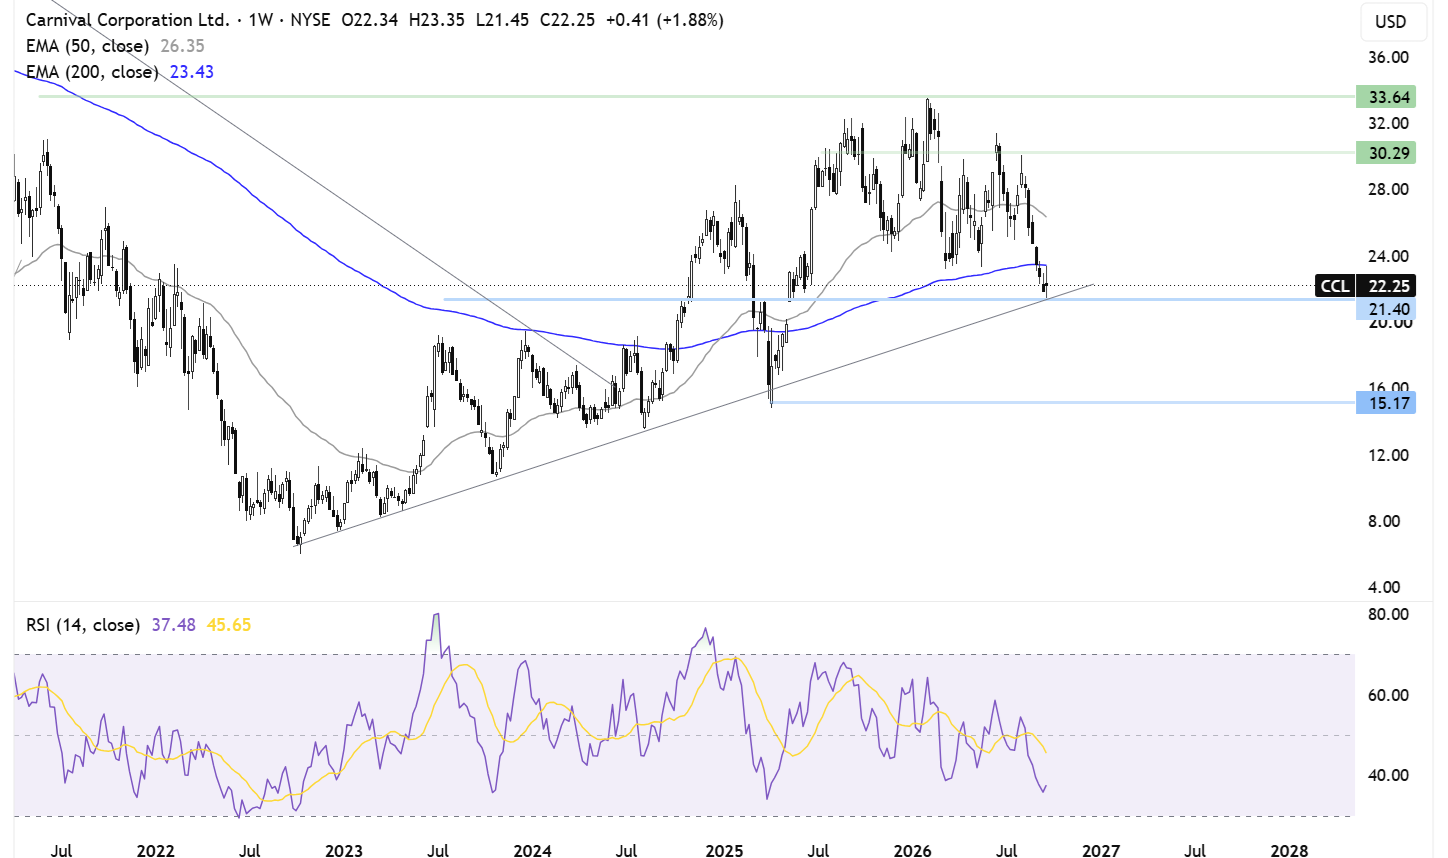
CCL trades above its rising trend line dating back to July 2022. After running into resistance at $33 in February of this year, the price has fallen lower, dropping below its 50 and 200 EMAs to test rising trendline support around the $21 level.
Sellers supported by momentum will look to break below this level in order to turn attention to $15, the April 25 low.
Any recovery would first need to retake the 23.52 EMA and the 50 EMA at $26.87. A rise above here turns attention back towards $33.20, the 2026 high.
Comments
Log in or sign up to join the conversation.