
Nominal retail sales upside surprise (+0.2% vs consensus +0.1% m/m), but actual real declines. Manufacturing production +0.3% vs. consensus +0.2% m/m (industrial production down primarily because of utilities).
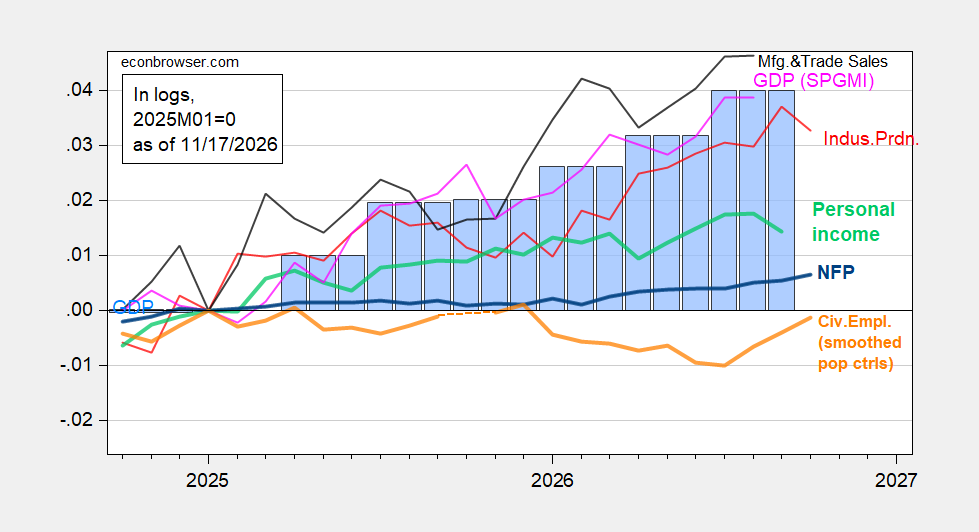
Figure 1: NFP employment (bold blue), civilian employment with smoothed population controls (bold orange), industrial production (red), personal income excluding current transfers in Ch.2017$ (bold light green), manufacturing and trade sales in Ch.2017$ (black), and monthly GDP in Ch.2017$ (pink), GDP (blue bars), all log normalized to 2025M01=0. Source: BLS via FRED, BLS, Federal Reserve, BEA 2026Q3 advance release, S&P Global Market Insights (nee Macroeconomic Advisers, IHS Markit) (10/2/2026 release), and author’s calculations.
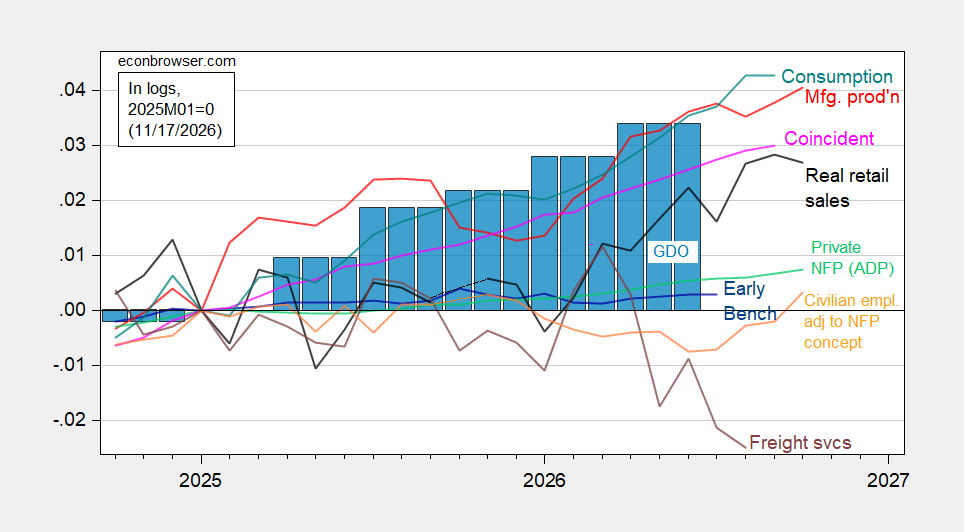
Figure 2: Civilian employment adjusted to NFP concept smoothed population controls, using experimental controls for 2025 (bold orange), manufacturing production (red), ADP private nonfarm payroll employment (light green), real retail sales, CPI deflated (black), freight services indexes (brown), and coincident index in Ch.2017$ (pink), GDO (blue bars), all log normalized to 2025M01=0. Source: BLS, ADP via FRED, Census, Philadelphia Fed, Philadelphia Fed, Bureau of Transportation Statistics, Federal Reserve via FRED, BEA 2026Q3 advance release, and author’s calculations.
Note that retail sales in previous month were revised up, so October inflation adjusted retail sales are still above what we thought a month ago they were in September. That said, both total retail sales and ex-gas station sales were down.
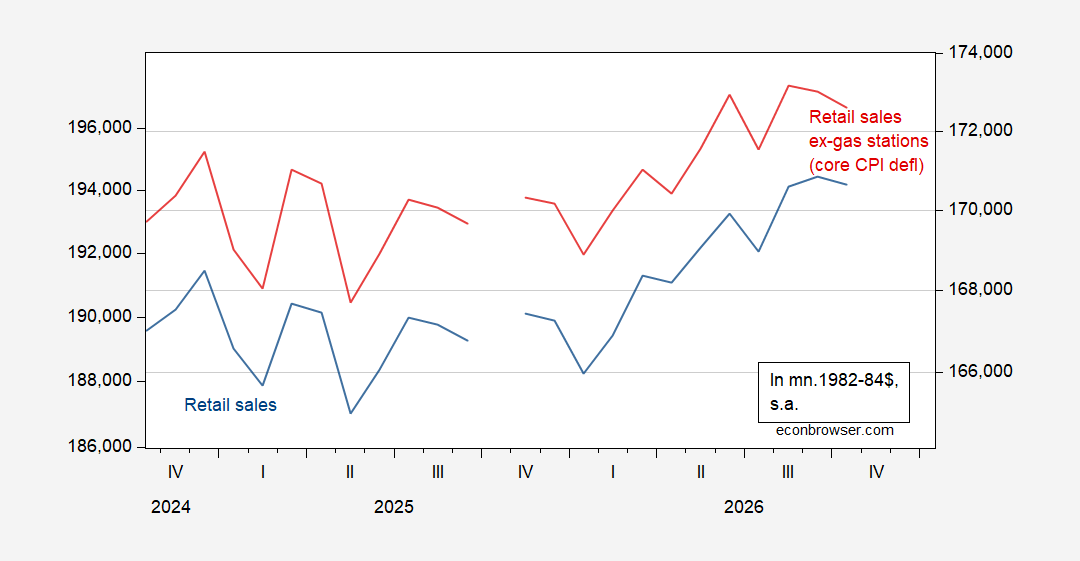
Figure 3: Retail sales, deflated by CPI (blue, left log scale), retail sales ex-gasoline station sales deflated by core CPI (red, right log scale), both in mn. 1982-84$. Source: Census, BLS, via FRED, and author’s calculations.
Comments
Log in or sign up to join the conversation.