
Uber Technologies (UBER) is showing unusually large options volume ahead of its earnings release on Nov. 4 (pre-market). Out-of-the-money (OTM) UBER puts expiring in three weeks and OTM calls expiring in more than a year have traded.
UBER is at $68.17 in midday trading. That's well off its recent peak of $80.35 on Aug. 25, but very near a recent low of $67.88 on Oct. 1. This is a typical drop ahead of earnings, as the Barchart chart below shows.
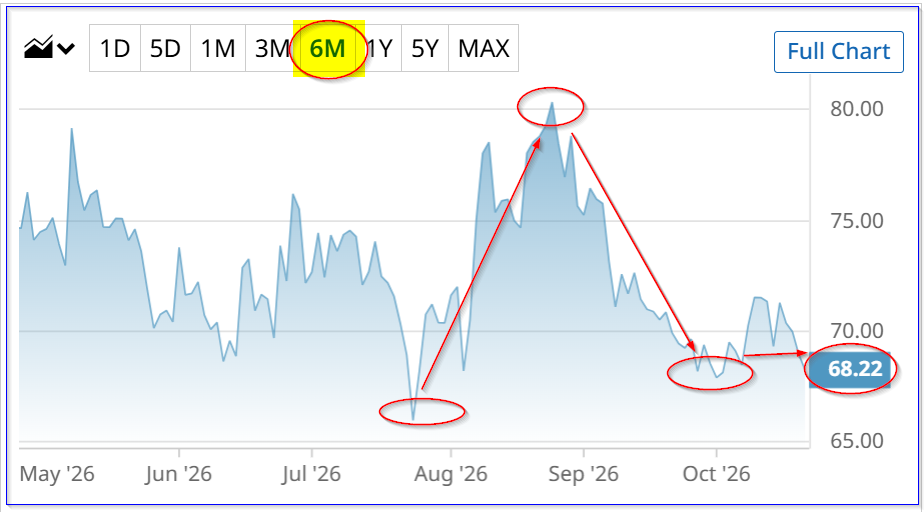
UBER stock - last 6 months - Barchart - Oct. 21, 2026
As a result, these unusual options trades may indicate that investors believe that UBER is near a low. They are taking advantage of high premiums by shorting them.
Unusual Options Trading Today
This can be seen in today's Barchart Unusual Stock Options Activity Report. It shows that 21,000 puts have traded at $58.00, $10 and 15% below today's price (i.e., “out-of-the-money”) for expiry on Nov. 13. This volume was almost 99 times the prior number of outstanding puts.
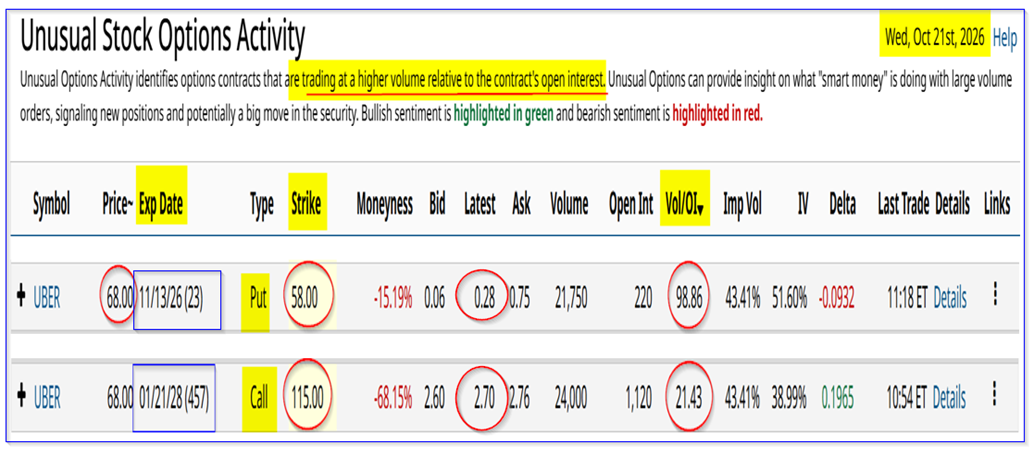
UBER puts expiring Nov. 13, 2026, and calls expiring Jan. 21, 2028 - Barchart Unusual Stock Options Activity Report - Oct. 21, 2026
In addition, the table above shows that 24,000 calls have traded at the $115 strike price, over 68% above today's price, but the expiry period is 1.25 years away (15 months) on Jan. 21, 2028.
This heavy out-of-the-money trading might indicate that short-sellers of these puts and calls initiated these trades. In addition, another play could be that an investor intends to short OTM puts each month to pay for an OTM purchase of these long-dated calls.
Either way, it looks like the investors in these puts and calls are essentially bullish on UBER. And why not? The fundamentals show that UBER could be undervalued. Here's why.
UBER Looks Undervalued
Analysts have significantly higher price targets (PTs) for UBER. For example, Yahoo! Finance's survey of 50 analysts shows an average PT of $100.86. That's 48% over today's price.
Similarly, Barchart's mean survey PT is $102.38, and AnaChart's survey of 34 analysts shows an average PT of $105.84. These are 52.7% above today's price on average.
And why not? The company is generating strong free cash flow (FCF) and high FCF margins. This can be seen on page 31 of its Q2 supplemental info deck (see below).
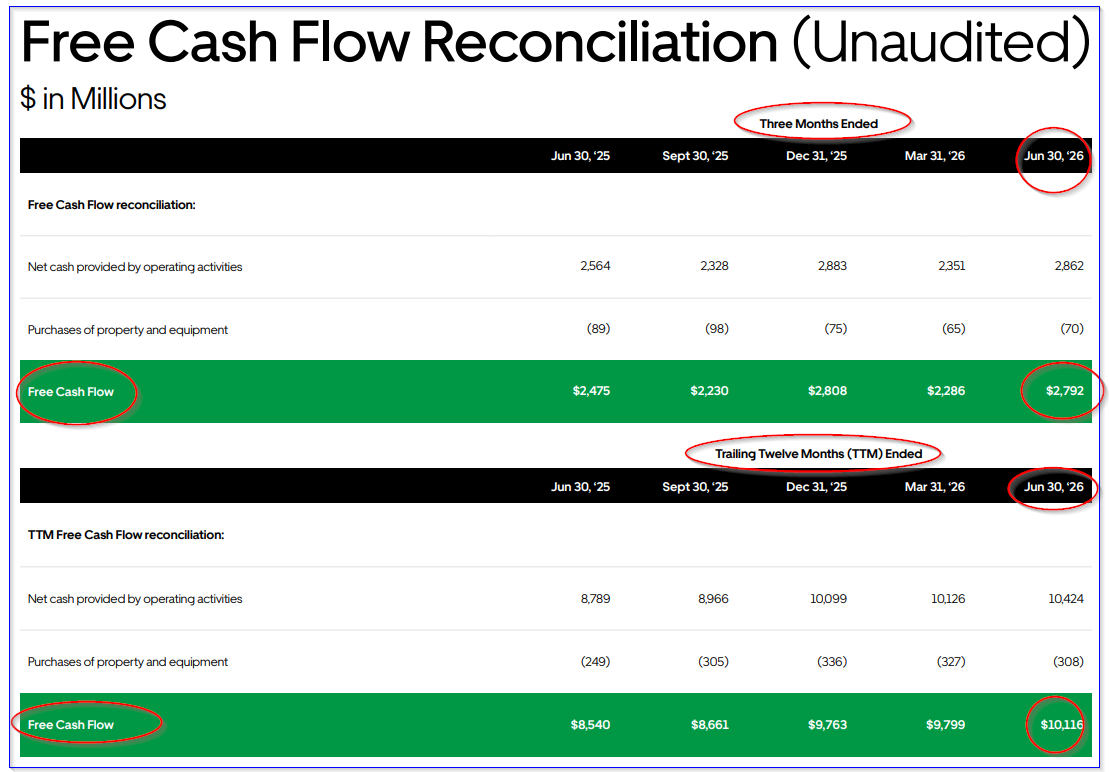
UBER FCF in Q2 and trailing 12 months (TTM) - Supplemental Info deck
FCF was $2.792 billion in Q2, and for the past year Uber generated 10.116 billion. Those represented 19.67% and 18.32% of revenue, respectively, according to Stock Analysis. In other words, the company is producing huge amounts of cash. That is likely to continue, as analysts have higher revenue forecasts.
For example, using analysts' forecast of $57.88 billion for this year and $66.79 billion next year, the next 12 months (NTM) revenue forecast is $62.335 billion. That implies FCF could rise to $11.42 billion, or 12.9% higher than its TTM $10.116 billion.
As a result, using a 6.66% FCF yield (i.e., a 15x multiple, since 1/0.0666 = 15), the fair market value (FMV) is $171.3 billion (15 x $11.42 billion NTM FCF). That is 23% higher than Uber's present market cap of $139.2 billion.
In other words, the PT based on FCF is 23% above today's price:
$68.17 x 1.23 = $83.85 PT
And next year, if forecasts of $66.79 billion come to pass, the FMV will be $183.54 billion ($12.236 billion x 18.32% x 15), or a price target of $89.88 (i.e., 1.3185x $68.17).
Summary and Conclusion
These higher valuations depend on Uber maintaining high FCF margins. Analysts and investors will be looking to see if Uber's FCF margins stay above 18.32% for the TTM period.
For example, if it matches the Q2 19.67% FCF margin or does better than the 16.56% Q3 2026 FCF margin, its TTM FCF margin will exceed 18.32%.
There are indications this will happen based on analysts' higher Q3 revenue forecasts. For example, they are predicting $14.67 billion in Q3 revenue, 8.97% higher than last year's $13.47 billion. That means if Uber maintains cost control, its FCF margins could rise. That could lead to higher FCF margins.
The bottom line is that UBER stock could rise sometime after its upcoming results, if its FCF margins stay strong. That may be what is behind today's unusual options volume.
Comments
Log in or sign up to join the conversation.