
The US Dollar turns slightly positive after recovering early losses ahead of the US CPI release.
Financial markets see the US headline CPI arriving higher at 3.6% YoY in September.
Almost every Fed member has warned of upside inflation risks since the September policy outcome.
The US Dollar (USD) claws back its early losses and ticks higher ahead of the United States (US) Consumer Price Index (CPI) data for September releasing at 12:30 GMT.
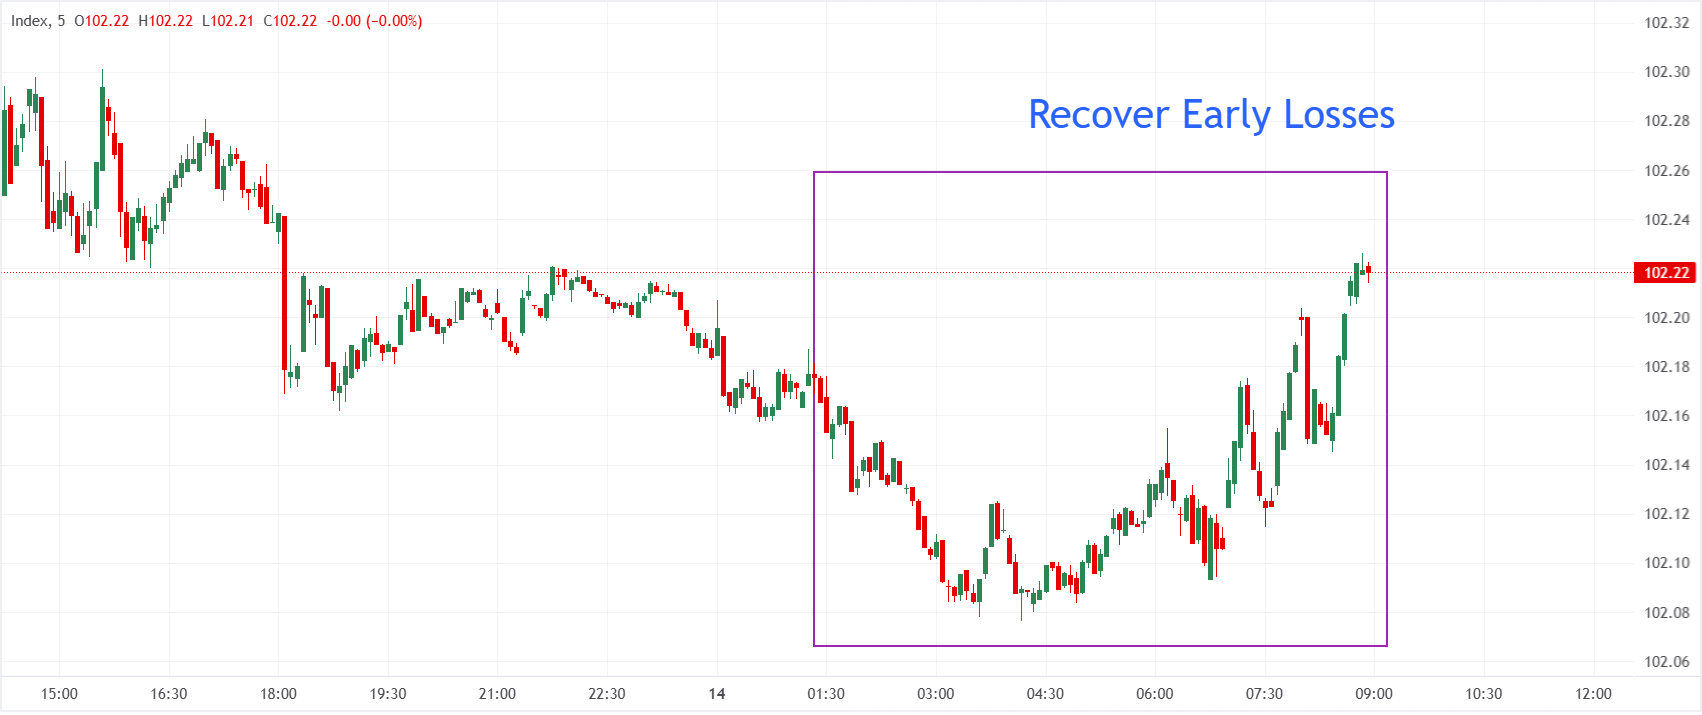
In the European trade, the US Dollar Index (DXY), which tracks the Greenback’s value against six major currencies, trades marginally higher to near 102.24.
US inflation preview highlights divergence between headline and core
Analysts at Rabobank preview the US September CPI release, noting that "headline CPI is expected to accelerate to 3.6% y/y and 0.6% m/m from 3.4% y/y and 0.4% m/m prior." In contrast, they expect underlying price pressures to ease, with "core CPI inflation expected at 2.5% y/y and 0.2% m/m from 2.45% y/y and 0.29% m/m," adding that "energy [is] likely to account for the divergence between headline and core expectations."
Investors will pay close attention to the US inflation data to get fresh cues regarding the Federal Reserve’s (Fed) interest rate outlook. Several policymakers have argued about persistent inflation risks and have indicated that both energy supply risks and Artificial Intelligence (AI)-driven demand are boosting price pressures.
Fed’s Collins keeps hawkish bias but flags data dependence into the new year
Fed’s Collins scores 7.1 on the FXS Speechtracker, modestly above the 6.7 historical average, underscoring a tone that remains firmly focused on inflation risks relative to the established baseline. The emphasis on an “elevated risk of high inflation” as the main focus, expectations for inflation to stay above 2% due to high energy prices, and explicit support for the September rate hike all reinforce a hawkish stance, even as comments on a broadly balanced job market and resilient growth introduce a measured, data-dependent nuance. References to a stable job market supporting consumer spending and data-center build out pressuring inflation readings further highlight concern that underlying price pressures could persist into the new year.
The FXS Fed Sentiment Index fell by 2.23 points to 131.63, signaling a modest pullback in perceived hawkishness despite the above-baseline speech score on the FXS Speechtracker. With the index still well above the neutral 100 mark, the Fed’s overall stance remains in hawkish territory, but the decline suggests markets see a slightly lower probability of additional aggressive tightening even as inflation risks stay front and center.
Regarding the likely impact of the US CPI data on Fed’s interest rate expectations, strategists as OCBC have said in a note “If core inflation moderates as expected, markets could further trim expectations for additional Fed tightening.” OCBC added, “It would likely take a core CPI print of 0.4% m/m or higher to materially shift market pricing and strengthen the case for earlier Fed action.”
US Dollar Index Technical Analysis
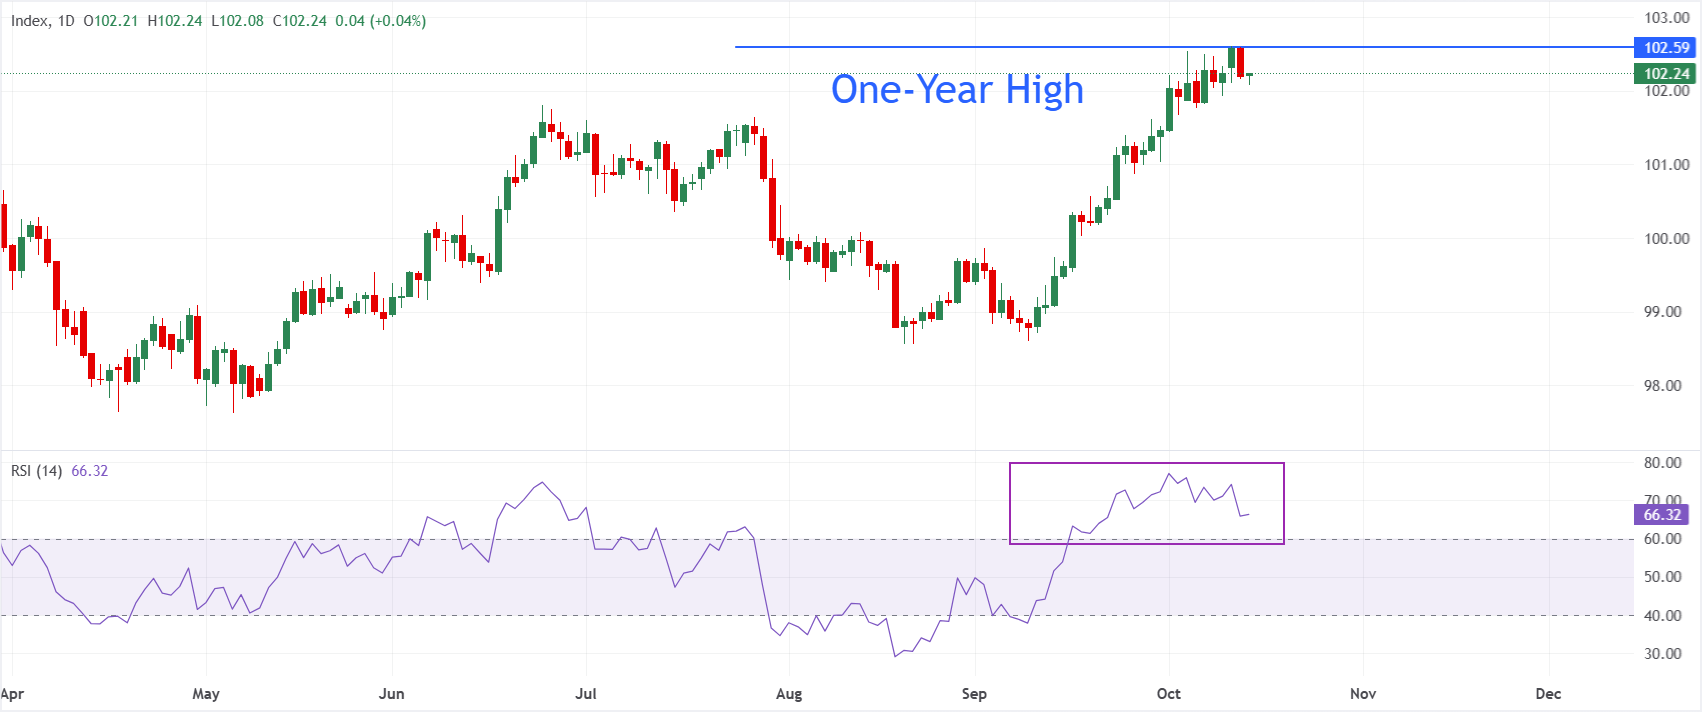
In the daily chart, Dollar Index Spot trades at 102.24, extending its advance after reclaiming the 102 handle, which keeps the near-term bias bullish. Price holds comfortably above prior consolidation levels near the upper 90s and low 100s, suggesting underlying demand remains in place, while the Relative Strength Index (14) at 66.32 hovers just below overbought territory and hints at strong but maturing upside momentum.
With no nearby moving averages or Fibonacci levels specified, the technical focus stays on price action and momentum, where the index is supported by its recent sequence of higher lows and steady grind higher. As long as the RSI holds elevated without a sharp reversal, dips are likely to attract buyers, though the proximity to overbought conditions cautions against chasing the move aggressively at current levels.
Comments
Log in or sign up to join the conversation.