
By Carlos Yudica
A Barchart report today shows unusually heavy call option volume in United Parcel Service (UPS) stock that expires in 3 months. It recently delivered strong Q3 earnings.
However, analysts' price targets aren't much higher than today's price. As a result, Investors may be shorting slightly out-of-the-money (OTM) UPS calls and call credit spreads.
UPS closed yesterday down slightly to $111.64, up from a recent low on Oct. 7 ($92.29), but down slightly from its Nov. 11 peak of $112.45. So, are these short-sellers exiting after seeing UPS at a peak?
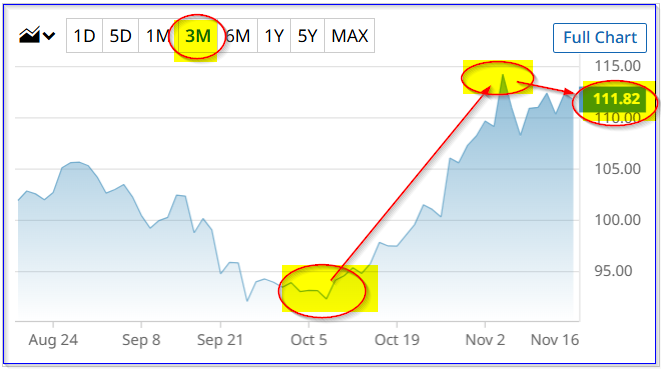
UPS - last 3 months - Barchart - Nov. 17, 2026
Unusual Call Option Activity in UPS
This activity is shown in today's Barchart Unusual Stock Options Activity Report. It shows that over 7,000 call options traded at the $120.00 strike price. That's just 7.3% higher than today, for expiry on Feb. 19, 2027.
That volume is more than 58 times the prior number of calls outstanding at the strike and expiration date. Moreover, the premium is high at $3.30 at the midpoint.
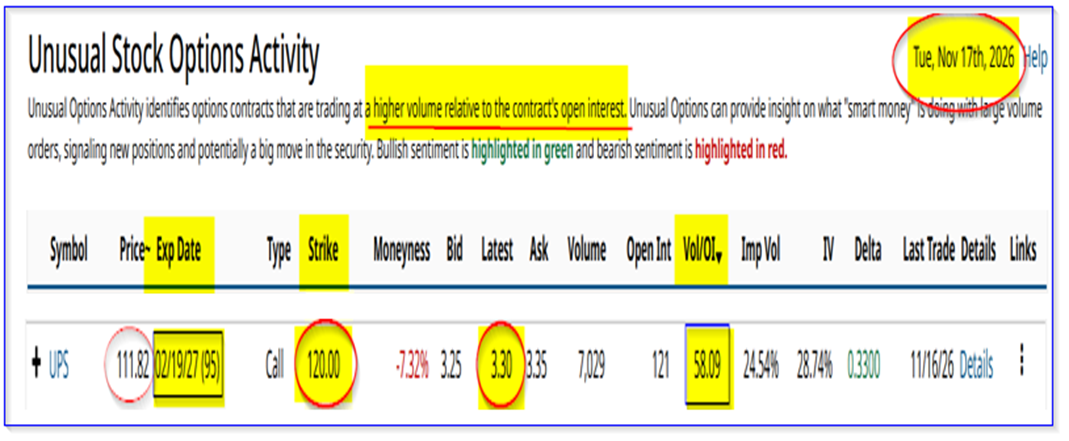
UPS calls expiring Feb. 19, 2027 - Barchart Unusual Stock Options Activity Report - Nov. 17, 2026
This means that existing shareholders selling covered calls can make an attractive almost 3.0% yield over 3 months (i.e., $3.30/$111.82 = 2.95%).
And it may not just be existing shareholders selling these calls. Investors may be investing in a call credit spread (i.e., selling $120 calls and buying higher strike calls). They are betting UPS may have reached a 3-month peak.
The latter play could be risky if UPS stock keeps rising above $120 for the next 3 months. For example, a large portion of the volume could be from investors buying these calls, believing UPS is undervalued.
What UPS Stock May Be Worth
United Parcel Service reported on Oct. 27 that its Q3 (ending Sept. 30) revenue rose +6.71 YoY, and up +2.1% for the trailing 12 months.
Moreover, the company raised its revenue outlook to $92.6 billion and its non-GAAP earnings per share (EPS) forecast to $7.28.
In addition, UPS forecasted that its free cash flow (FCF) will hit $6.1 billion this year. That's up from $4.765 billion last year.
As UPS's year-to-date FCF is $4.22 billion (up 53.7% from last year's $2.77 billion), this implies Q4 FCF will be $1.88 billion, or 7.3% of forecast revenue of $25.71 billion. That's lower than the 10.53% Q3 FCF margin, but higher than its LTM FCF margin of 6.95%.
In other words, UPS's run rate FCF margin will be at least 7.0% and possibly higher. For example, next year, analysts are forecasting 3.3% higher revenue at $95.64 billion:
$95.64b x 0.07 = $6.695 billion FCF (2027)
That is almost 10% higher than the $6.1 billion projected by management for 2026 (i.e., +9.75%). However, that's just 5.4% above the $6.351 billion over the last 12 months (LTM), as seen in Stock Analysts data. That might imply just a 5% higher valuation.
For example, over the last year, UPS stock has been valued at roughly a 7.0% FCF yield. So, applying this to our $6.7b 2027 forecast:
$6.7b FCF / 0.07 = $97.71 billion valuation
That is actually only slightly over (+0.53%) its market cap today of $95.21 billion, according to Yahoo! Finance.
In other words, the market has already discounted an increase in its FCF over the next year. The price target is 1.0053 x $111.64, or $112.20. Yahoo! Finance has a similarly low price target of $115.46, Barchart's is $117.11, and AnaChart's is $116.76.
Summary and Conclusion
The bottom line is that UPS is not worth more than $120 for the next year. That's, even after factoring in an increase in its FCF margin and higher revenue forecasts.
That could be why there is heavy call option activity today at the $120 strike price for expiry in the next 3 months. It appears some investors are initiating call option short sales or call credit spreads at the $120 strike price for expiry on Feb. 19, 2027.
Comments
Log in or sign up to join the conversation.