
Global ex-US Equities
I wanted to share this topic from a recent Weekly Macro Themes report because it answers a few key questions, raises a couple more, and helps put into context today’s Fed rate hike decision.
Firstly, on that note, in case you missed it, the US Federal Reserve just hiked rates +25bps to 4% — as I noted last week, this is exactly what they should be doing, and we probably will see more hikes (my indicators say another ~100bps are required).
Now back to the issue at hand…
First up is the Main Page for this topic —all topics in my weekly report take this format: an overall assessment (summing up the outlook), risks against the view, catalysts to reinforce the view, a key chart to provide big picture visibility on what is happening, and ratings for each of the core factors I look at (table at the bottom).
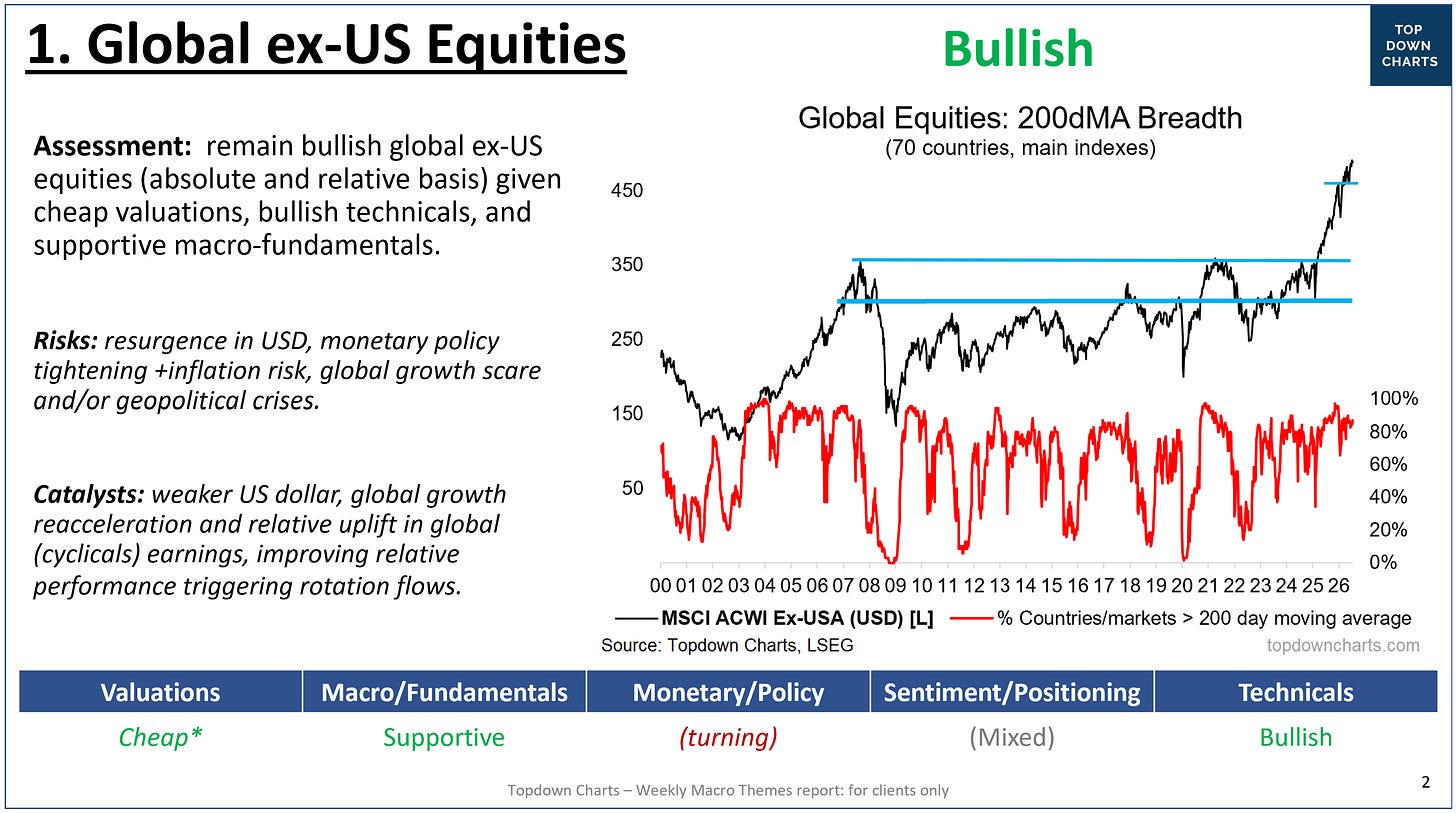
As you can see the overall assessment is bullish (this assessment is primarily for global ex-US [rest of world] equities in absolute terms, but the relative case is also decent). Let’s now go through the key charts behind this…
Policy and Valuations: for global ex-US equities, the technicals still look bullish (uptrend, strong breadth). However while policy settings are still in tailwind territory, they are turning and this will be a problem sooner or later (especially if we see higher inflation, more rate hikes, and growth wobbles in 2027). Valuations likewise are still reasonable, and very cheap vs USA – but have already moved up a lot.
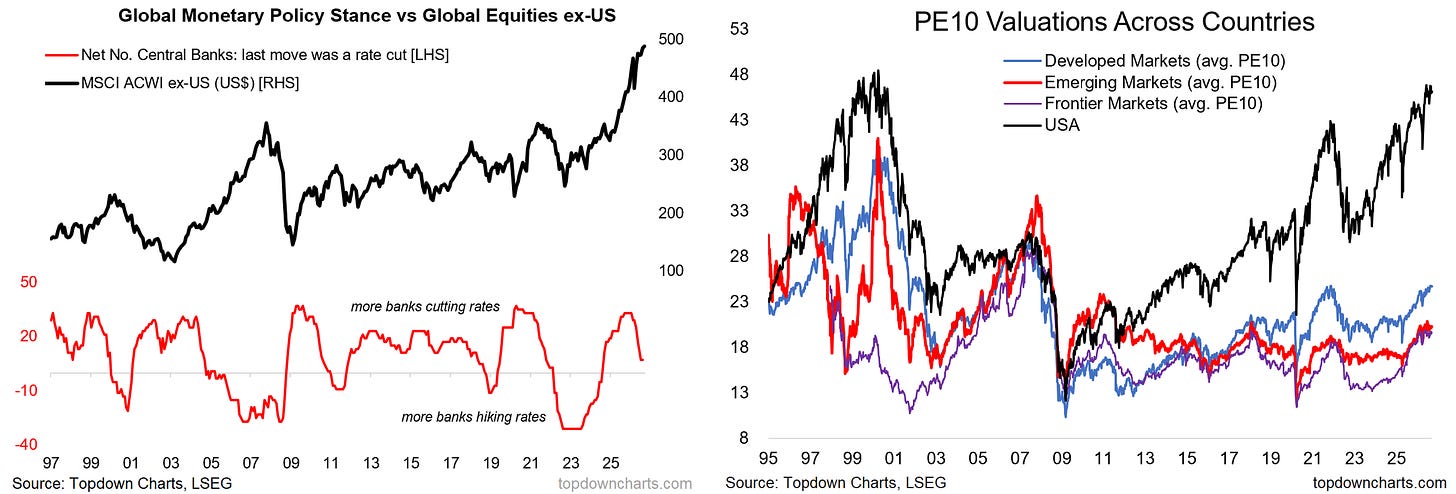
So the bull case has diminished significantly vs back in 2024/25 (when valuations were cheaper and policy was pivoting towards cuts vs pivoting towards hikes now). Still bullish, but less-so now.
[the latest Fed rate hike only adds to the global policy pivot to rate hikes, and reinforces this assessment —notably, the US is coming from a much higher valuation starting point, so the risks for US equities are arguable higher (as outlined last week)]
Relative Performance picture: as for relative performance, global continues the work in progress in turning the corner vs US after about 15-years of one-way traffic on this front (it takes time to turn). EM has been doing most of the heavy lifting so far, but DM is putting up a decent fight.
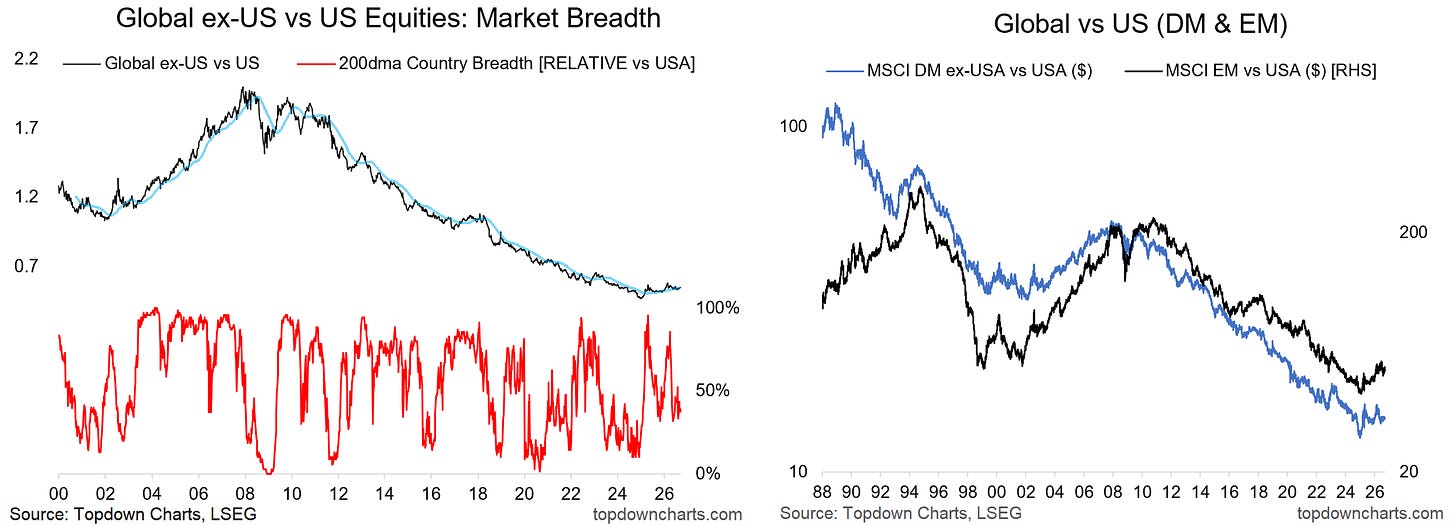
Relative breadth has been volatile, but notably is in a higher range (higher lows). Tentative turning point ticking away.
Relative Performance drivers: the value and technicals side of things support global vs US, but the macro/fundamental catalysts for a sustainable turn in global vs US equities’ relative performance has likewise been a bit stop-start. Namely, relative earnings performance is still favoring US (trending up), and the US dollar is holding support for now (after a brief bear run off the peak).
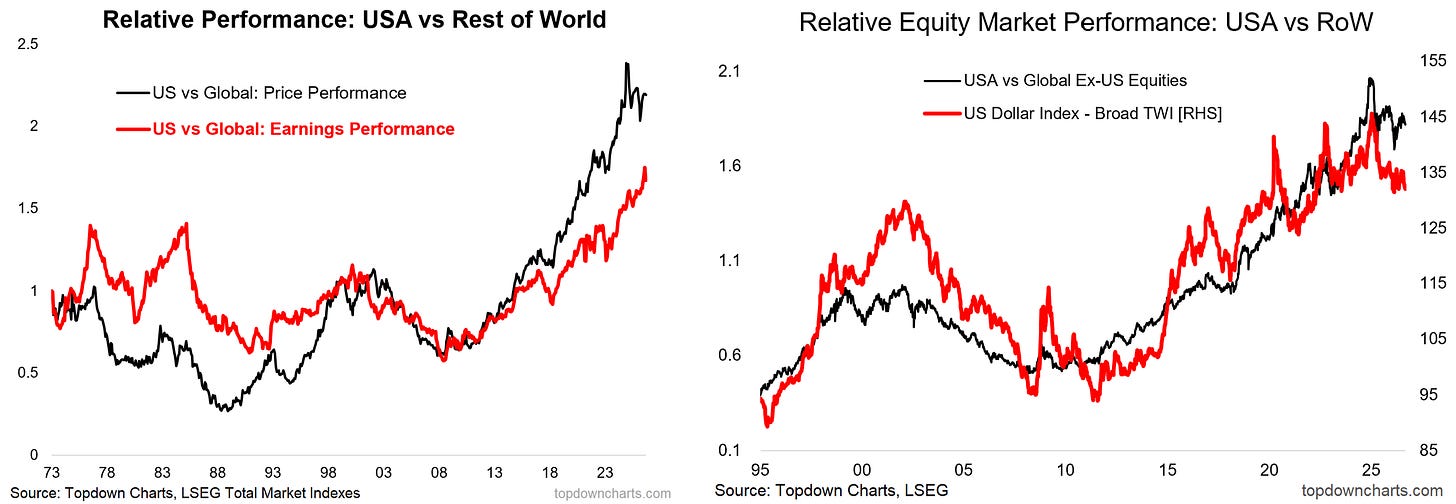
Basically, you want to see a sustained period of US dollar weakness (downtrend in USD), and global earnings outgrowing US (ideally as a result of global strength). We need to see more progress here to raise conviction on global vs US.
Earnings: staying with the earnings picture, at the global ex-US level we are seeing global starting to play catch-up and break out of its stagnation on the earnings front.
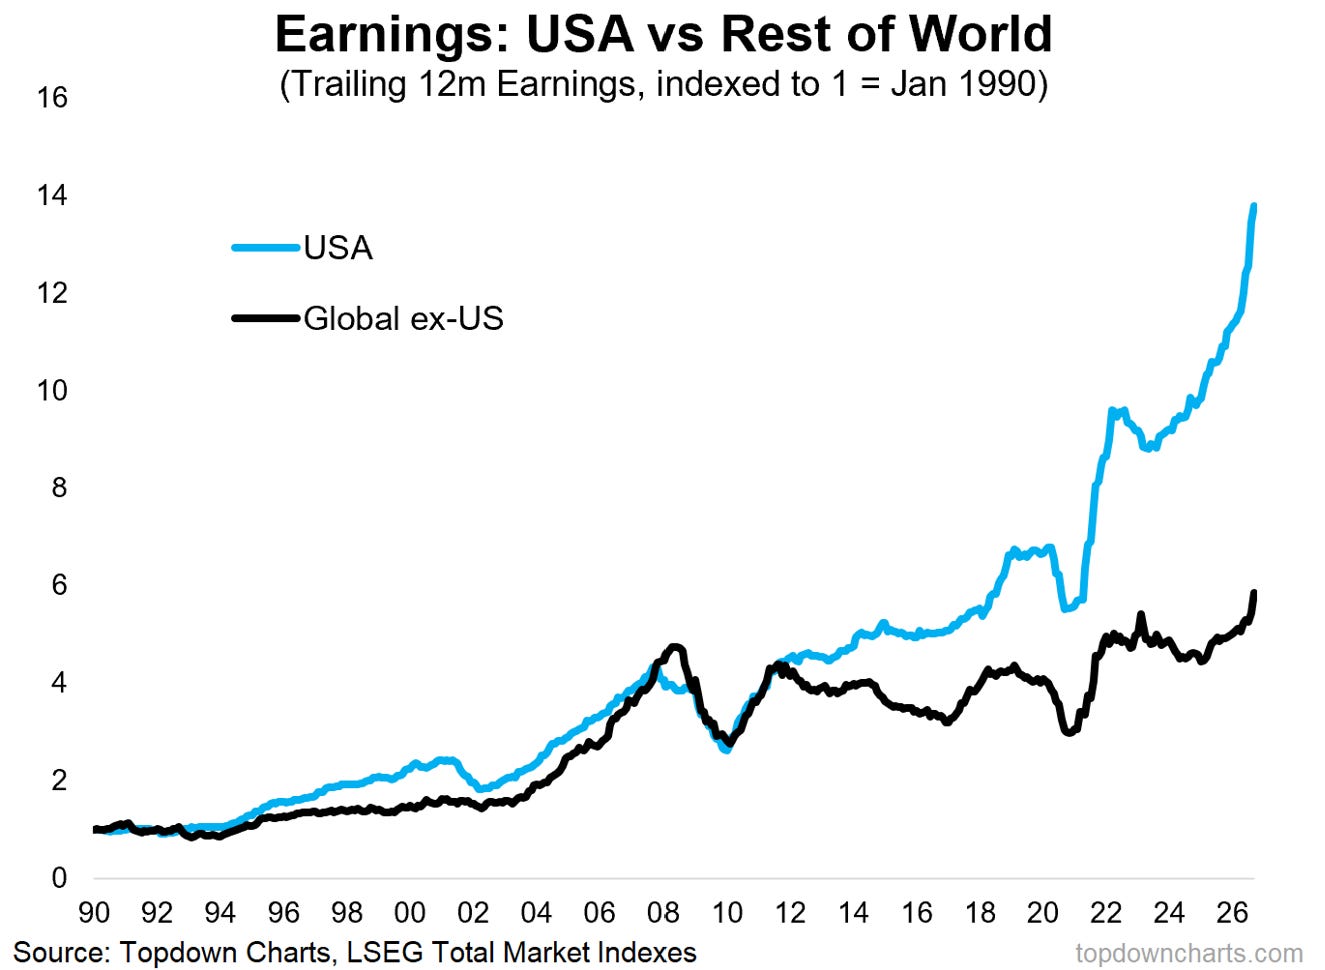
Notably all three major chunks of global equities are seeing upgraded long-term earnings growth expectations and a solid pace of improvement in forward EPS.
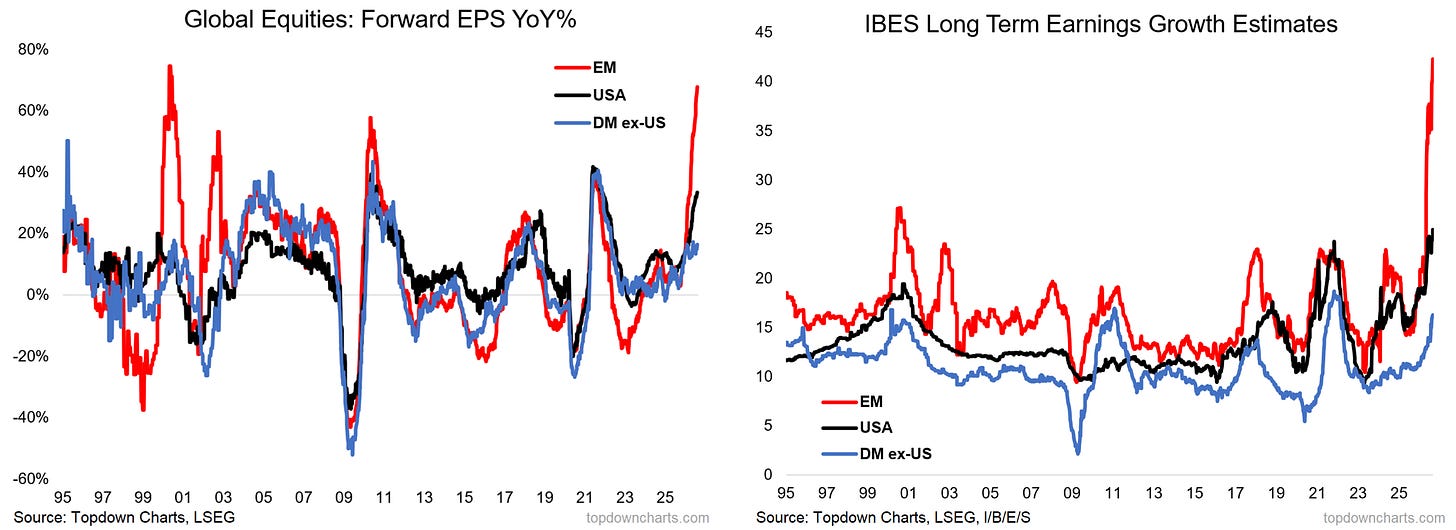
EM (Korea/Taiwan) is a key driver, but developed ex-US are also seeing earnings growth accelerate. This is a key support to the absolute and relative bull case for global ex-US equities.
Overall Conclusion…
As you can see there is a body of evidence pointing to a bullish outlook for global ex-US equities, but with valuations having already re-rated significantly and monetary policy pivoting to rate hikes globally, the risks are starting to shift (less favorable than the past couple of years).
On a relative basis it is still a work in progress, but improved earnings for global ex-US, tentative improvement in relative price performance, and still significantly cheap relative valuations it is worth keeping tabs on the key drivers/catalysts to gain conviction on the relative outlook for global vs US stocks.
Comments
Log in or sign up to join the conversation.