

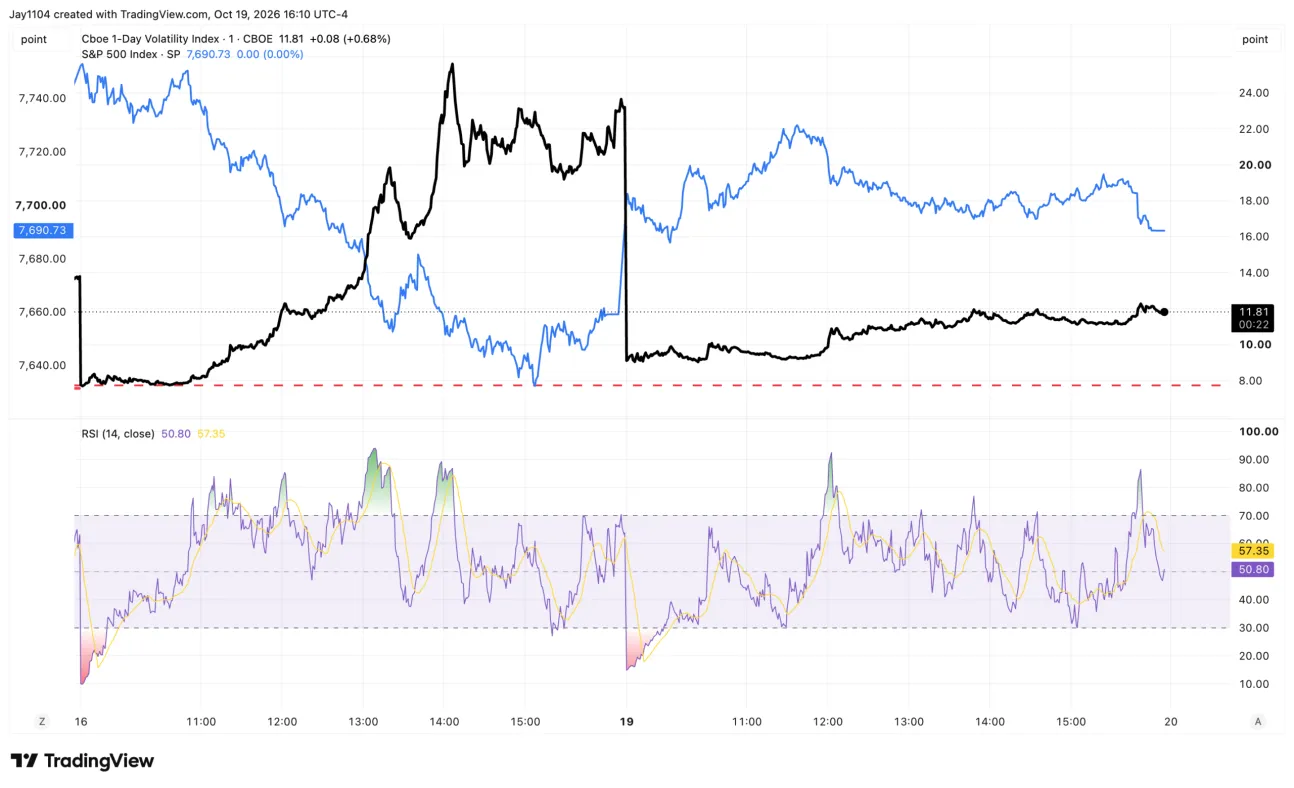
Stocks finished higher today, with the S&P 500 up 46 bps, which I thought was kind of weak given how much the VIX 1-day fell. The VIX 1-day closed near 24 on Friday, opened today around 9, and finished at 12. Given that drop, I’m surprised the S&P 500 moved by only 46 bps.
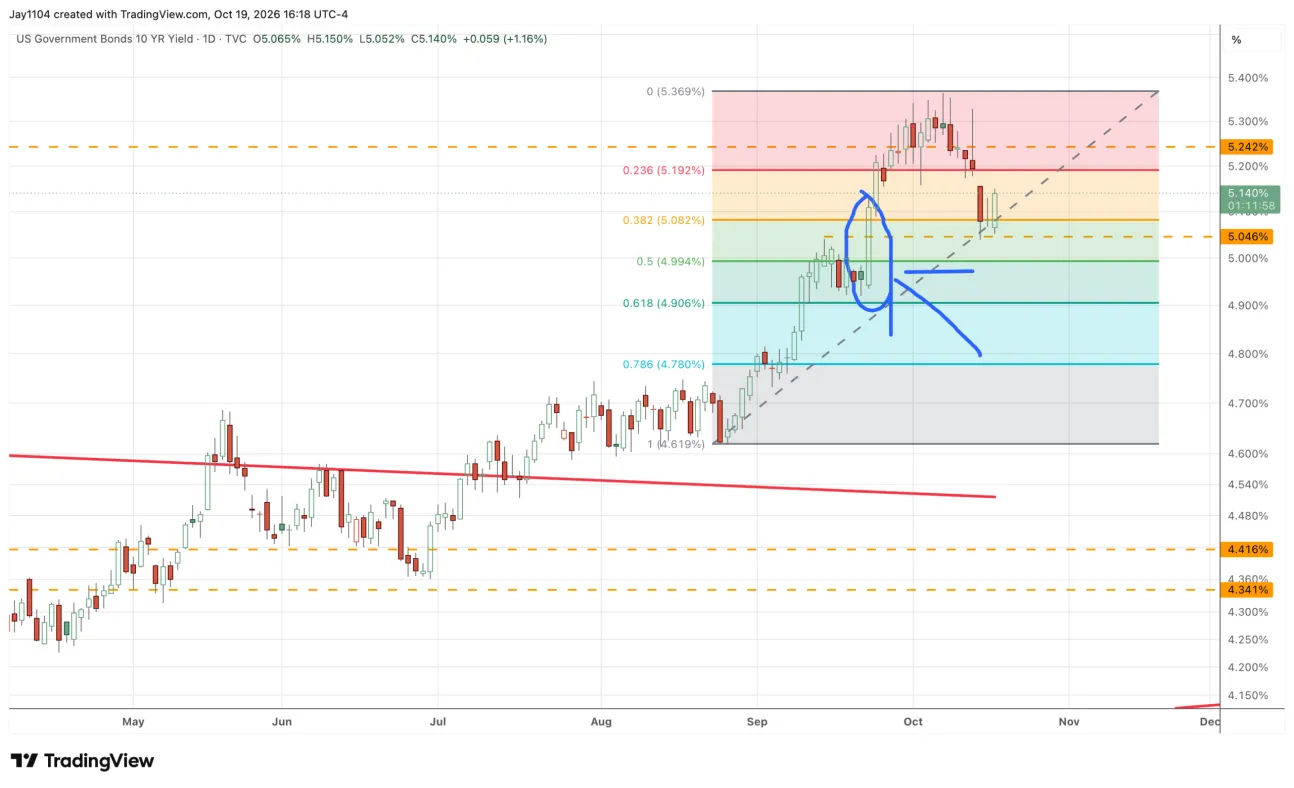
The 10-year rate rose nearly 6 bps today and rebounded off the 38.2% retracement level noted over the weekend. The big day to watch is Friday, when the S&P Global PMI Flash reading is released. This was the same report that sent rates higher back in September.
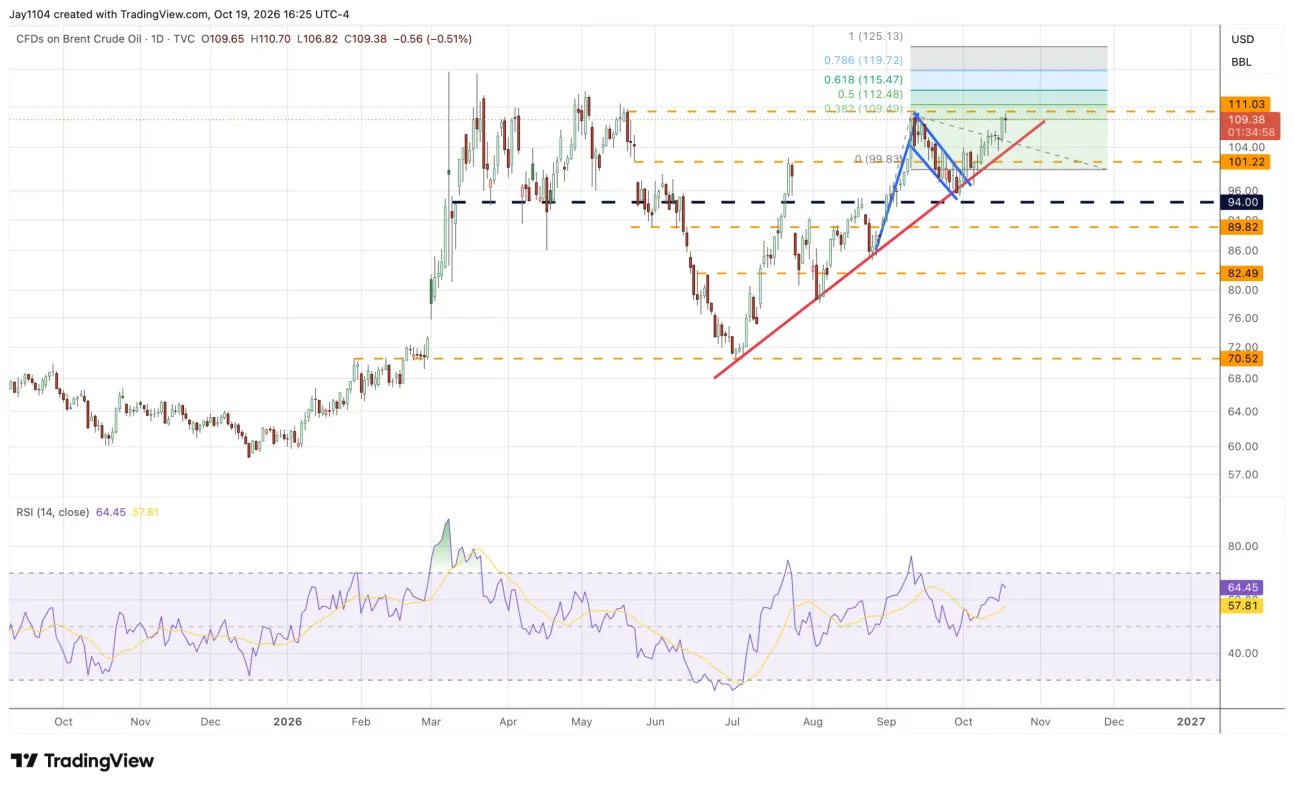
Brent oil is sitting at resistance at $111 and has been grinding higher. This is Brent’s second attempt at the $111 price point. If Brent breaks out, it is likely to head significantly higher, probably well beyond the $115 area, and maybe well over $120. If we treat the recent rises as part of a bull flag, it suggests a move toward around $125.
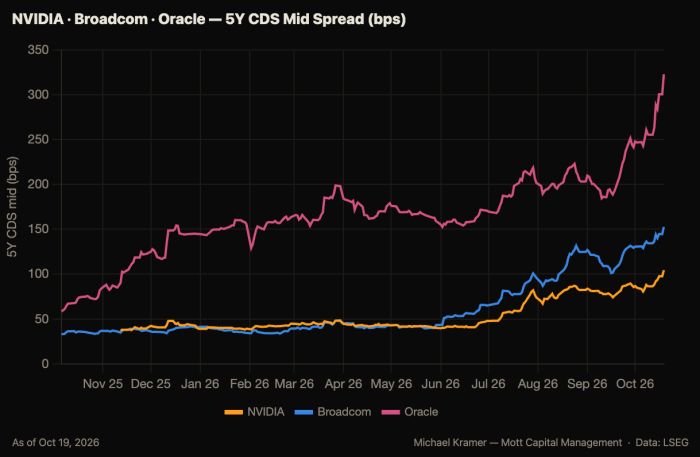
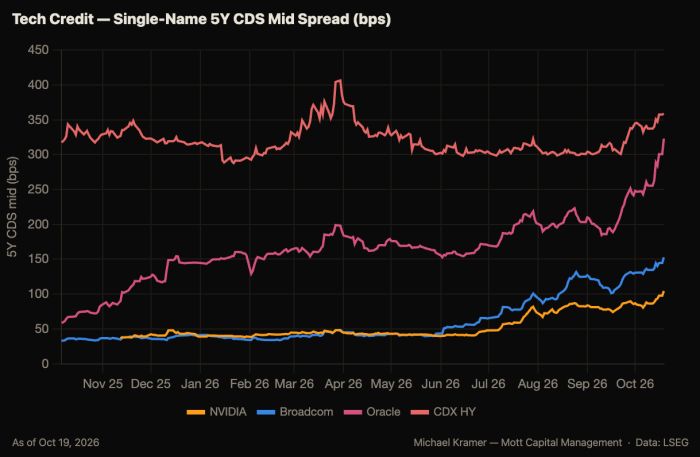
Credit Default Swaps for Oracle (ORCL), Broadcom (AVGO), and Nvidia (NVDA) continue to widen out, with Oracle at a 23% default probability, Nvidia at about 8%, and Broadcom at 12%. Which is pretty amazing, given these are among the largest companies in the world.
It’s taken a while, but we are finally starting to see the CDX High Yield index move up and keep pace with the CDS of some investment-grade names that already moved higher. It is something to watch, because I expect equity implied volatility to rise as CDS widen further, and the S&P 500 PE multiple to contract.
Comments
Log in or sign up to join the conversation.