

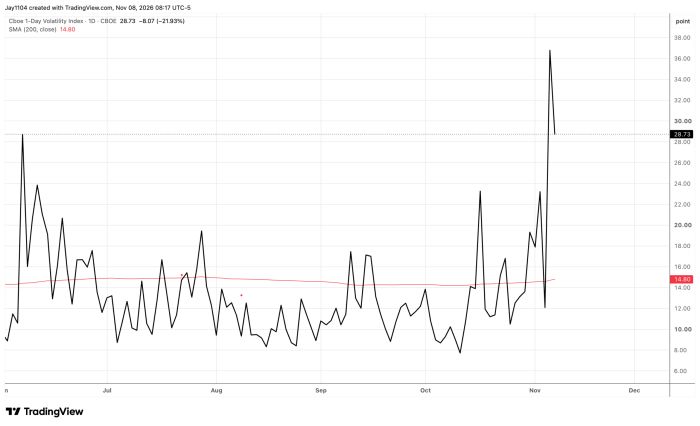
Stocks didn’t rebound much on Friday despite being set up to. They should be set up to rebound again on Monday, with the 1-day VIX closing Friday at nearly 29. If there’s no bounce on Monday either, that would be the second day in a row of failing to rally from a setup built for one, and that isn’t a good sign.
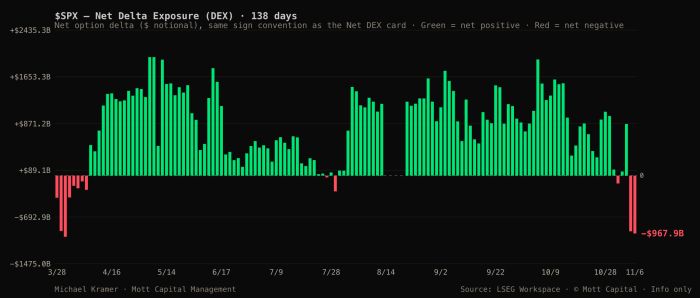
The S&P 500 is in negative gamma at this point, with the put wall at 7,300, and even net delta is now estimated to be negative. The last time we saw that was at the end of March. So the index is back in a regime where selling begets more selling and buying begets more buying. With volatility this high and a sharp drop in that 1-day vol likely Monday morning, a failure to rally would be a big negative for this market.
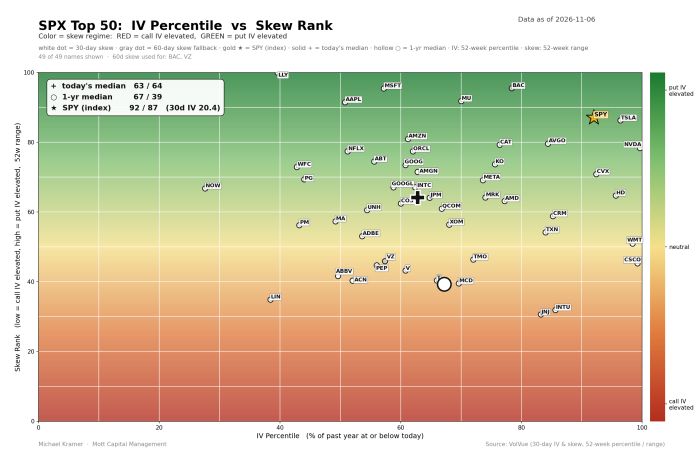
It’s also important to remember that the options market is more bearish today than at any time I can remember since the spring. The heatmap of the top 50 names in the index shows how much has shifted in just a few weeks, with more stocks showing elevated put skew and higher implied volatility.
If this environment persists, the market would likely keep heading lower. That’s the part we still don’t know, and it will take more time to find out. Certainly, the liquidity backdrop isn’t supportive right now, with a very heavy stretch of T-bill issuance and more than $57 billion in net issuance expected. That will likely keep draining market liquidity.
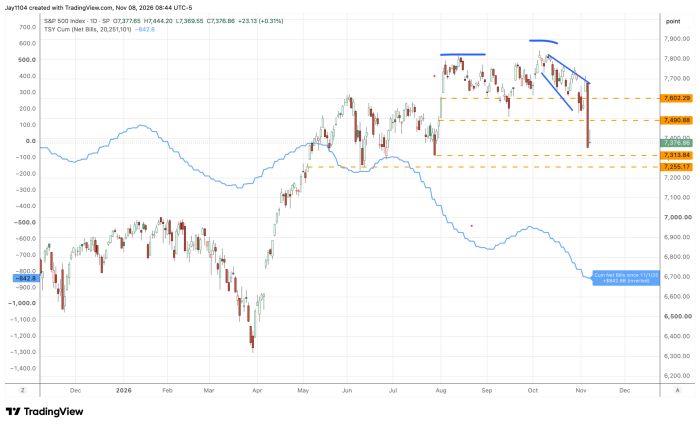
The CPI report, of course, is the wild card. A hotter-than-expected reading could push Fed policy in a more hawkish direction, which would tighten financial conditions further. Financial conditions have already tightened, and that tightening is starting to weigh. The Fed’s efforts to tighten conditions appear to be showing up, and if that continues, it will be the ultimate driver of markets, just as it was in 2022.
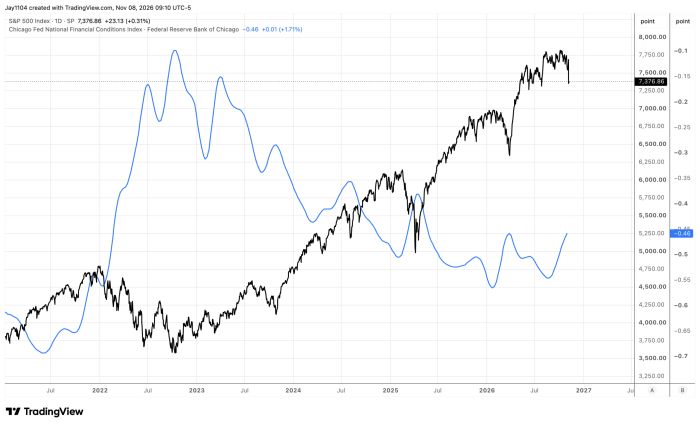
Tightening liquidity, coupled with tightening financial conditions, may be something not even the AI trade can overcome.
Comments
Log in or sign up to join the conversation.