
Global equity markets opened the week with a defensive bias as institutional desks pared risk ahead of a defining week for artificial intelligence valuations, central bank rate paths, and high-stakes geopolitical summits. Following a cautious Friday close on Wall Street—where the S&P 500 dipped 0.4% to 7,562—US equity futures retreated into the European open, led by a ~0.9% drop in Nasdaq 100 contracts. Asia-Pacific bourses absorbed the heaviest liquidation, with South Korea’s Kospi plunging ~3.0% (dragged down by 6% losses in SK Hynix and 4% in Samsung) and Taiwan’s Taiex sliding over 4% intraday on TSMC pressure. Japan’s Nikkei 225 shed nearly 2.0% after Q3 GDP unexpectedly contracted, while China’s October industrial production (+4.8% vs. +5.3% consensus) and soft retail sales underscored persistent domestic consumption fragility.
The AI ecosystem faces a twin public-and-private stress test this week. Tomorrow’s Nvidia (NVDA) earnings print takes on monumental significance following CEO Jensen Huang’s abrupt resignation; interim CEO Colette Kress must deliver airtight forward guidance, roadmap continuity, and customer assurances to stem multiple compression across the semiconductor supply chain. Later in the week, Anthropic’s landmark IPO will serve as the ultimate barometer for private-market appetite toward frontier AI models amid higher hurdle rates and looming US export-control scrutiny.
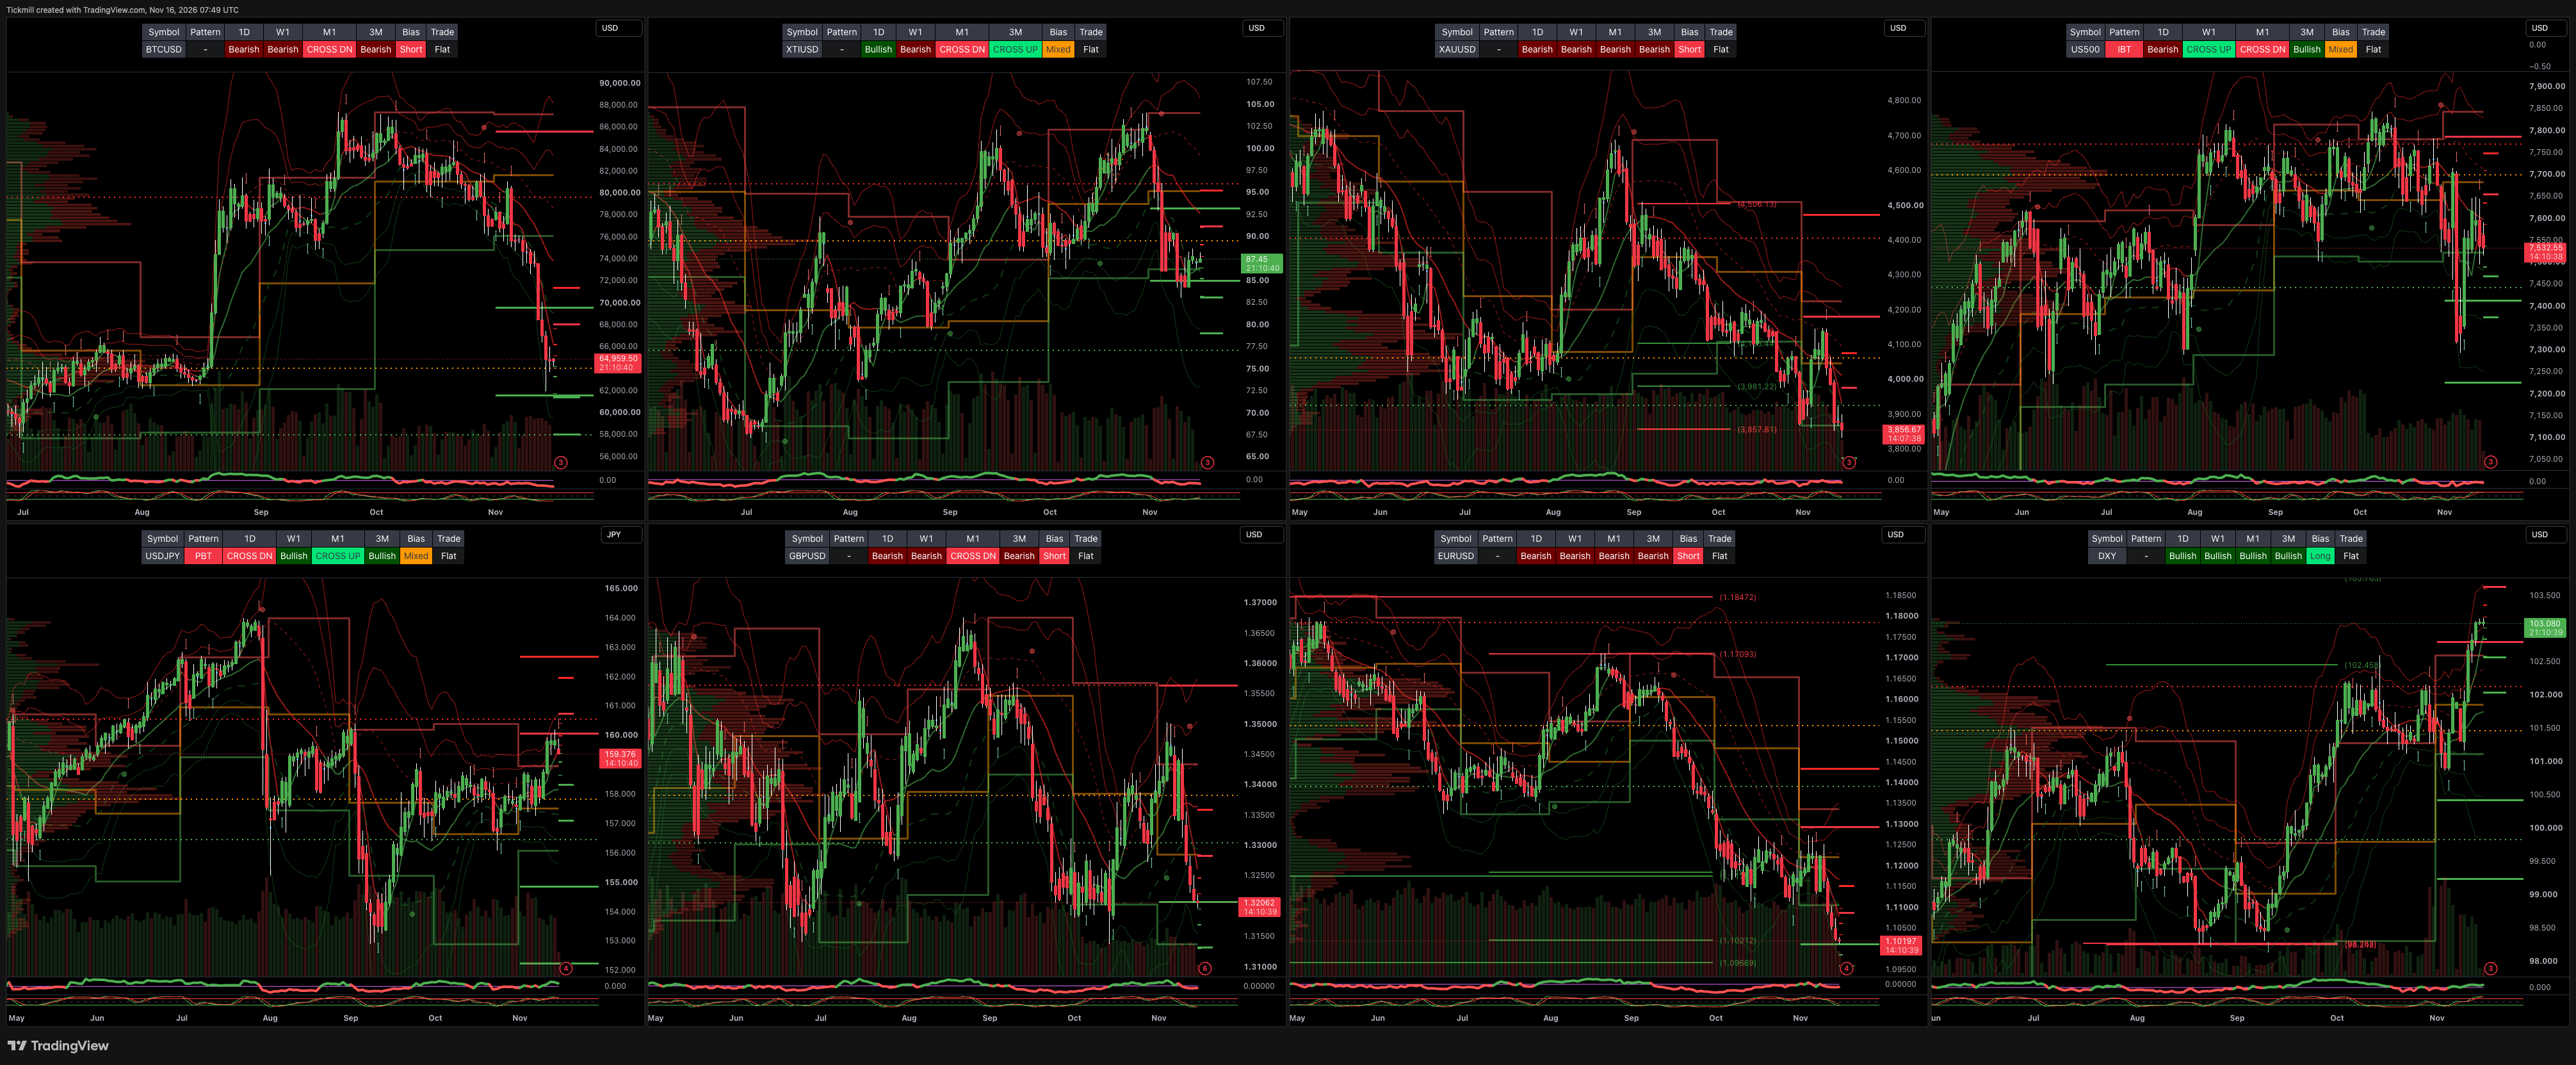
Fixed income and currency markets continue to price an unyielding Federal Reserve. Friday’s October PPI offered only marginal relief: while headline final demand printed slightly softer at 0.3% m/m, core ex-trade services ran hot at 0.5% m/m, accompanied by surging food prices (+1.4%) and deteriorating intermediate pipeline pressures. With core inflation proving sticky, swap markets continue to price a 25 bps Fed hike in December alongside strong odds for another move in January, keeping the benchmark US 10-year Treasury yield pinned near 5.15%. Higher US yields propelled USD/JPY through the intervention-sensitive 159–160 zone, while high-beta speculative assets buckled under real-rate pressure, driving Bitcoin (BTC.X) below $70,000 for the first time since August.
Energy markets stabilised below recent highs, with Brent crude trading under $96/bbl on global oversupply signals, though President Trump’s warning that the US "doesn't need a deal with Iran" keeps a geopolitical risk floor intact. Meanwhile, geopolitical tail risks escalate into Thursday’s scheduled summits between President Trump, Chinese President Xi Jinping, and Russian President Vladimir Putin—events carrying direct implications for semiconductor export controls, tariffs, and global energy security.
Across the Atlantic, the UK faces a pivotal macroeconomic slate featuring Tuesday’s labour report and Wednesday’s October CPI, measured directly against the Bank of England’s 3.7% y/y forecast. An upside inflation surprise alongside Governor Andrew Bailey’s Wednesday remarks would rapidly shift market pricing from a February hike toward an immediate December move. In the Eurozone, final October CPI prints and Friday commentary from ECB President Christine Lagarde are expected to cement a 25 bps December rate hike followed by an extended pause, even as French fiscal spreads remain a latent risk marker.
Macro to Micro: Financial markets are shifting from broad risk appetite to acute event-risk hedging as AI leadership transitions collide with sticky producer-price pipelines. With 10-year Treasuries anchored near 5.15% and Bitcoin breaking below $70,000, liquidity conditions are tightening across long-duration assets. For traders, the immediate tactical focus centres on Nvidia’s post-Huang guidance, Anthropic’s IPO pricing, Wednesday’s FOMC minutes, UK CPI surprise risk, USD/JPY intervention defences near 160, and Thursday’s Trump-Xi-Putin diplomatic headlines.
Overnight Headlines
Trump May Hold Off Further Iran Strikes Without Fresh Provocations
Iran Targets Bahrain Base But Says Path To US Deal Remains Open
Iran Claims Three Oil Tankers Set Ablaze By Mines In Strait Of Hormuz
Saudi-Backed Forces Retreat Near Bab El-Mandeb As Houthis Advance
Zelenskyy Says US Floats NATO Membership In Exchange For Donbas
US Envoy Kushner Seeks Direct Russia-Europe Talks On Ukraine Peace
Trump To Discuss Nuclear Arms Cuts With Putin, Xi At Thurs Summit
US And Allies Sign Accord To Protect AI Supply Chains From China
Fed’s Collins Says ‘Steady, Gradual’ Rate Hikes Appropriate
Brussels To Propose €45B Ukraine Loan Backed By EU Budget
ECB Tools Can’t Replace Sound Fiscal Policy, Knot Tells Corriere
BoE Chief Economist: Further Rate Hikes Needed To Combat Inflation
BoJ's Takata Calls For Swift Hike In Rates To 'Good' Position
Japan's Economy Shrinks As Inflation Squeezes Households
China’s Economy Weakens More Than Forecast Despite Stimulus Push
PBoC Withdraws Medium-Term Funds, Challenging Further Easing Bets
Bessent Calls For Nvidia To Appoint CEO From Outside Company
Trump Admin To Name Nvidia Among AI ‘National Champions’
SpaceX’s S&P 500 Bid Revived As Musk Pitches Tesla Merger
Boeing-Lockheed Rocket Failure Destroys Amazon (AMZN) Satellite Payload
J&J Eyes Acquisition Of Eye Disease Biotech For Up To $3.4B
VW CEO Blume Aims To Achieve Record Returns By 2030
Alibaba (BABA) Unveils New Flagship AI Model To Challenge US Rivals
Comments
Log in or sign up to join the conversation.