
Image: Bigstock
The recent selloff in technology and semiconductor stocks has created potential buying opportunities, particularly among companies benefiting from the artificial intelligence (AI) infrastructure boom.
Taiwan Semiconductor Manufacturing Company (TSM - Free Report) stands out after delivering better-than-expected third-quarter results on Thursday and issuing upbeat Q4 guidance, reinforcing its position as a leading supplier of advanced chips.
With strong earnings momentum and a favorable growth outlook, TSM may be an attractive stock to consider following the recent market pullback as shares have fallen 9% this month but are still up 36% year to date.
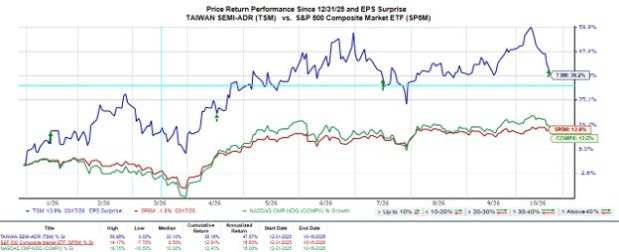
Image Source: Zacks Investment Research
Taiwan Semiconductor’s Record Q3 Results
Fueled by surging demand for advanced chips used in AI infrastructure, Taiwan Semiconductor’s Q3 earnings reached a quarterly record of $4.60 per share, beating the Zacks Consensus Estimate of $4.45 by 3% and climbing 57% from EPS of $2.92 a year ago.
This came as Q3 revenue surged 41% year over year to a quarterly peak of $46.72 billion, surpassing expectations of $45.61 billion. Gross margin remained robust at 66.4%, while operating margin reached 58.7%.
Notably, advanced semiconductor technologies accounted for 79% of wafer revenue, reflecting strong demand from major customers such as Nvidia (NVDA - Free Report), Apple (AAPL - Free Report), and Advanced Micro Devices (AMD - Free Report).
It’s also noteworthy that Taiwan Semiconductor has now exceeded earnings expectations for a remarkable 24 consecutive quarters, with an average EPS surprise of 7.78% in its last four quarterly reports.
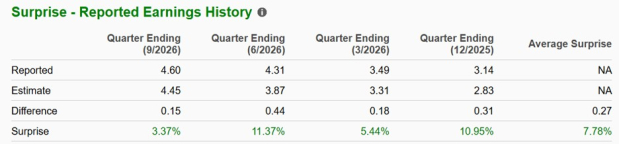
Image Source: Zacks Investment Research
Taiwan Semi’s Favorable Guidance
Looking ahead, TSMC projected Q4 revenue of $52.3-$54.3 billion, implying 58% YoY growth at the midpoint and comfortably exceeding Wall Street's expectations of roughly $50.22 billion.
The company also anticipates gross margins of 65%-67%, signaling continued profitability as it expands production of next-generation chips.
Monitoring TSM’s Valuation
At current levels of around $412 a share, TSM trades at 25X forward earnings, representing only a modest premium to the benchmark S&P 500 and the broader Zacks Computer and Technology sector's 23X.
Considering Taiwan Semiconductor is the world's largest dedicated semiconductor foundry provider and a critical supplier to leading AI chipmakers, this valuation still appears reasonable given its impressive earnings growth and favorable outlook.
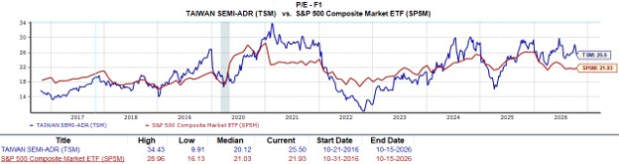
Image Source: Zacks Investment Research
Bottom Line
Despite recent selling pressure across semiconductor stocks, Taiwan Semiconductor's Q3 earnings beat and upbeat Q4 guidance reinforce its position as a leading beneficiary of the AI infrastructure boom.
With accelerating demand for advanced chips and encouraging growth prospects, TSM currently sports a Zacks Rank #2 (Buy), supported by favorable earnings estimate revisions that could gain further momentum following its impressive Q3 report.
Comments
Log in or sign up to join the conversation.