
The S&P 500 (Index: SPX) closed out the trading week ending on Friday, 23 October 2026 a little under a half percent from its previous week's close. The index went into the weekend at 7,623.68, which is 2.5% below its record high close of 7,818.93 back on 6 October 2026.
What the Federal Reserve will be doing with interest rates continued to dominate investor attention during the week that was. With Fed officials silent in blackout mode in the week ahead of their scheduled meeting on 27-28 October 2026 to determine their next actions, investors had little information to go on.
It showed in how little expectations changed for how the Fed will set the Federal Funds Rate in the weeks ahead. The CME Group's FedWatch Tool continues to project the Fed skip taking any action during this week's meeting and will next act to hike the Federal Funds Rate by a quarter point at the end of its next meeting on 9 December (2026-Q4). That hike would be followed by another quarter point rate hike that will be announced when the Fed's rate-setting Open Market Committee meets on 17 March (2027-Q1).
After that, the FedWatch Tool anticipates one more rate hike in 2027, coming when the Fed meets on 15 September (2027-Q3). That's 18 weeks later than what it projected a week earlier, but in reality, it wouldn't take much to move it earlier on the calendar, say to June (2027-Q2).
The latest update of the alternative futures chart shows stock prices dropped to the lower end of the range associated with investors focusing on the current quarter of 2026-Q4 as they set current day stock prices.
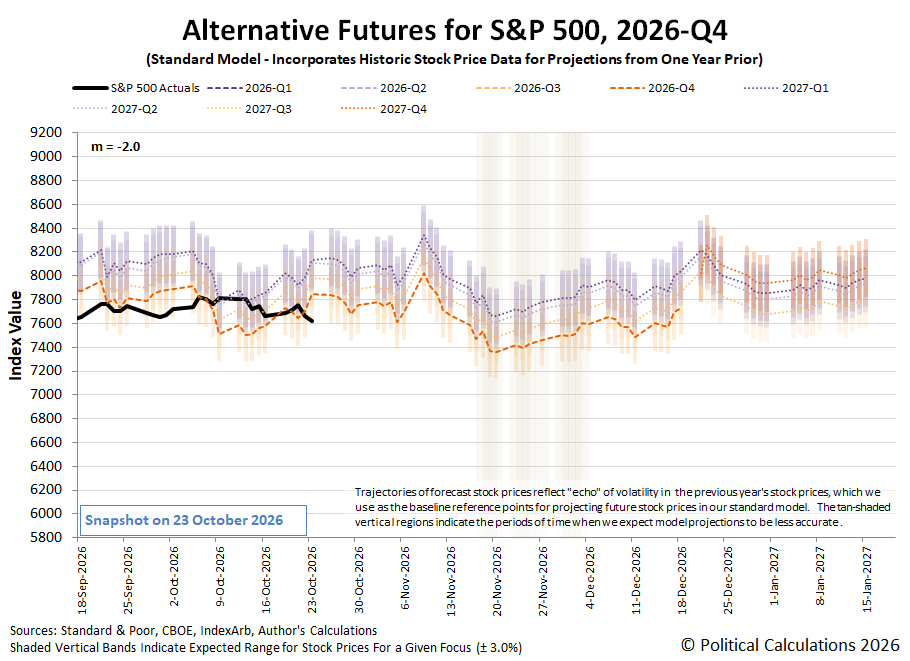
That downward adjustment mostly took place in the latter part of the week. It came about as investors became increasingly concerned over how much tech companies are spending to realize their plans for building and implementing AI systems and also because also because oil prices increased because of ongoing geopolitical events in the Middle East. While neither of these are new concerns, in the absence of direction on the future for interest rates from the Fed, they represented the bulk of new information investors had to absorb during the week that was.
Here are the week's market-moving headlines.
Monday, 19 October 2026
Signs and portents for the U.S. economy:
Fed minions upset AI boom is keeping U.S. economy growing:
Bigger domestic trouble, export growth developing in China:
BOJ minions admit Japan's inflation is almost where they want it, are expected to use it to justify more rate hikes:
S&P 500, Nasdaq advance ahead of mega-cap companies’ earnings
Tuesday, 20 October 2026
Signs and portents for the U.S. economy:
Housing is flashing warning signs just as the Fed weighs more interest rate hikes
China's September US soybean imports rebound from zero a year earlier, data shows
Brent hits five-month high as attacks on ships, Saudi sites fuel supply worries
AI data center projects boost US warehouse demand and rents, real estate company JLL says
Economists expect Fed minions to sit on their hands in October 2026:
Smaller stimulus, bigger trouble developing in China:
BOJ minions see more rate hikes ahead as they boost inflation forecast and wage-price inflation spiral gets going:
Growth signs developing in Eurozone:
Dow outperforms as Wall Street rises, healthcare stocks lead gains
Wednesday, 21 October 2026
Signs and portents for the U.S. economy:
Bigger trouble, higher interest rates developing in Japan:
Strange economic metaphor developing in Eurozone:
Bigger trouble still developing in Eurozone:
Nasdaq leads Wall Street gains as SpaceX, Super Micro boost AI sentiment
Thursday, 22 October 2026
Signs and portents for the U.S. economy:
Former Fed minion says US economy isn't running too hot:
Bigger real estate losses developing in China:
BOJ minions worrying less about propping up Japan's currency, see other reasons to keep hiking Japan's interest rates:
Bigger trouble developing in Eurozone, ECB minions want to do away with national economies within Eurozone:
Nasdaq, S&P decline as AI spending worries weaken investor sentiment, U.S. stocks suffer
Friday, 23 October 2026
Signs and portents for the U.S. economy:
Bigger trouble, stimulus developing in China:
BOJ minions getting excited to hike interest rates again as bigger trouble develops in Japan:
Bigger trouble developing in Eurozone:
S&P 500 ends lower for week as AI spending concerns and rising oil prices weigh
The Atlanta Fed's GDPNow tool's projection of real GDP growth for the U.S. economy in 2026-Q3 dipped 0.1% to 3.1% this week. After the BEA releases its initial estimate of GDP for 2026-Q3 on 29 October 2026, the GDPNow tool will shift toward projecting 2026-Q4's real GDP growth rate.
Comments
Log in or sign up to join the conversation.