
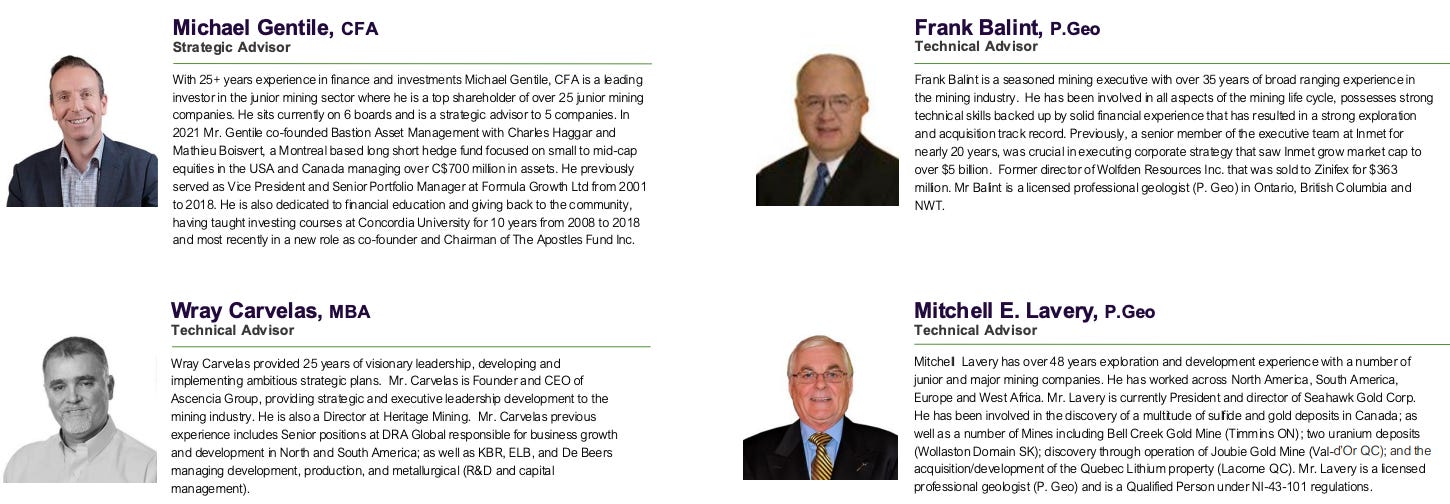
Unlike most so-called “silver” companies that might be only 30–60% silver, Silver Crown Royalties (ticker: SCRI) has effectively 100% pure-play silver exposure. Generalist investors like pure-play exposure, low operational risk, and open-ended growth. But, it’s really hard to find.
Very, very few companies are as leveraged to silver (“Ag”) as Silver Crown. New Pacific Metals is all Ag, but 100% if its assets are in Bolivia, not the safest basket to have all one’s eggs in.
By contrast, as an Ag-only royalty company, Silver Crown’s portfolio is spread across Canada, Brazil & Ecuador. By this time next year, there’s a good chance more countries will be represented.
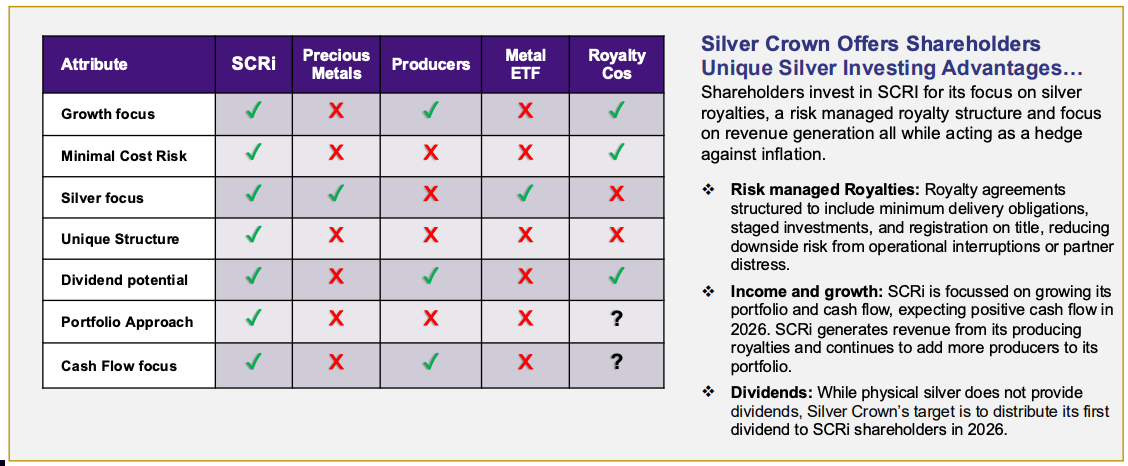
Readers can buy the ETF ticker SLV for pure-pay Ag leverage, but royalty companies offer far more torque. If Ag were to double (not that crazy, returning to its ATH of late-Jan 2026), SLV would double. However, Silver Crown could potentially more than double for three primary reasons.
On top of the same gain in the Ag price, it could also benefit from industry-wide or company specific earnings multiple expansion. It could gain from ongoing attributable production growth, and/or from incremental ounces via new transactions.
And, it could gain from greater interest in royalty/streaming or metals/mining plays. Therefore, if one’s bullish on Ag, first and foremost one should consider owning shares of Silver Crown Royalties. Then, perhaps SLV, and/or other high-quality Ag-heavy juniors. But remember, Silver Crown is truly unique.
Its latest asset acquisitions are why its share price has held up better than Ag-heavy companies and royalty/streaming peers. Readers should note the share price gain to the mid-$30s from under $10. This gives management much more valuable share “currency” to use in upcoming transactions.
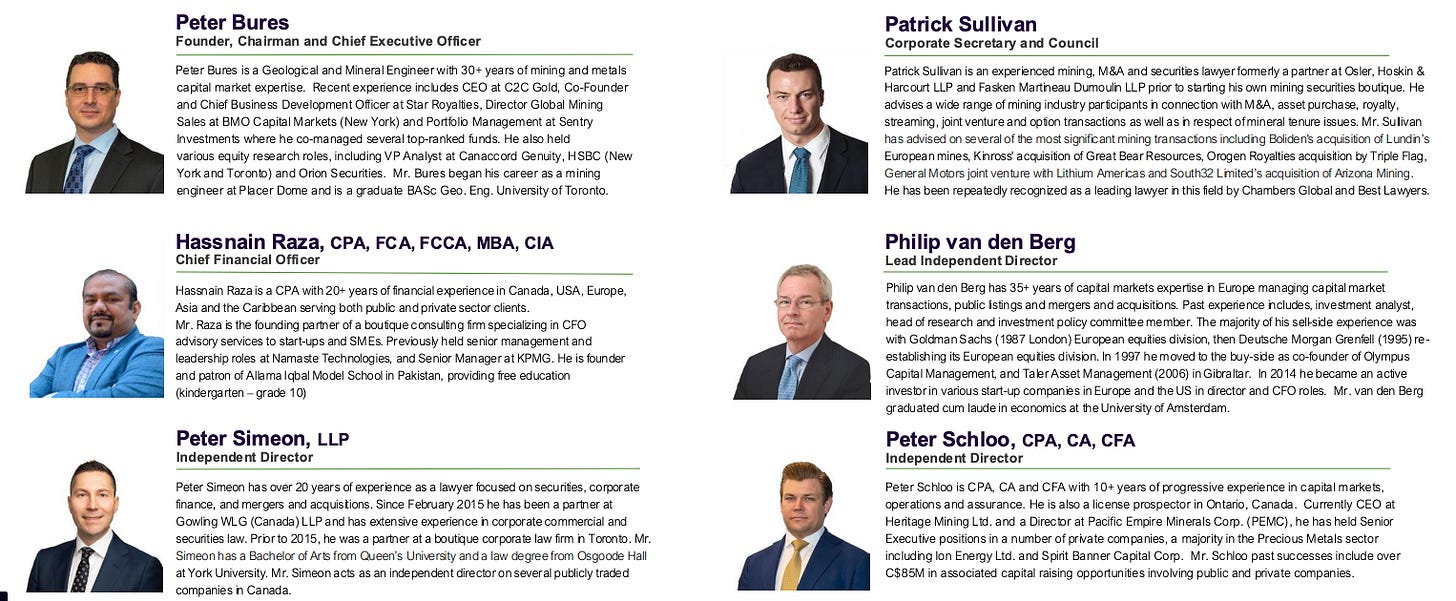
In early June, management, led by CEO Peter Bures, announced the acquisition of two existing 1% net smelter return royalties (“NSRs”) on Titiminas Silver Inc.’s Madre Sierra project in central Peru for US$6M in cash, plus US$1M to the holder of each royalty upon first royalty payment.
In early September a third private 1% NSR was acquired. All three NSRs have an all-in maximum cost (with contingencies) of US$4M each.
Madre Sierra is a past-producing mine with numerous surface access points and working faces targeting small scale (70 to 100 tonnes per day [“tpd”]) production. Silver Crown believes that Titiminas Silver’s production could increase towards 1,000 tpd in 18 to 24 months.
This is a fairly high-grade mine (~140 g/t Ag-only), with solid reported Ag recoveries in the mid-to-high 80’s percent. Silver Crown anticipates that if Titiminas executes reasonably on plan, run-rate annual revenue from the three NSRs could reach the cash equivalent of ~90,000 ounces/yr. in 2028.
Titiminas controls a significant land package in a past-producing camp, so these uncapped NSRs could potentially produce for decades. Silver Crown Royalties had ~C$15M in cash before paying out the US$6M.
A prior royalty on PPX Mining really moved the needle, but the latest acquired NSRs are poised to generate more cash flow, for a longer time.
At an assumed US$70/oz Ag, the IRR on PPX would approach 100%. Consider that when the PPX royalty was signed, the Ag price was < $31/oz, about half the current level and a quarter of January’s ATH.
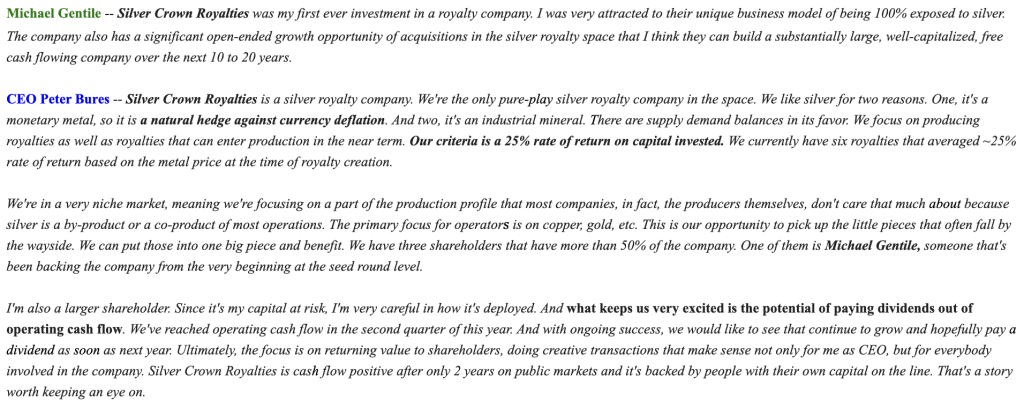
Minimum deliveries (the cash equivalent of) 14,062.5 ounces per quarter, commenced earlier this year. At the front-month Ag price of ~$61/oz, this single royalty equates to ~C$4.9M/yr. in cash flow for the next 3.5 years, bridging the Company to bigger & better transactions. CEO Bures has > 10 deals under careful review at any given time.
Very important shareholder Michael Gentile is great at communicating Silver Crown’s investment thesis and continues to attract attention to the name. He has a hot hand, a string of successes. Each time he enjoys a win, investors look at what he’s invested in…
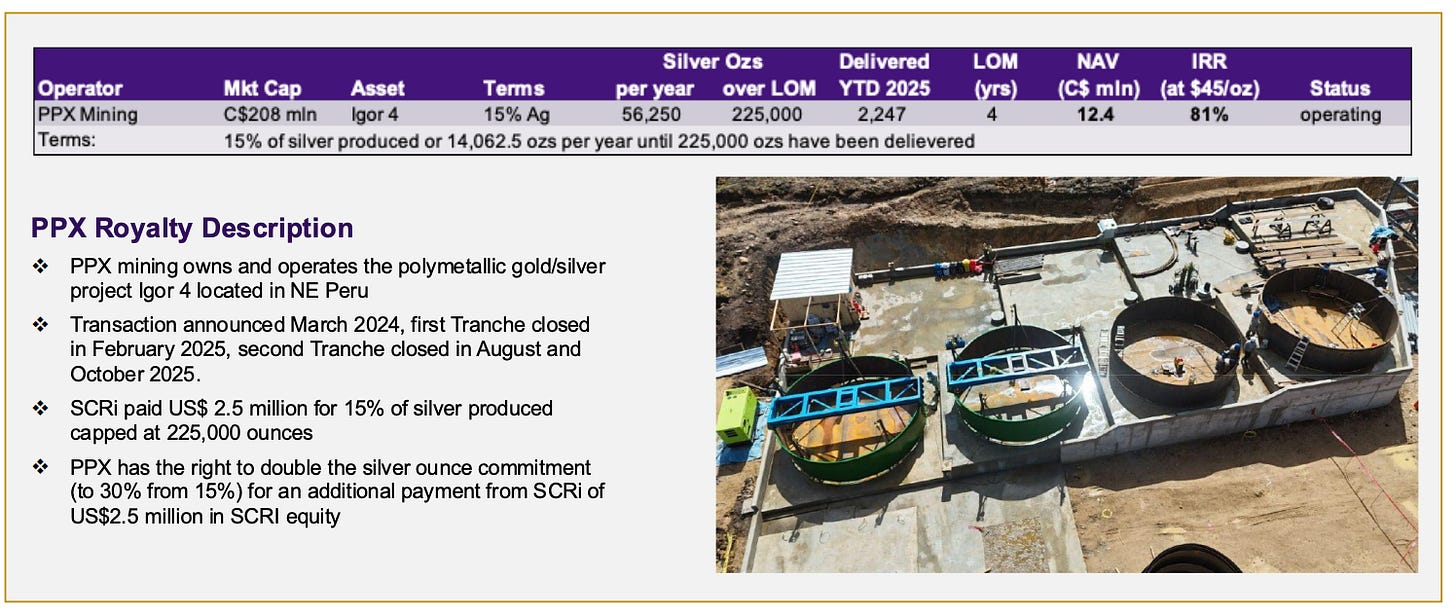
Mr. Gentile is the largest shareholder in over 25 juniors, sits on several company boards, and is a valued strategic advisor.
While Gentile appreciates the royalty model, he has major issues with the small / micro-cap junior royalty space. He says many junior royalty companies claim they will be “the next Franco Nevada.”
Yet Franco Nevada succeeded because it was the one of the first royalty/streaming companies. As such, it had first pick of deals, wrote high-IRR (20–30%) perpetual royalties, and the market rewarded it with a 2× P/NAV multiple and a very low cost of capital (~5%).
By contrast, most junior royalty companies face the opposite problem. They have high costs of capital (20%+). Gentile believes that Silver Crown’s model is superior.
Roughly 70-75% of the world’s silver comes as a byproduct. In a gold or copper mine, silver might be only a few percent of total revenue, with no formal resource/reserve estimate. Therefore, many projects don’t even bother valuing their contained silver.
Silver Crown creates royalties specifically on a company’s tiny silver “stubs.” This methodology creates an essentially unlimited acquisition runway in a niche where management does not compete head-on with much larger royalty companies.
In prior articles on Silver Crown, I’ve pointed out that the past year has not been smooth sailing. The Company has had a few setbacks, but new assets coming in, like the Titiminas Silver existing royalties, are far larger than the troubled deals.
To be clear, with strong IRRs there’s room for problems, it’s simply a cost of doing business. As the number of portfolio assets grows, diversifying risk across multiple fronts, and if/when the Ag price retakes $70, $80, $90… per troy ounce, Silver Crown’s business model will shine.
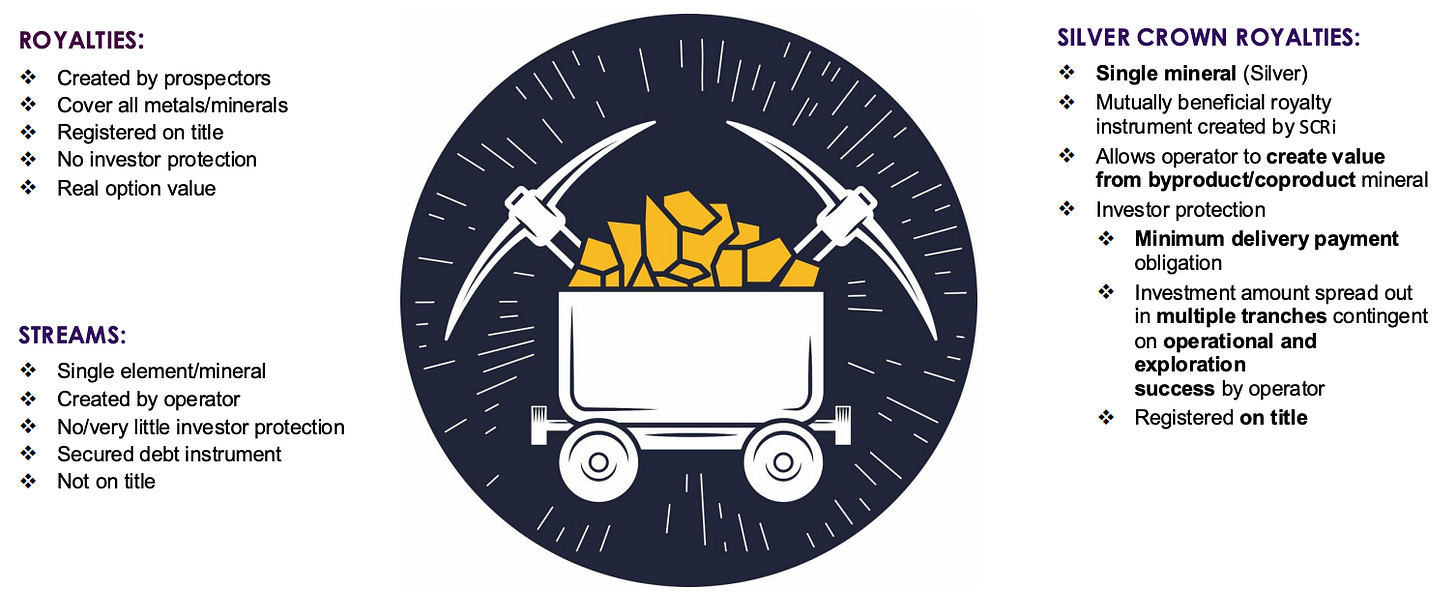
Not just as one of the best royalty/streamers, but the best way to gain turbo-charged exposure to silver. Admittedly, this is a much higher risk royalty company than Franco-Nevada, But with higher risk comes higher return potential in a bull market.
Franco is valued at ~15x 2028e revenue. For Silver Crown were to achieve that 15x 2028e revenue multiple, it would need to take in ~C$13M in 2028. By 2028 revenue could be a lot higher than that, especially factoring in future transactions.
Disclosures/disclaimers: The content of this article is for information only. Readers fully understand and agree that nothing contained herein, written by Peter Epstein of Epstein Research [ER], (together, [ER] ) about Silver Crown Royalties, including but not limited to, commentary, opinions, views, assumptions, reported facts, calculations, etc. is not to be considered implicit or explicit investment advice. Nothing contained herein is a recommendation or solicitation to buy or sell any security. [ER] is not responsible under any circumstances for investment actions taken by the reader. [ER] has never been, and is not currently, a registered or licensed financial advisor or broker/dealer, investment advisor, stockbroker, trader, money manager, compliance or legal officer, and does not perform market-making activities. [ER] is not directly employed by any company, group, organization, party, or person. The shares of Silver Crown Royalties are highly speculative, and not suitable for all investors. Readers understand and agree that investments in small-cap stocks can result in a 100% loss of invested funds. It is assumed and agreed upon by readers that they will consult with their own licensed or registered financial advisors before making investment decisions.
At the time this article was posted, Silver Crown Royalties was an advertiser on [ER] and Peter Epstein owned shares in the company.
Readers understand and agree that they must conduct due diligence above and beyond reading this article. While the author believes he’s diligent in screening out companies that, for any reason whatsoever, are unattractive investment opportunities, he cannot guarantee that his efforts will (or have been) successful. [ER] is not responsible for any perceived, or actual, errors including, but not limited to, commentary, opinions, views, assumptions, reported facts & financial calculations, or for the completeness of this article or future content. [ER] is not expected or required to subsequently follow or cover events & news, or write about any particular company or topic. [ER] is not an expert in any company, industry sector, or investment topic.
Comments
Log in or sign up to join the conversation.