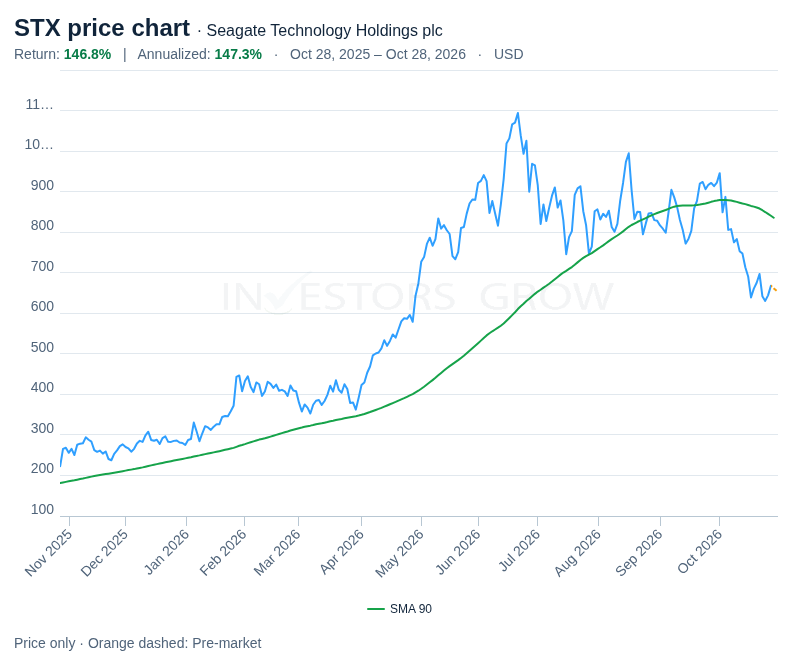
More of each sales dollar is turning into profitSeagate, the hard drive maker, reported $4.233 billion in revenue in yesterday's earnings release, compared with $2.629 billion a year earlier. The more revealing number was its gross margin: 57.3%, up from 39.4%.
|
The results show a much stronger business. Whether that strength lasts depends on two things working together: technology that lowers the cost of supplying storage, and pricing that lets Seagate keep some of the benefit. This quarter demonstrates the profitability; it leaves the durability question open.
|
Gross margin is the share of sales left after covering the cost of the products sold, before expenses such as research, administration and interest. Seagate is generating more revenue and keeping a much larger portion of it at that first stage of the profit calculation. These are GAAP figures, prepared under standard accounting rules, so the improvement also shows up outside the company's adjusted results.
|
The results cover fiscal first quarter 2027, which ended October 2, 2026. All financial amounts here are in US dollars.
|
Sales grew much faster than nearline shipmentsRevenue rose 17% from the preceding quarter. Yet management described the amount of nearline storage shipped as relatively flat. Nearline hard drives are large capacity drives used for data center storage.
|
Seagate brought in considerably more revenue without a comparable increase in the amount of nearline storage it delivered. Management credited favorable pricing and product mix, meaning the combination of products sold.
|
That comparison does not give us an exact price increase. Total company revenue covers more than nearline drives, and different products sell at different prices. It does show why contract pricing deserves as much attention as growth in storage demand.
|
Data Center accounted for 81% of quarterly revenue. Management argues that AI gives customers more reasons to retain and reuse information. The connection to storage is straightforward: data that remains useful needs somewhere to live. How much Seagate earns from that demand depends on what customers pay and what the drives cost to make.
|
More data on each disk can change the economicsSeagate's main technological lever is HAMR, short for heat assisted magnetic recording. Its explanation of the technology describes a tiny laser briefly heating a spot on a disk so the recording head can write smaller magnetic bits that remain stable afterward. Smaller bits let more information fit on the disk surface.
|
For a customer, a higher capacity drive means more storage in the same data center space. For Seagate, it offers a way to ship more storage without a matching increase in the number of physical drives it produces.
|
If manufacturing goes well, that can lower Seagate's internal cost for each unit of storage. Customers may also save on space and supporting equipment. Those benefits could give Seagate room to retain some of the value through pricing, rather than passing every manufacturing improvement along as a lower price.
|
Purchased components complicate the picture. Management says their rising costs are offsetting some internal cost reductions. Part of a selling price increase may simply cover a larger supplier bill. What matters for profit is how selling prices move relative to total costs.
|
Customers have reserved supply. Prices still matter.Management says the vast majority of Seagate's nearline storage supply is allocated through calendar 2028, with some cloud customer agreements extending through calendar 2030. That gives the company a useful view of customers' plans.
|
But the agreements are at different stages. Management says product configurations and pricing are established for nearline shipments through calendar 2027. It expects to begin finalizing those terms for calendar 2028 over the next few quarters. Reserved capacity helps Seagate plan production; the agreed prices will help determine how profitable that production becomes.
|
Competing supply could influence those negotiations. In an October 2 expansion announcement, Toshiba said its Philippine operation had made its first shipment from an expanded nearline drive production line. The operation aims to nearly double its annual production capacity by Toshiba's fiscal 2027 compared with fiscal 2025, measured by storage capacity rather than the number of drives.
|
A capacity target still has to translate into reliable products that customers buy. Even so, the expansion is a concrete reason to question whether supply will remain tight. Higher capacity drives add more available storage even without a matching increase in drive production. If that supply grows faster than customers' purchases, future pricing could weaken while the amount of data being stored continues to rise.
|
The stronger profits are producing cashSeagate reported approximately $1.7 billion of operating cash flow and $1.5 billion of free cash flow for the quarter. Free cash flow is cash from operations after capital spending, such as investment in manufacturing equipment.
|
That cash gives the company choices: fund technology development, repay lenders or return money to shareholders. Seagate retired approximately $1.2 billion of principal debt during the quarter. After the quarter ended, it retired another $750 million, bringing principal debt to approximately $1.6 billion.
|
Lower debt reduces financing pressure and can lower interest expense. It also leaves the company more flexibility if customer purchases slow. The caution is in treating this quarter as a repeatable cash generation rate. Payment timing, inventory investment and future equipment needs can all change how much cash remains available.
|
Can shipment growth reinforce the pricing gains?Management forecasts fiscal second quarter 2027 revenue of $4.8 billion, plus or minus $100 million. It says its newer Mozaic 4 drives are ramping with two leading cloud providers, with additional customer qualifications expected. Those qualifications are the approval process needed before broader deployment.
|
Stronger shipment growth would help show that the improvement extends beyond pricing. Further manufacturing cost reductions would support the technology argument. And the terms negotiated for calendar 2028 will tell us more about how much pricing strength Seagate can carry into future shipments.
|
The strongest version of the story combines more storage shipped, lower internal cost per unit and prices that preserve healthy profits. Slower customer purchases, difficult product transitions or faster growth in competing supply could weaken that combination.
|
Management credits demand, pricing and product improvements for this quarter's profitability. Whether Seagate can sustain that profitability will depend on how those forces hold up through the next round of customer negotiations. |
|


Comments
Log in or sign up to join the conversation.