
Year-over-year trends are downright awful.
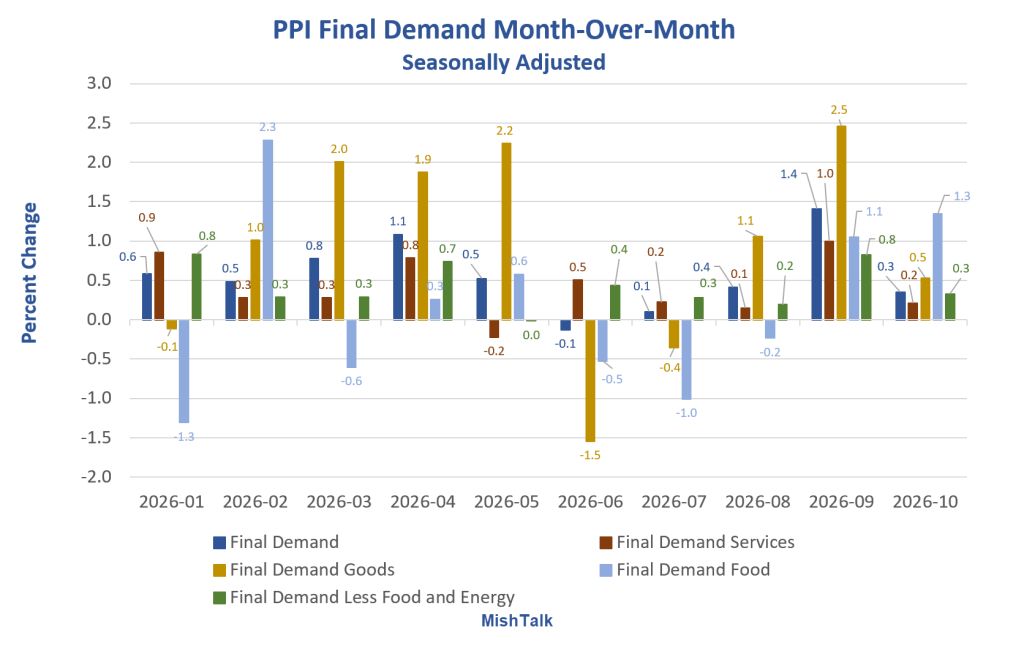
PPI Final Demand Month-Over-Month Percent Change
PPI September 2026
Please consider the BLS Producer Price Report for October 2026.
The Producer Price Index for final demand rose 0.3 percent in October, seasonally adjusted.
Final demand prices advanced 1.4 percent in September and 0.4 percent in August.
On an unadjusted basis, the index for final demand increased 6.5 percent for the 12 months ended in October, the largest 12-month rise since moving up 7.4 percent in November 2022.
PPI Final Demand Month-Over-Month Details
Final Demand: 0.3 percent
Final Demand Goods: 0.5 percent
Final Demand Services: 0.2 percent
Final Demand Food: 1.3 percent
Final Demand Less Food and Energy: 0.3 percent
For the second month, there has been a big jump in the PPI food index.
Final Demand Synopsis
Final Demand Goods: The index for final demand goods increased 0.5 percent in October following a 2.5-percent rise in September. Over 60 percent of the advance in October is attributable to prices for final demand goods less foods and energy, which moved up 0.5 percent. The index for final demand foods increased 1.3 percent. In contrast, prices for final demand energy edged down 0.1 percent. For the 12 months ended in October, the index for final demand goods increased 10.2 percent, the largest 12-month rise since advancing 10.5 percent in October 2022.
Goods Detail: Within the index for final demand goods in October, prices for basic organic chemicals advanced 3.9 percent. The indexes for fresh and dry vegetables; gas fuels; aeronautical, nautical, and navigational instruments; jet fuel; and processed young chickens also moved higher. Conversely, diesel fuel prices fell 7.9 percent. The indexes for pork and for passenger cars also declined.
Final Demand Services: The index for final demand services moved up 0.2 percent in October, the fifth consecutive advance. Three-fourths of the October rise can be traced to a 2.0-percent increase in prices for final demand transportation and warehousing services. The index for final demand services less trade, transportation, and warehousing advanced 0.2 percent. In contrast, margins for final demand trade services decreased 0.2 percent.
Services Detail: Over 80 percent of the October increase in the index for final demand services is attributable to prices for truck transportation of freight, which rose 3.9 percent. The indexes for fuels and lubricants retailing; health, beauty, and optical goods retailing; food and alcohol wholesaling; hospital outpatient care; and traveler accommodation services also moved higher. Conversely, margins for machinery and vehicle wholesaling fell 4.2 percent. Prices for system software publishing and for airline passenger services also declined.
PPI Final Demand Year-Over-Year
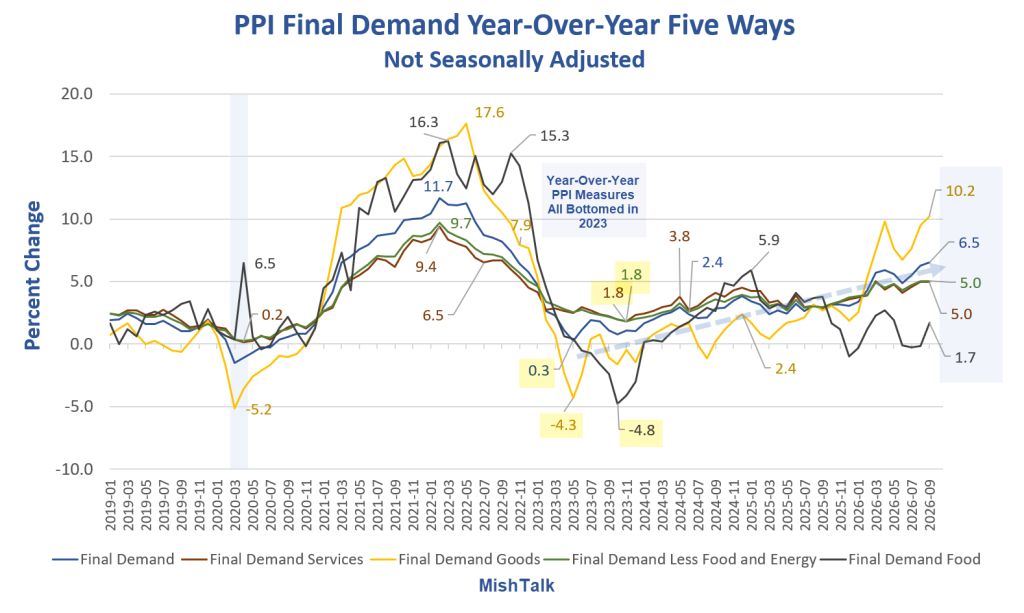
PPI Final Demand Year-Over-Year Percent Change
PPI Final Demand Year-Over-Year Notes
Final Demand: 6.5 percent
Final Demand Services: 5.0 percent
Final Demand Goods: 10.2 percent
Final Demand Less Food and Energy: 5.0 percent
Final Demand Food: 1.7 percent
PPI Final Demand Services
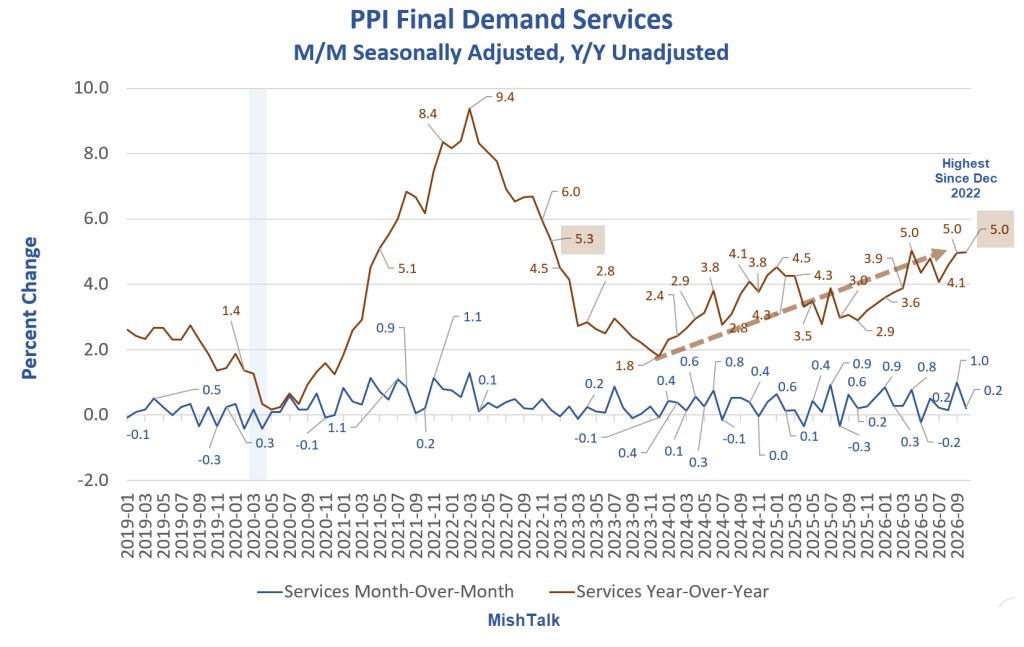
PPI Final Demand Services Month-Over-Month and Year-Over-Year Percent Change
Services Key Points
Services represent a dominant portion of the Producer Price Index (PPI) for final demand, accounting for approximately 68% to over 70% of total PPI coverage as of early 2026.
Services are often the primary driver of PPI inflation, significantly outweighing goods.
The trend in services is now ominous. Year-over-year services PPI is up 5.0 percent.
PPI Synopsis
What’s happening now is neither temporary nor random.
Prices declined following the memorandum of understanding (MOU) with Iran, opening the Strait of Hormuz. The strait is now closed again.
Price pressures will persist as long as the strait is closed. Additionally, Trump’s foolish trade war with Canada and the rest of the world is adding to price pressures.
Looking Back and Ahead
The midterm elections are over. Voters undeniably voted for change.
However, Trump is plowing ahead with deportations and tariffs. Both rate to drive up prices.
No one knows yet what Trump will do with Iran, but it’s guaranteed that Israeli prime minister Benjamin will press for more war.
Expect a Quarter-Point Hike in December
In August I called for a hike in September, none in October, and one in December.
That has been an easy call for months.
The Fed did not want to hike ahead of the election and despite Warsh’s alleged “no forward guidance” policy, a parade of Fed Governors came out of the woodwork to kill what was once an odd-on October hike, that I mocked at the time.
Today’s PPI report following a bad CPI report sealed the December hike. And it’s a single hike too, despite lots of yap about a 50-basis-point hike.
A quick check on CME Fedwatch shows implied odds of single hike at 93.7 percent with a 6.3 percent chance of a half-point hike.
Forget the double hike idea. The double-hike odds are down from 18.7 percent from a month ago. And even if the PPI report was much worse, I highly doubt the Fed would have pulled the trigger.
This is easy stuff. The Fed is always slow to hike and fast to cut. That is what you need to remember.
Related Posts
October 15, 2026: Trump Promised to Reduce Energy Bills in Half. How’s He Doing?
Let’s check in on a Trump campaign promise.
November 10, 2026: CPI Hotter than Expected Again. Expect a December Fed Rate Hike
This was the third consecutive bad month for CPI inflation.
Another Fed Rate Hike Coming
In August I said “A rate hike in September is all but certain after this report.”
And so it was.
Last month I said there would not be a hike in October, but there should be. That was correct as well.
My statement from a month ago was “As of now, expect a December hike. There is no November meeting.”
The Fed went out of its way to issue forward guidance when a parade of Fed governors and presidents pushed back on an October rate hike, without mentioning the obvious reason – the election.
Fed Chair Kevin Warsh stopped forward guidance in theory, but not practice, The Fed will always find a reason to do what it wants and telegraph it, forward guidance or not.
The Fed is behind the curve again.
November 10, 2026: Fed Rate Hike Odds Hit 100 Percent for December After CPI Report
There was nothing to like in today’s CPI report.
For a brief time today, the implied CME Fedwatch odds of a 25-basis-point hike plus a 50-basis-point-hike added to over 100 percent.
The double hike odds soared to something like a 22 percent chance. I failed to capture the chart, but made a mental diagnosis – forget about it.
It’s always baby steps on hikes. Giant steps are reserved for rate cuts.
Comments
Log in or sign up to join the conversation.