

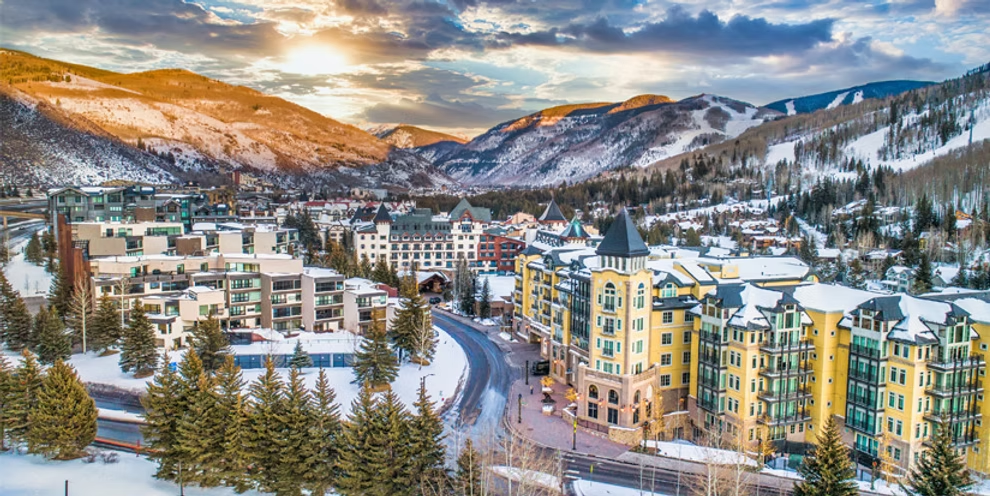
For the past month, I’ve called Southeast Wyoming home. It’s been quite an adjustment since I’ve always lived at near sea-level and in fairly high humidity. But I swear each Wyoming sunset is more beautiful than the last.
Last week, I was talking to a new friend about areas that I’ve been and those I want to visit. Wyoming is not a small state. Heading to South Dakota from Laramie will take you 5 hours and Montana at least 6. Colorado makes the most sense for quick day trips since I am only about 30 minutes from the state line.
He was telling me about a recent trip to Boulder and that he was recently in Vail for a conference. I was very interested as I had run a stock screener earlier in the day and Vail Resorts (MTN) was one of the results.
But his demeanor changed completely when we got to that part of the conversation. It sounded like what was once a quaint, unique mountain town now feels more like a theme park.
The story is not unfamiliar:
Corporation finds a profitable idea
Corporation streamlines the experience to make it more profitable
Corporation replicates success while expanding
The outcome can be higher profits and, in turn, solid dividends for investors. But this raises an important question: How much should your personal opinion on a company’s product weigh on your actual investment?
A Moving Line
I firmly believe that if your portfolio keeps you up at night, then it’s not right for you.
I’m a long-term investor. I plan to hold my positions for many years, even decades for some of them. Short-term market movements don’t give me anxiety. I have a pretty high tolerance level for risk at this point in my life.
If your emotional chemistry is different, your portfolio should reflect that.
If you’re too often worried about your money in the market, you need to make some changes.
I also adjust the types of companies I invest in to match my values and worldview.
Looking at publicly traded private prisons is a good example. Before COVID, the two dominant players were REITs and paid a decent dividend. It did not matter what the yield was because I personally don’t want to share in the profits of the incarceration industry.
I do, however, like to own “sin-vestments” when I spot the right opportunity. My readers are sitting on a 100% gain on shares of Philip Morris (PM), and that does not count the 5 years of dividends we’ve collected.
I’m also bullish on VICI Properties (VICI) right now. The core of its portfolio is casinos, but it has moved into golf courses, indoor water parks, and even bowling alleys in the last few years. That doesn’t bother me, but I know people who refuse to own gambling or tobacco companies on personal principles.
Back to Vail
I haven’t hit the snow slopes since I took some snowboarding lessons at Roundtop back in 2014, but I did take a moment to look into MTN as a potential investment.
The last decade has truly been a story of rapid scaling. At the start of 2015, the company owned just 10 resorts. That number is now 42 and includes properties in Canada, Switzerland, and Australia. Coincidentally, Roundtop is one them, the only ski resort I have had the pleasure of visiting.
Vail Resorts sells what is called an Epic Pass. The pass has three tiers, with the top one covering all 38 North American resorts plus limited international access. I’ve read that this affordably priced access has contributed to overcrowding and lift line congestion at many of its flagship mountains. This could be a real turnoff from the user perspective and eat into the bottom line.
There are a couple of other red flags right off the bat for me. Shares are down over the past 1-year, 5-year, and 10-year time frames. At the same time, we know consumers spend more on “experiences” year after year. According to its last earnings release in June, past sales for this upcoming season are down 10% year over year.
For the third quarter, MTN reported EBITDA of $586.4 million, down 9.4% year over year. Net income of $340 million was down 17%. The company’s per-share net income of $8.82 easily covers the $2.22 quarterly dividend but was less coverage than the same quarter last year.
The latest earnings numbers look like its expansion might have been too aggressive. Or maybe the root of the decline is pushback and opposition from locals and sympathetic ski fans to the death of the small mountain town. Give it another year, and I think that dividend will be at risk. I’ll keep adding VICI to my portfolio for a greater stake in experiential real estate.
Comments
Log in or sign up to join the conversation.