
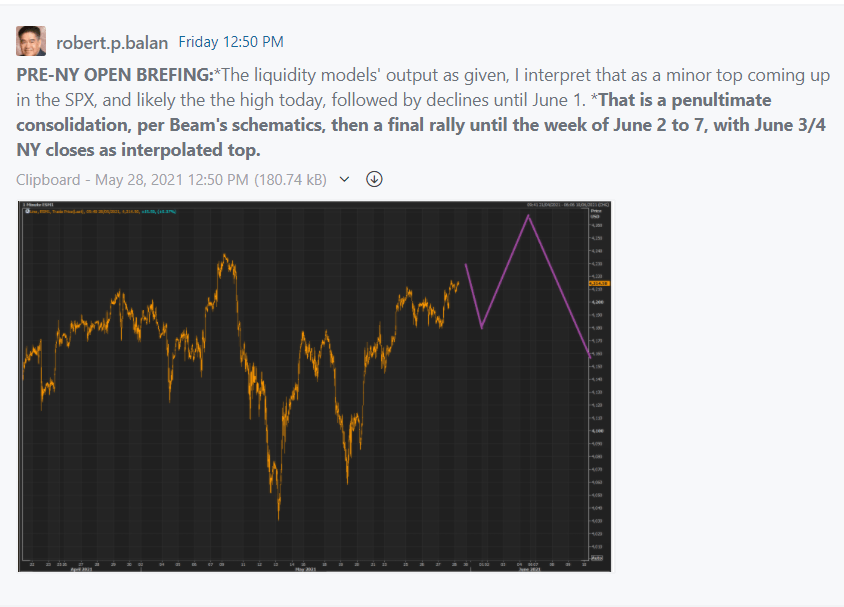
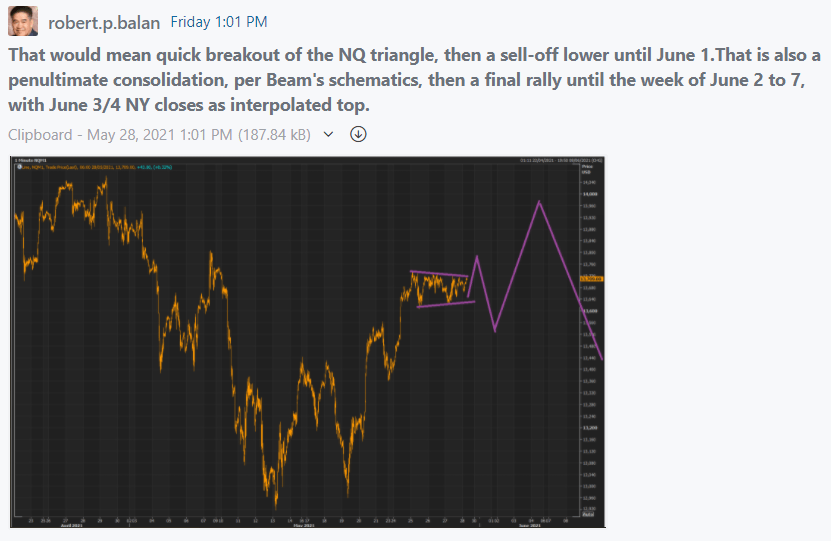
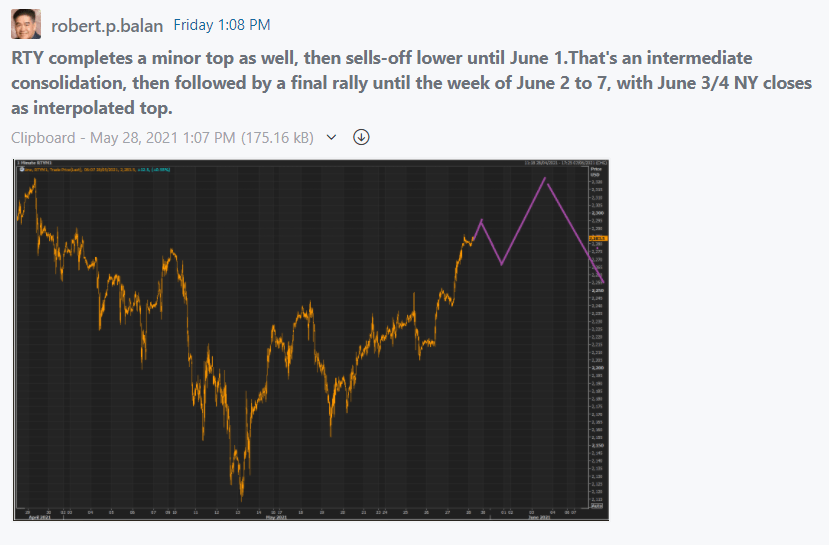
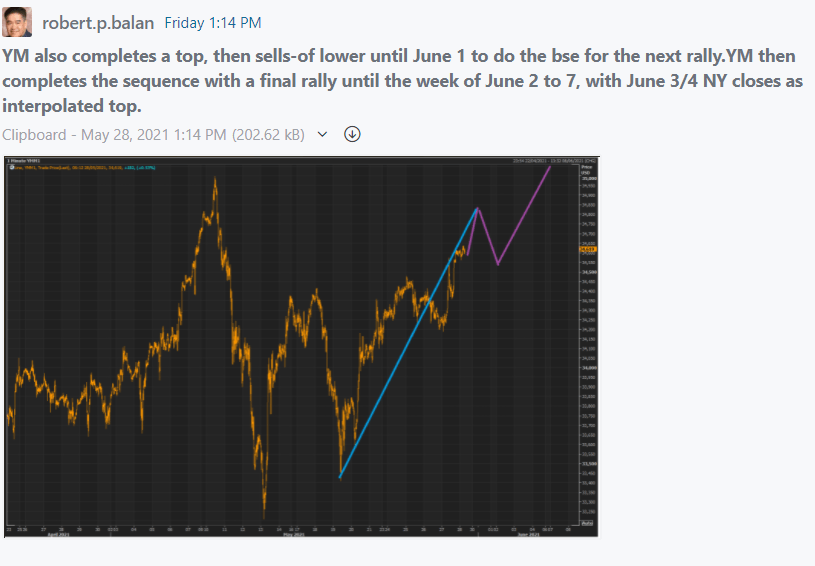
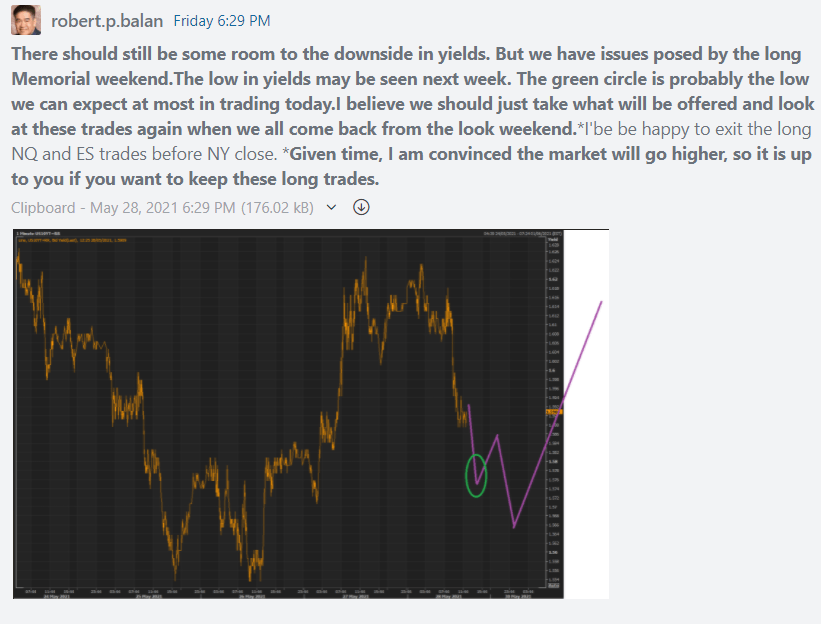
Therefore, on balance, we expect equity futures to drift lower today, and that weakness may possibly extend until tomorrow, June 1, as we have depicted in all the schematics of the equity futures forecast progression.
WE HAVE MADE SOME CHANGES/TWEAKS IN THE VARIOUS LIQUIDITY MODELS:
This will affect the forecasts made by the models, as it extend the potential of the next upside rally from a peak in the first week of June to possibly a peak during the 2nd-3rd week of June.We are dealing with weekly data, and all it takes is be off by one data point -- and that means the forecast is off by 5 trading days. And we were off by one, possibly two data points, in the model calibration.
But we should still see opportunities to reset our long equity positioning by June 1, and ride the next (perhaps final, for the current sequence) rally until late 2nd week-early 3rd week of June. Appropriately, there is a raft of possible triggers for a market sell-off during that period. Remember -- liquidity outflows weaken the market underpinnings, but we still need a trigger to bring the market lower.
Alan.Longbon -- "The June 15th fed tax take should do it."
Albert.Food -- "There is an CPI report on June 10th and a fed meeting on June 18th. Two potential catalysts."
Anyone of these (or all of the above) could bring about a significant sell-off event in sequence later in the 2nd week - 3rd week of June..
This is how the liquidity models currently stand:
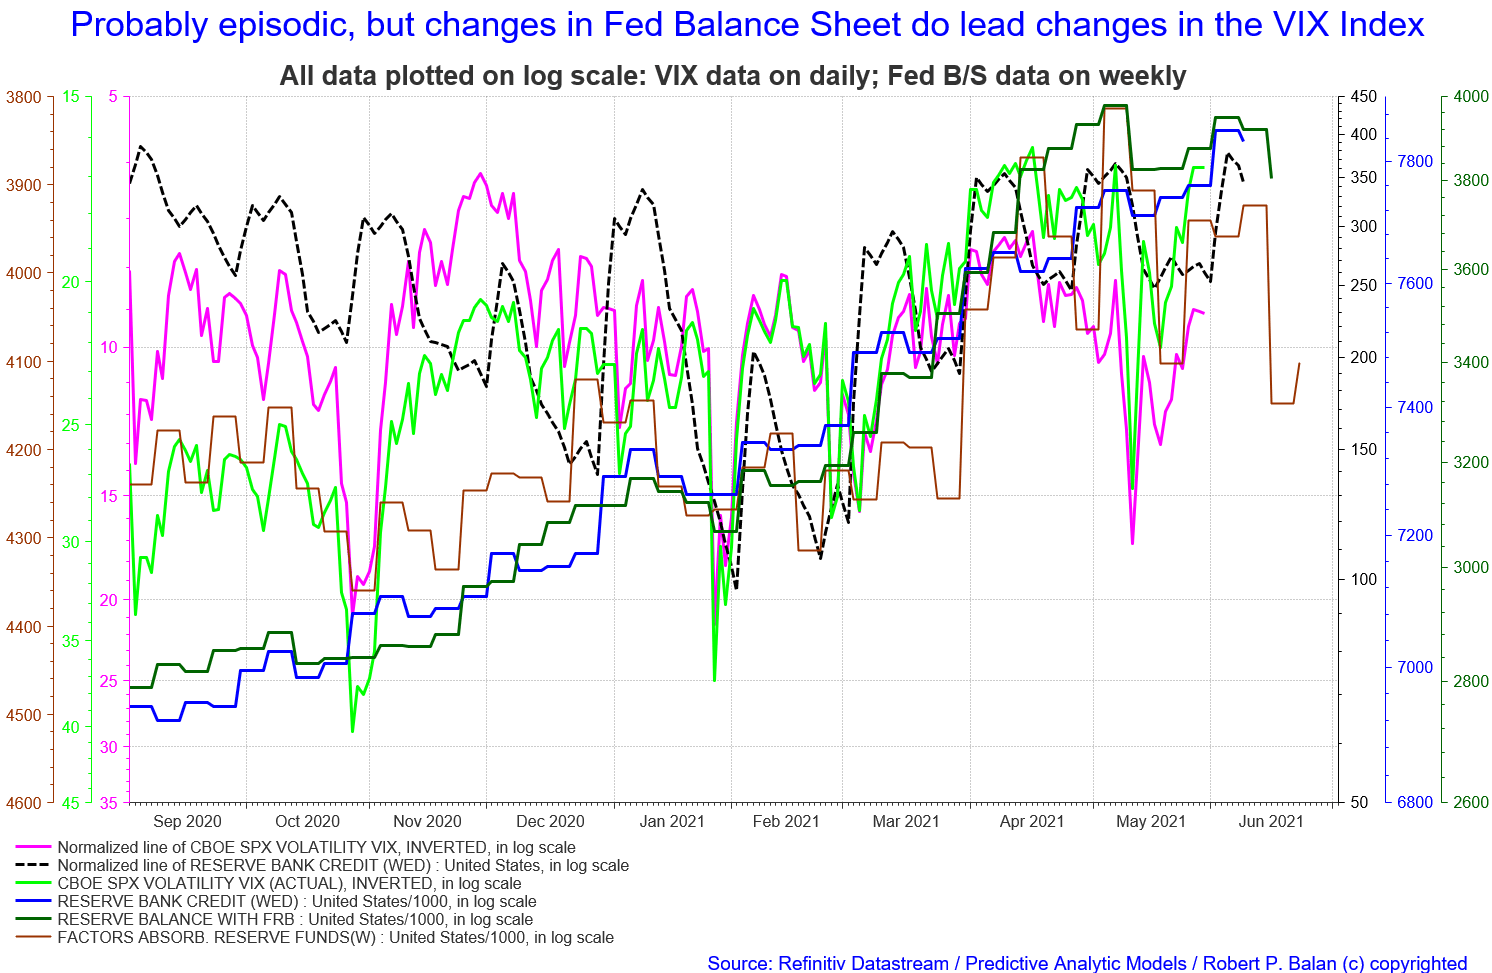
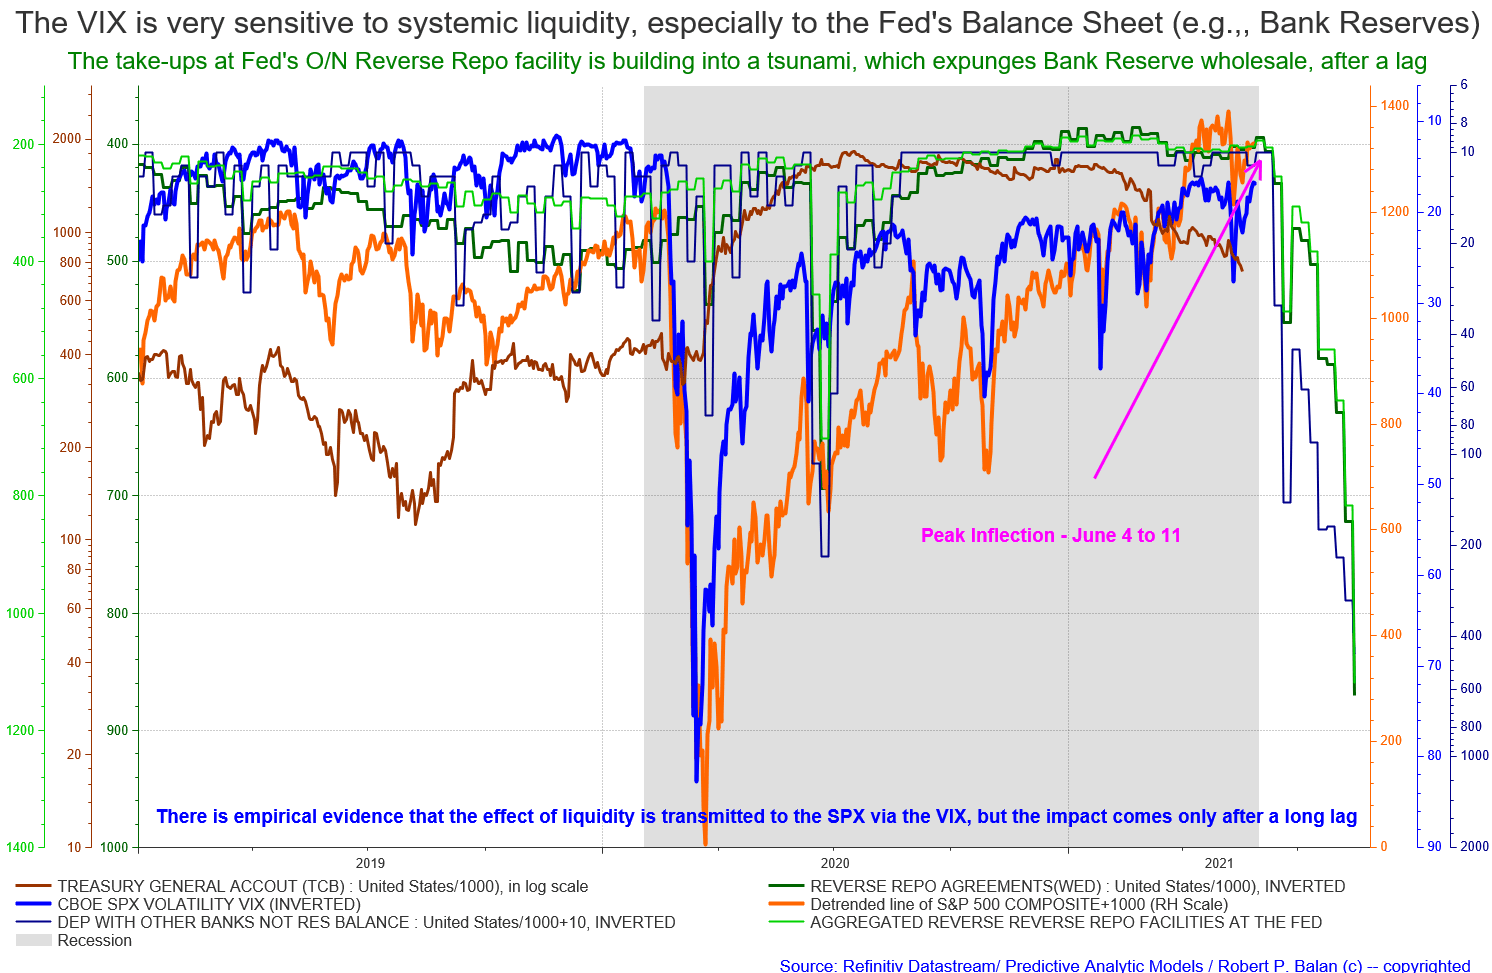
The implications of the Fed's Balance Sheet models' liquidity flows -- remain the same: sharply lower VIX going into the week of June 2 to 7 (optimal, interpolated trough thereafter is June 4), supporting the view of higher equities during the same period.
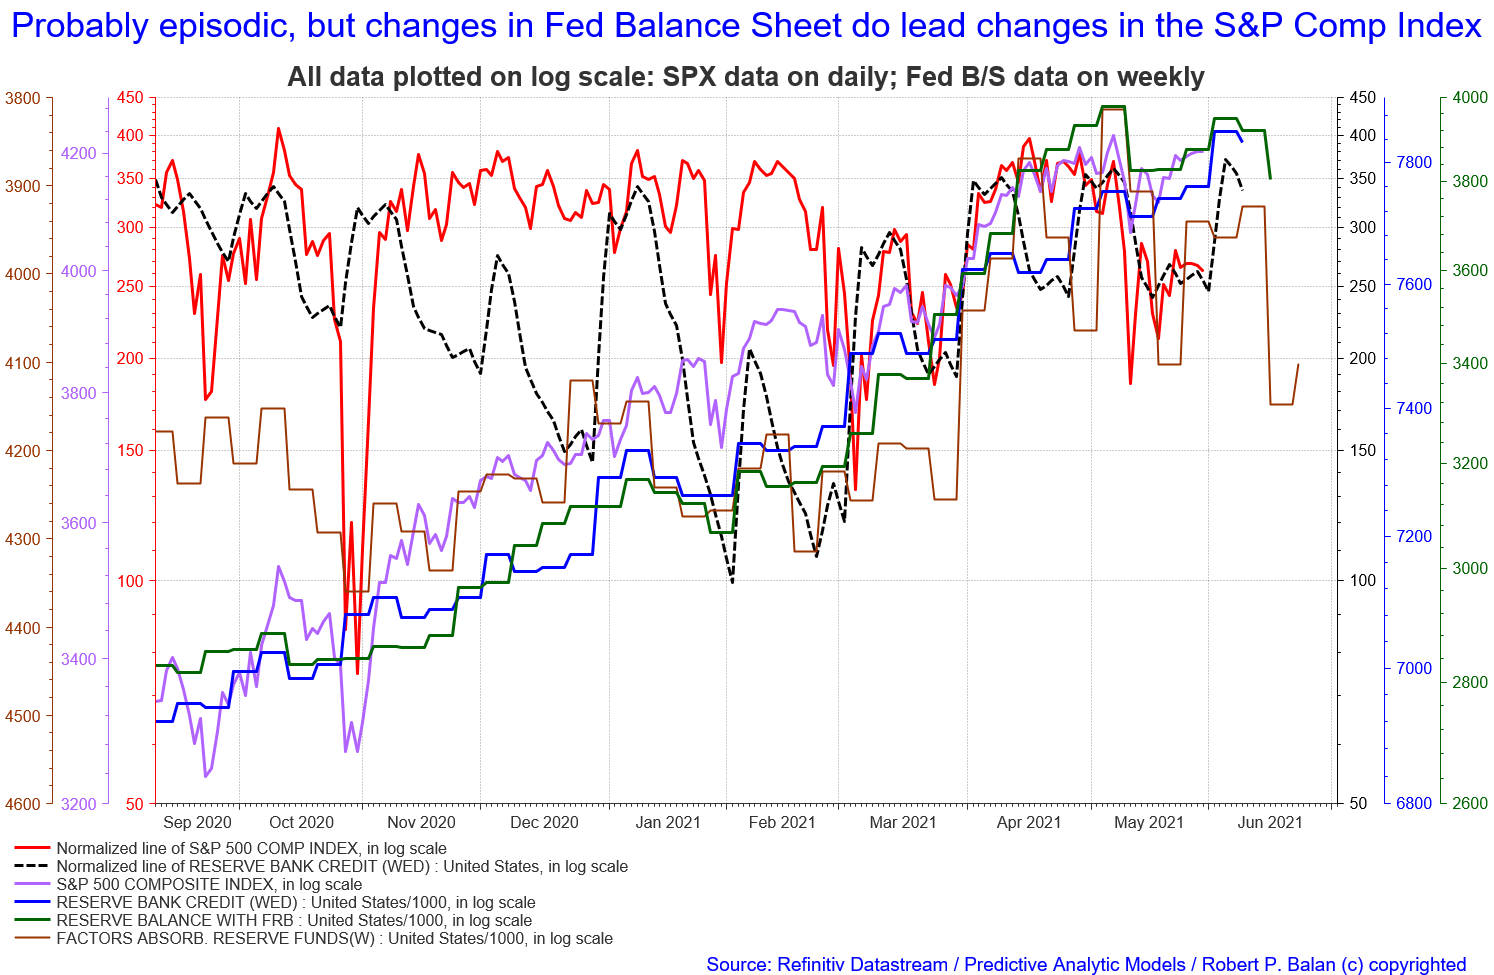
SPX rallying higher is what the model also calls for, going into the week of June 2 to 7 (optimal, interpolated top thereafter is June 4). No change in outlook, so far.
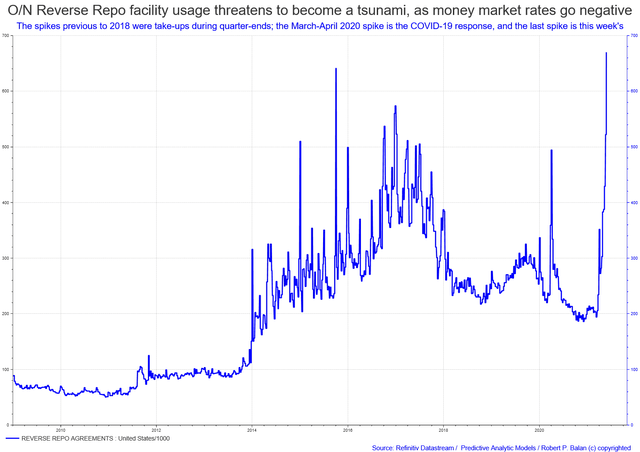
Meanwhile, a tsunami of take-ups at the O/N RRP facility continues to build, aggregated reverse repo flood rising even higher in foreseeable future. Not many say this is a "black swan" event, but the impact's long lag may be catching up soon. Be especially wary of June 4-11.

Comments
Log in or sign up to join the conversation.