
Palantir (PLTR) stock has suffered a big reversal, wiping out some of the gains made since June when it bottomed at $106.5. It dropped to $186.7, down by 12.75% from its highest point this year. Still, analysts are optimistic about the company, citing its strong fundamentals and revenue growth.
Palantir stock coincided with the tech sector sell-off
The ongoing PLTR stock sell-off has coincided with that of most software companies. Salesforce dropped to $241.4, down by 10% from its highest point in September. Other top software companies like Palo Alto Networks, Twilio, Okta, Fastly, and SentinelOne were among the top laggards.
One reason for the ongoing Palantir stock retreat is the upcoming midterm elections, where Democrats are set to win the House of Representatives and, potentially, the Senate.
Analysts predict that a win by Democrats will lead to some major investigations on companies that have helped the administration on key issues. Palantir will be targeted for its role in helping the administration in border issues. It is unclear whether these investigations will impact its revenue and profitability growth.
Analysts are bullish on PLTR stock
Still, on the positive side, analysts are highly bullish on PLTR stock, citing its strong revenue and profitability growth. On Thursday, Mizuho analysts boosted the target from $215 to $245. Two days before that, Baird analysts set the target price at $250, while Barclays initiated with a target of $265. Other analysts who have maintained a bullish outlook for the stock are from Goldman Sachs, Raymond James, and UBS.
Most of these analysts are citing the company’s revenue and profitability growth. The most recent results showed that Palantir’s business continued doing well in the second quarter, driven by corporate and government orders.
American companies are increasingly turning to Palantir’s solutions, with the revenue rising by 149%. Their remaining deal value jumped to $6.24 billion, with more firms embracing its AIP solution.
In total, Palantir’s revenue rose 93% YoY to $1.93 billion, while the adjusted income from operations rose to $1.19 billion. The management expects that this revenue growth will continue in the foreseeable future.
Its third-quarter revenue is expected to be between $2.16 billion and $2.164 billion, much higher than the $1.18 billion it made last year.
Palantir’s key valuation multiple, known as the Rule of 40, shows that it is highly undervalued. This multiple is calculated by adding a company’s revenue growth with its margins. In this case, adding the two gives PLTR a multiple of 155%, one of the highest in the US.
Traditional metrics, however, show that it is highly overvalued. It has a forward price-to-earnings ratio of 123, much higher than the sector median of 21.8. This multiple is much higher than other software companies like Microsoft, Salesforce, and Okta.
Palantir stock price analysis
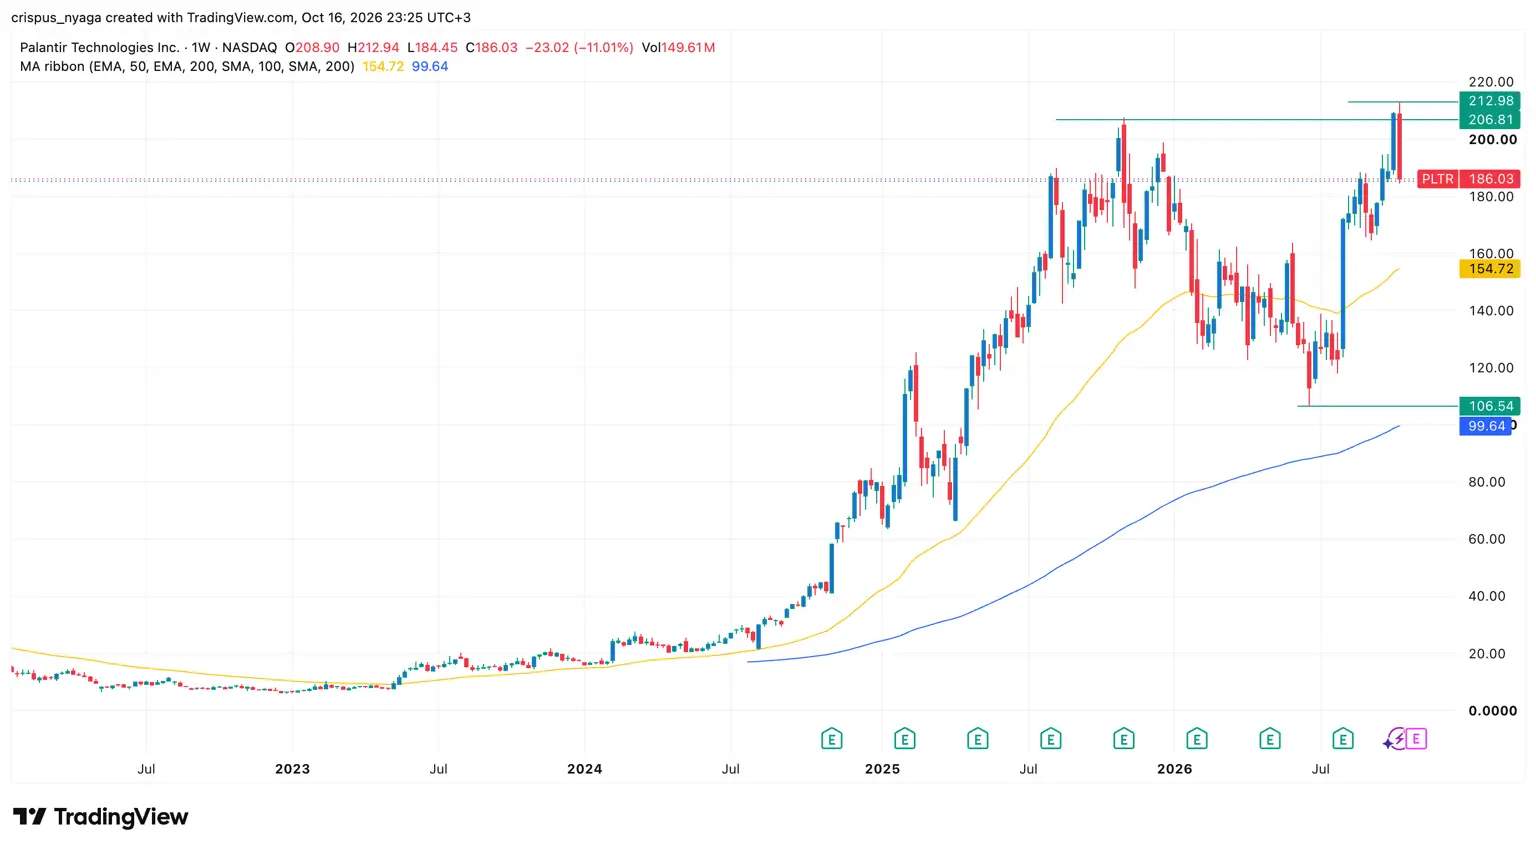
The weekly chart shows that the PLTR stock rebounded from $106 in June to a high of $212 in this month. Its highest point was notable because it coincided with the highest point in November last year. It has also formed a bearish engulfing pattern, where a big bearish candle covers a bullish candle fully.
Therefore, the stock will likely retreat further, potentially to $160, and then resume the upward trend. If this happens, the stock will likely jump to $250.
Comments
Log in or sign up to join the conversation.