
OKTA, Inc. (OKTA), the identity software security company, has significant out-of-the-money put option activity ahead of Q3 earnings in 2 weeks, on Dec. 1. But is this actually a contrarian bullish signal for OKTA? After all, management has already projected strong FCF growth and margins.
OKTA is up over 4.5% today, trading at $186.42 at midday. That's up from a recent trough at $168.69 on Nov. 6, and down from a peak of $232.19 a month ago on Oct. 9. But today's option activity may imply a higher price.
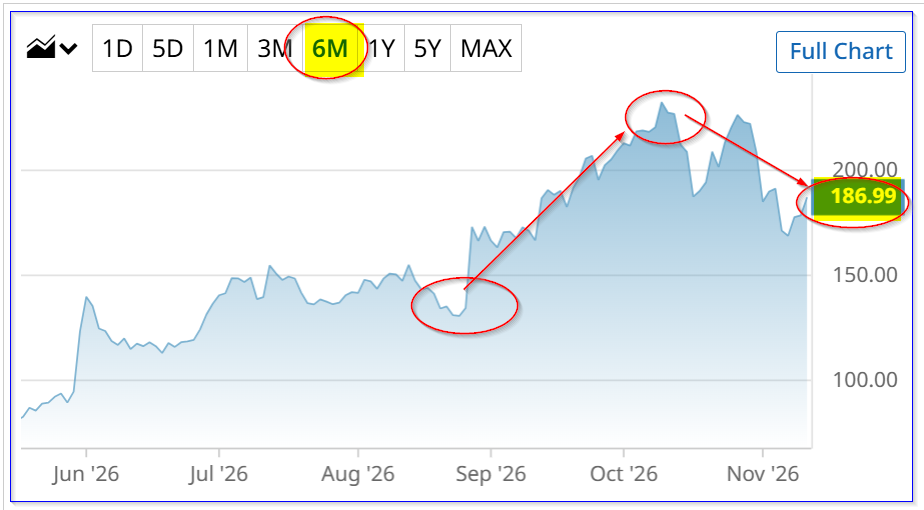
OKTA stock - last 6 months - Barchart - midday Nov. 11, 2026
After all, analysts have significantly higher price targets (PTs). For example, Yahoo! Finance shows an average PT of $214.72 from 44 analysts. That's over 15% above today's price. Barchart's mean survey PT is $213.27, or +14.4% higher.
So, why the huge put option activity today?
Unusual OKTA Put Option Activity
Today's Barchart Unusual Stock Options Activity Report shows 2,000 puts traded at the $150 strike price expiring in 100 days on Feb. 27, 2027. That's over 13.5 times the prior number of puts outstanding.
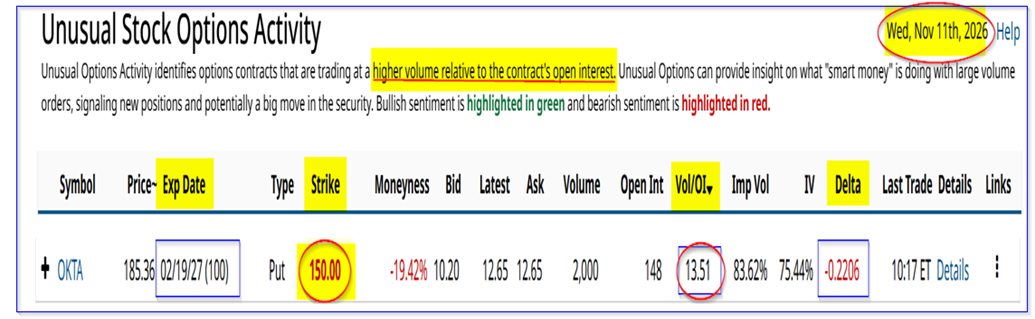
OKTA puts expiring Feb. 19, 2027 - Barchart Unusual Stock Options Activity Report - Nov. 11, 2026
Moreover, the strike price is deep out-of-the-money (OTM), i.e., over 19.5% below today's higher price. What's more, the premium is very high: $11.42 at the midpoint (at the time of the report).
That implies short-sellers initiated these put trades. That way, they collect an immediate yield of 7.613%, i.e., $11.42 / $150, (for just over 3 months).
And it also guarantees a significantly lower buy-in, even if OKTA drops 20% to $150 (i.e., the breakeven would be $138.58, or -25.6%.
The point is that this is a very bullish signal, a contrarian viewpoint, since it doesn't seem likely that OKTA will really drop 20-25% in the next 3 months.
After all, the delta ratio is -0.22, implying a 78% chance of success (i.e., that OKTA won't drop to $180).
Or could it? If OKTA's FCF comes in lower than expected, that could lower its prospects and valuation.
Strong FCF Prospects
OKTA is one of the very few companies that not only forecast its FCF figures but also its FCF margins. It has a high degree of confidence in its FCF since over 98% of its revenue is from annual subscriptions, and it has a high renewal rate.
As a result, last quarter management projected not only $175m to $185m in Q3 FCF, but also a FCF margin of 21% to 23%. That implies lower FCF than last year's 214 m FCF, and a lower margin than last year's 28%.
However, for the full year (ending Jan 31, 2027), management projects $910 to $930 million in FCF, for a 28% to 29% FCF margin. That is higher than the $875 million FCF last year, but the FCF margin would be lower (30%).
This could be why investors are buying puts today. However, let's look at these numbers more closely.
For example, analysts now project revenue for the year ending Jan. 2028 (i.e., 2027) will be $3.55 billion, or 10% higher. So, if its FCF margin stays at 29% (but still below last year's 30%), FCF could rise to $1.03 billion.
OKTA Valuation Prospects
That could push OKTA higher by Feb 17, 2027, the expiry date for these puts. For example, using a 2.5% FCF yield (well below its average 1.25% FCF yield), OKTA would be worth:
$1.03b FCF est. / 0.025 = $41.2 billion
That's 26% above its present market cap of $32.65 billion. In other words, the PT is 26% higher:
$186.42 x 1.26 = $234.89 PT
Just to be conservative, let's use a 3.0% FCF yield. That results in a valuation of $34.3 billion, or 5.1% higher (i.e., PT of $195.74).
In other words, OKTA could be worth between $195 and $235 next year, just using management's FCF margin guidance and analysts' revenue forecasts.
Summary and Conclusion
Here's how that works out for put option sellers today. Let's say the news is disappointing on Dec. 1 and OKTA drops 20%to $180. Put buyers will make money, but the short-sellers also have a lower breakeven point of $138.58 (see above).
In other words, given the stock's PT next year of between $195 and $235, say $215, the upside is very attractive:
$215 / $138.58 -1 = +55% expected return
Even if OKTA doesn't hit $180, the put short-sellers make a 3-month 7.613% yield, or 27.8% annualized (i.e., 365/100 x 7.613%). Either way, they have good prospects of making money.
That's why today's unusual put option activity is actually a contrarian bullish signal for OKTA investors.
Comments
Log in or sign up to join the conversation.