
Markets will scan the European Central Bank announcement on 29 October for any signs that French bond turmoil has triggered a dovish rethink. We don’t think it has, and expect the ECB to leave the door open for a December hike, which should shield rates and the euro from a major adjustment. As usual, we also look at three alternative scenarios to our baseline.
The ECB is expected to leave rates on hold this week at 2.5%
This is our market preview of October's European Central Bank meeting; you can find our macro preview here.
In September, the ECB effectively brushed aside rising bond market concerns with a hawkish rate hike. This week, a hold is widely expected. The key question is whether the latest turmoil in French and other European bonds is enough to trigger a dovish shift in the ECB’s message.
We don’t think we are there yet. But equally, we admit that a more dovish tone on further tightening would probably be the first line of defence against more bond volatility, before exploring any bond-buying measure.
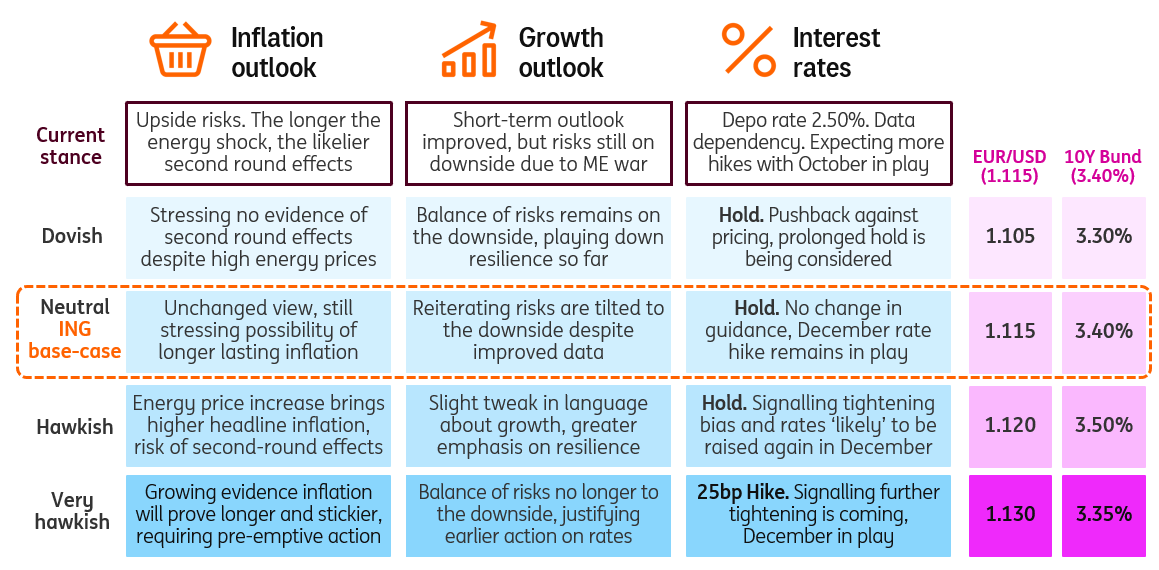
Four scenarios for October
As usual, we look at four scenarios for this meeting. As in previous instances, the market reaction will depend as much on the statement and press conference as on the now-customary tip to the media on Thursday afternoon. In September, the message was: “ECB officials expect more tightening, with October in play”.
A hike this week would, however, be a big surprise (close to zero chance priced in), as inflation has remained well-behaved, France has prompted a dovish repricing and President Christine Lagarde has sounded a bit less hawkish.
In a meeting without new projections, the wording around December will be crucial. We expect the door to remain open for a December move, with a broadly neutral and balanced message to markets. Signalling that a hike by year-end is “likely” would be a slightly hawkish surprise in our view, even if markets are pricing in 20bp.
Rates look for predictability amid fragile sentiment
Rates have started to deviate from their tight correlation with oil, but global factors remain an important driver. Risk sentiment is more fragile, and not just because of the French turmoil, but also because of renewed AI jitters. So whilst markets will listen carefully to Lagarde, we don’t expect this week’s meeting to trigger a major repricing. A stronger dedication to a December hike would nudge a hawkish repricing, but with more than 20bp already priced in, the reaction should be contained. Both the ECB and markets understand the outlook is shrouded in uncertainty, so any forward guidance will be weighed against that backdrop.
A bigger surprise to markets would be a 25bp hike, but this would not be taken lightly by investors, especially if December remains in play too. Without clear second-round inflation risks, an unexpected tightening of financial conditions while sentiment is fragile could trigger a broader risk-off move. Expect French government bond spreads to widen and equities to continue their drift lower. We might even see 10yr Bund yields fall on the decision, as growth concerns return.
EUR could do with some ECB protection
The euro has become less sensitive to the latest moves in French bond spreads, with undervaluation to short-term fair value still around 1-1.5%. Still, the common currency has been hurt not only by the build-up of a fiscal risk premium, but also by the repricing lower in ECB rate expectations because of the French turmoil.
This week’s meeting is unlikely to have the same FX impact as September’s, but currency investors will be looking for any cracks in the ECB’s tightening bias as a sign that bond market concerns could prompt a dovish rethink.
That probably leaves the balance of risks on the downside for the euro. Still, our baseline is for no pushback against lingering hawkish bets, leaving the euro broadly stable after Thursday.
If the ECB does continue to fuel bets on a December hike, we think the bar is higher for French spreads to deliver another big blow to the euro. Our preference remains for EUR/USD to return to the 1.120-1.130 area over the coming weeks.
Comments
Log in or sign up to join the conversation.