
Norges Bank faces a finely balanced decision, but we expect a final 25bp hike to 4.50% on Thursday. While core inflation has undershot projections, headline inflation remains above forecast and domestic conditions are still firm. Markets already price in most of a hike, reducing the cost of tightening. EUR/NOK may face more pressure before any recovery
Mixed inflation signals
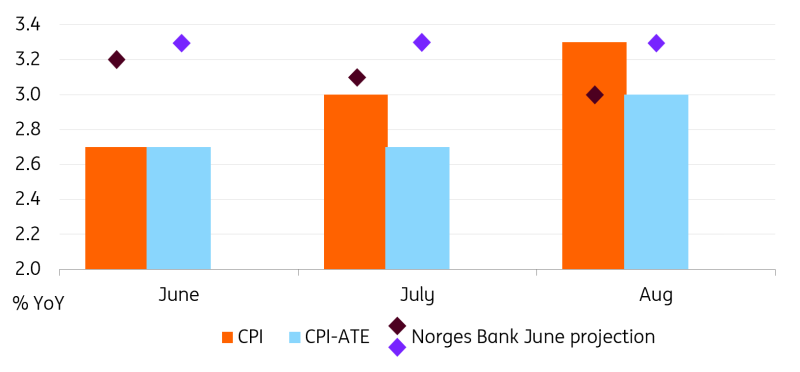
Consensus is evenly split on whether Norges Bank will hike interest rates again at the 24 September meeting. We expect a 25bp hike to 4.50%, but understand why this is a close call. Inflation has undershot Norges Bank’s expectations over the summer, with underlying CPI (CPI-ATE) easing to 2.7% in June and July before rebounding to 3.0% in August, still below the central bank’s 3.3% projections for all three months.
By contrast, headline inflation is now 0.3pp above Norges Bank’s projections, at 3.3%. The June rate path had already pointed to a likely hike to 4.50% in September, with rates then expected to stay broadly unchanged through mid-2027.
Higher headline, lower underlying inflation
Source: ING, Norges Bank, Macrobond
Overall backdrop still favours tightening
While price dynamics were more benign over the summer, we think Norges Bank's inflation concerns remain. Higher energy prices should continue to support headline CPI and could still feed through more broadly. Economic conditions remain solid, according to Norges Bank's regional survey, with wage growth expected to stay elevated at 4.0% in 2027.
That’s a backdrop that can tilt the balance towards insurance tightening even if data has not proven particularly worrying. With the Federal Reserve and European Central Bank both signalling another hike by the end of the year, the external pressure is also on the hawkish side.
One final reason why we think Norges Bank will hike is that markets are pricing in 16bp for this meeting. The cost of disappointing expectations may outweigh that of tightening too early in a rather healthy economy. Anyway, should they opt for a hold, we expect strong hints of another hike by year-end.
Extra support for NOK, but oil remains key
Market pricing beyond September is nowhere as aggressive as for the Fed or the ECB, with 38bp priced in total for January and a flat curve for the remainder of 2027. As a result, Norges Bank faces little pressure to lift its rate projections materially. We nonetheless expect updated forecasts to show some probability of a further fourth-quarter rate hike, while the statement should continue to leave the door open to additional tightening. Our baseline is that this September move is the last one for this cycle.
A hike should support NOK’s recent strength. We maintain a near-term EUR/NOK target of 10.70, with potential to reach 10.60. That said, our end-4Q target of 10.60 is beginning to look somewhat too bearish. We now expect another ECB hike in December, and our commodities team’s baseline scenario is for a sharp fall in oil prices from 4Q: a backdrop more consistent with EUR/NOK returning to 11.00.
Comments
Log in or sign up to join the conversation.