
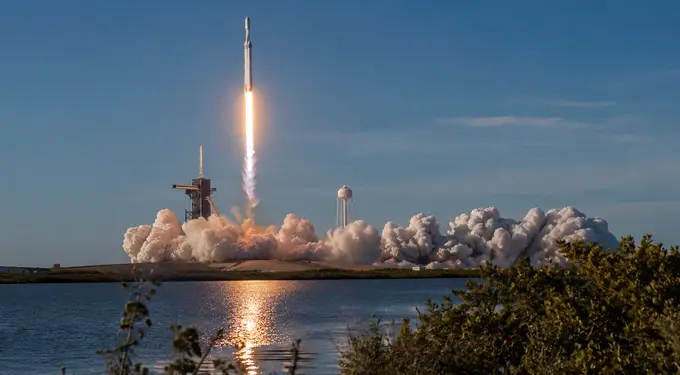
SpaceX SPCX earnings call last night offered investors plenty to digest, but one omission stood out to Bernstein analyst Doug Harned: orbital data centers.
Speaking this morning with CNBC, Harned said the “silence” reflected competing priorities rather than fading interest in computing infrastructure in space.
His view suggests investors should distinguish between the business generating excitement today and the technology underpinning longer-term expectations.
The immediate opportunity is on Earth.
Whether that makes the missing orbital update reassuring for those invested in SPCX shares depends on what they believe they’re paying for.
SpaceX’s terrestrial opportunity is taking center stage
According to the Bernstein expert, SPCX believes it can continue monetizing terrestrial computing capacity at $30 – $50 per watt, potentially securing even higher pricing.
He linked those economics to shorter-term agreements involving AI giants Anthropic and Google, explaining why management considers further ground-based construction attractive.
The expansion ambitions are substantial. On the October 20th earnings call, billionaire Elon Musk expressed confidence in adding as much as 10 gigawatts of compute during 2027, beyond roughly 2.5 – 3 gigawatts expected online by this year’s end.
Those figures represent management targets rather than completed installations.
For shareholders, the distinction matters: demand for terrestrial infrastructure gives SpaceX stock a commercial opportunity while orbital deployment remains ahead.
But pricing per watt alone cannot establish profitability.
Construction costs, customer utilization, contract duration, and equipment replacement all influence how much of that opportunity reaches investors.
What SPCX’s orbital ambitions mean for its valuation
Harned said initial launches for orbital data centers are planned for late 2027, while stressing that Bernstein expects a slower buildout.
He believes the concept can succeed, but his caution highlights the difference between launching initial infrastructure and operating a commercially significant network.
The valuation implication is “straightforward” – distant earnings are worth less today when their arrival is delayed, assuming other factors remain unchanged.
Plus, investors must account for the possibility that deployment takes longer or costs more than expected.
An orbital business could potentially strengthen SpaceX’s competitive position by connecting its launch capabilities with computing infrastructure.
Success would offer a growth opportunity that terrestrial computing rivals could struggle to replicate.
But at roughly $2 trillion, SPCX stock already carries “substantial expectations” for future growth.
And its terrestrial expansion offers a plausible route to supporting that valuation, provided capacity translates into sustained earnings and cash flow.
However, without commercial progress in orbit, more of the burden falls on maintaining attractive compute pricing while financing enormous construction costs.
In short, the omission alone doesn’t undermine the investment case, but it does leave a major justification for the premium unproven.
How Wall Street recommends playing SpaceX stock
Investors could still take heart in the fact that Wall Street remains bullish on SpaceX shares for the next 12 months.
The consensus rating on SPCX sits at Overweight, according to The Wall Street Journal, with the mean price target of about $245 indicating potential upside of roughly 50% from here.
Comments
Log in or sign up to join the conversation.