
Netflix, Inc. (NFLX) generated strong free cash flow (FCF) in Q3 in its Oct. 20 earnings release. However, it guided to lower 2026 FCF, reducing it to $12 billion from $12.5 billion. Despite this, Q3 FCF margin stayed high at 22.9%, and revenue is forecast to rise next year.
Nevertheless, analysts lowered their price targets, and NFLX dropped. Is it too cheap?
NFLX closed Thursday, Oct. 22, at $67.05, well below its price a week ago ($72.61 on Oct. 15). It dipped to $65.04 on Wednesday, Oct. 21.
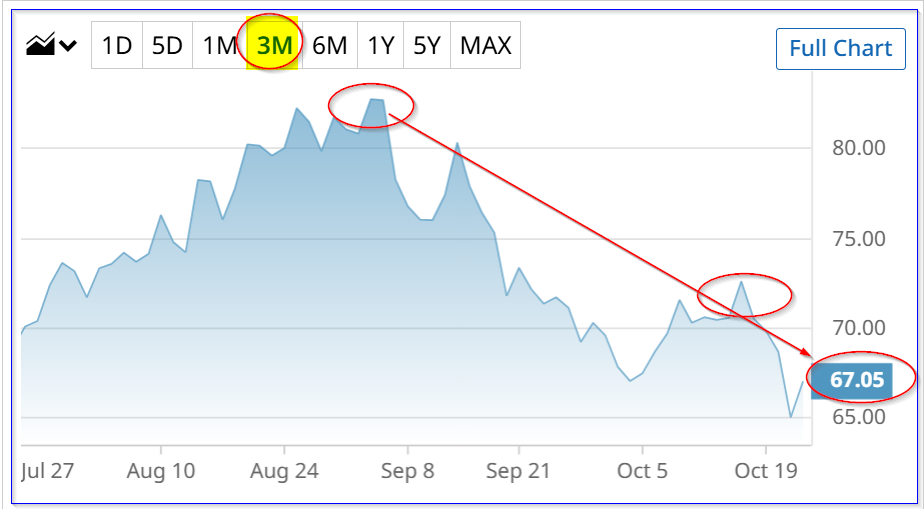
NFLX - last 3 months - Barchart - Oct. 22, 2026
Has it hit a bottom here? After all, the company is still generating very strong FCF. Let's look at that.
Strong FCF and FCF Margins, Despite Lower Guidance
The Netflix Q3 shareholder letter shows its FCF progression over the past 5 quarters (see below). I have added the FCF margins (i.e., FCF/revenue).
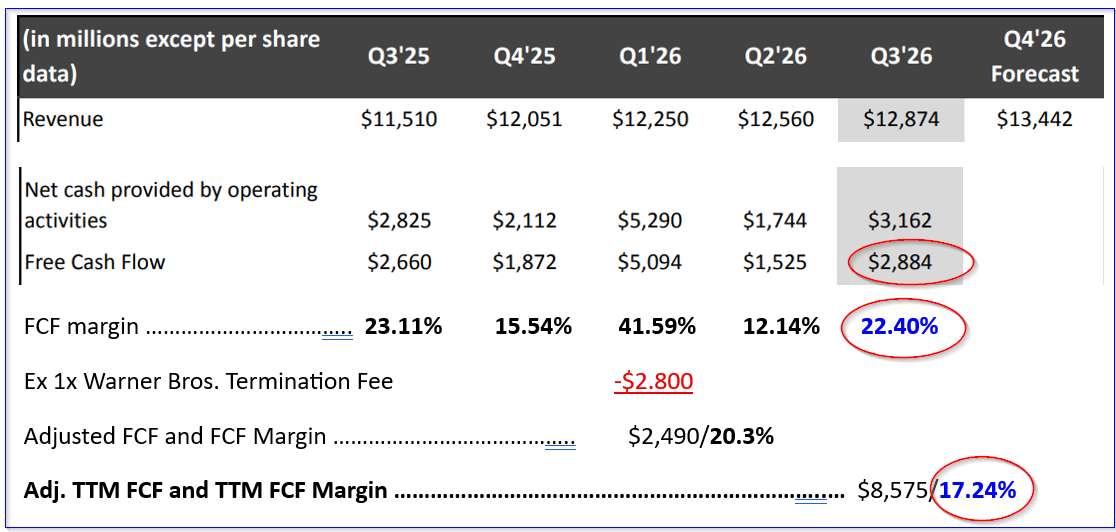
Netflix Q3 shareholder letter and Hake analysis
The point is that its Q3 FCF margin rose significantly. This is what my recent Barchart article discussed ("Huge, Unusual Netflix Put Options Activity Ahead of Earnings Release Later Today, Oct. 20.").
The table shows adjusted FCF and FCF over the trailing 12 months (TTM). In Q3, the FCF margin rose from 12.1% in Q2 and 20.3% (adj. basis) to 22.4%.
That adjustment removes the $2.8 billion one-time payment Netflix received from Skydance for walking away from the Warner Bros. takeover.
As a result, the adj. TTM margin is now 17.24%, close to last quarter (17.3%), as I explained in my Oct. 20 Barchart article.
Moreover, I used an 18.3% FCF margin to project FCF next year. Its Q3 margin (22.4%) is much higher than 18.3%. So, if management can maintain this margin, NFLX could be undervalued.
Forecasting Netflix's FCF and Valuation
Management said its 2026 FCF would now be $12 billion, down from $12.5 billion it previously forecasted. That is due to a one-time real estate deal. That could be one reason why NFLX took a dip.
But it shouldn't affect FCF projections for next year. For example, the 2026 FCF margin should be about 23.5% (i.e., $12 billion / $51.13 billion). Keep in mind that this includes the $2.8 billion fee.
However, using analysts' 2027 revenue forecast of $56.65 billion and a 19% FCF margin (i.e., less than halfway between the 17.24% TTM margin and the Q3 22.4% margin), FCF could reach $10.76 billion:
$56.65b 2028 revenue x 19% FCF margin est. = $10.76 billion FCF
Using a 3.0% FCF yield, NFLX could be worth $358.67 billion (i.e., $10.76b/0.03). That is 28.5% above its present market cap of $279.19 billion.
So, the price target (PT) is 28.4% higher:
$67.05 x 1.285 = $86.16 per share PT
Yahoo! Finance's survey PT is $85.07, and Barchart's mean survey PT is $88.38. These are both now lower than on Oct. 20 (see my article). That could also be why the stock is lower.
Summary and Conclusion
The bottom line is that Netflix is still generating strong free cash flow (FCF), and people are still viewing Netflix, watching its ads, and subscribing.
Moreover, next year, analysts project higher revenue, which, if margins rise, as I project, will lead to higher FCF. As a result, NFLX stock still looks cheap here, despite all the negative sentiment on the stock.
I will come back to this story in a week or two to show how an investor might play this in the options market.
Comments
Log in or sign up to join the conversation.