
Semiconductor behemoths Micron Technology (MU - Free Report) and NVIDIA Corporation (NVDA - Free Report) benefited from the artificial intelligence (AI) boom. With strong growth and an upbeat outlook, both seem poised to capitalize on rising AI infrastructure demand. But which stock offers a better buying opportunity? Let’s explore –
Micron’s AI Growth and Expanding Margins Boost Outlook
As AI infrastructure needs high-performance memory, demand for Micron’s cutting-edge high-bandwidth memory (“HBM”) chips has surged. This momentum helped the company post revenues of $54.23 billion in the fiscal fourth quarter of 2026, up sharply from $11.32 billion a year ago, according to its Sept. 30 press release.
For fiscal 2026, Micron’s revenues were $133.19 billion, up from $37.38 billion in fiscal 2025. Its guidance remains even more encouraging, with the company expecting revenues of $61.5 billion, plus or minus $1.5 billion, in the first quarter of fiscal 2027. The data center business continues to be Micron’s key growth engine, benefiting from an increase in AI-related demand.
Additionally, Micron’s profit margins are reaching exceptional levels. Its non-GAAP gross margin increased from 84.9% in the fiscal third quarter of 2026 to 87% in the fiscal fourth quarter, supported by higher selling prices, a favorable product mix, and operating leverage. Further, the company’s management expects its Strategic Customer Agreements to improve earnings visibility.
NVIDIA’s AI Demand Fuels Revenue Growth and Strong Profitability
According to NVIDIA’s Aug. 26 press release, the company’s revenues climbed 106% year over year and 18% sequentially to $96 billion in the fiscal second quarter of 2027. Its Data Center segment remained the primary growth driver, with revenues surging 117% year over year to $89 billion.
Going forward, NVIDIA expects revenues of $108 billion, plus or minus 2%, in the fiscal third quarter of 2027, signaling further sequential growth. The company also expects profitability to remain strong as its Vera Rubin platform has entered the full production stage, while NVIDIA remains well-positioned to capitalize on the next wave of AI infrastructure demand.
By the way, NVIDIA’s gross margin rose to 75% in the fiscal second quarter of 2027 from 72.4% a year earlier, while both GAAP and non-GAAP net income increased. NVIDIA’s GAAP operating income more than doubled year over year, implying strong operating leverage.
Micron or NVIDIA: Which AI Stock to Buy After Earnings
Both Micron and NVIDIA’s recent strong revenue growth, expanding margins, and upbeat guidance could boost both stocks. However, U.S. chip export restrictions to China and stiff competition could limit NVIDIA’s further growth, while Micron’s evolution from a highly cyclical memory stock to a vital supplier of AI infrastructure could drive sustained growth.
Moreover, NVIDIA’s debt-to-equity ratio of 14.1% exceeds Micron’s 3.3%, indicating greater financial leverage and potentially greater downside risk during economic downturns.
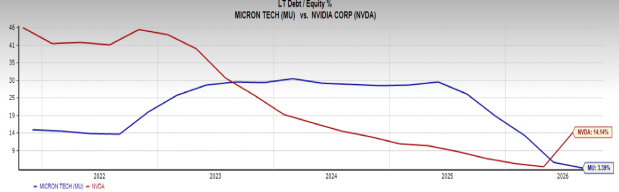
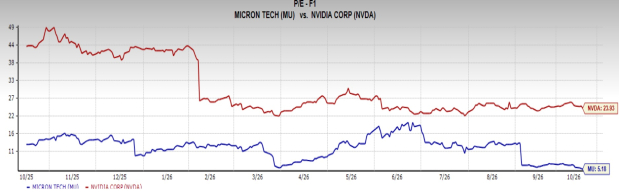
Therefore, Micron’s evolving role in AI infrastructure and lower financial leverage make it a more compelling buy than NVIDIA. Additionally, Micron appears more attractively valued than NVIDIA. Per the price/earnings ratio, MU trades at 5.18 forward earnings compared with NVDA’s forward earnings multiple of 23.93.
Micron currently has a Zacks Rank #1 (Strong Buy).
Comments
Log in or sign up to join the conversation.