

This META stock prediction starts with one product. Muse, Meta's personal AI agent, went from launch to the top of the US App Store in under two weeks, and the market answered with the stock's best month in 13 years. The rally has left META overbought, so the idea below waits for a pullback to 700 USD before it buys, with a target at 900 USD.
Trade Idea Parameters
Below are the specific parameters for the Meta Platforms trade idea.
Parameter | Value |
|---|---|
Instrument | Meta Platforms Inc (NASDAQ: META) |
Ticker in MobileTrader / MT5 | META |
Idea Date | September 22, 2026 |
Time Horizon | 3 months |
Direction | ↑ Buy (Long) |
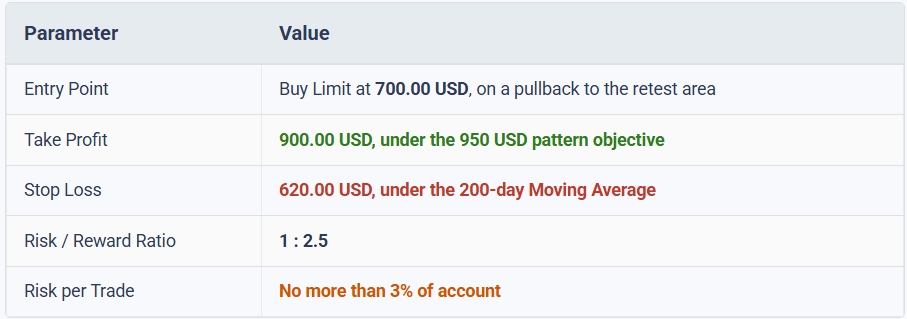
Entry Level (trigger) | 700.00 USD, Buy Limit |
900.00 USD | |
620.00 USD | |
Risk per Trade | No more than 3% of account · Medium risk |
Muse Becomes the New Driver Behind META Stock
META shares got a strong push after the launch of Muse, the company's new AI agent. On 21 September the stock rose 11% in a single session, its largest daily gain since April 2025. Over September it added about 30%, the best month in 13 years. That one session added 192 billion USD to the market value of Meta Platforms.
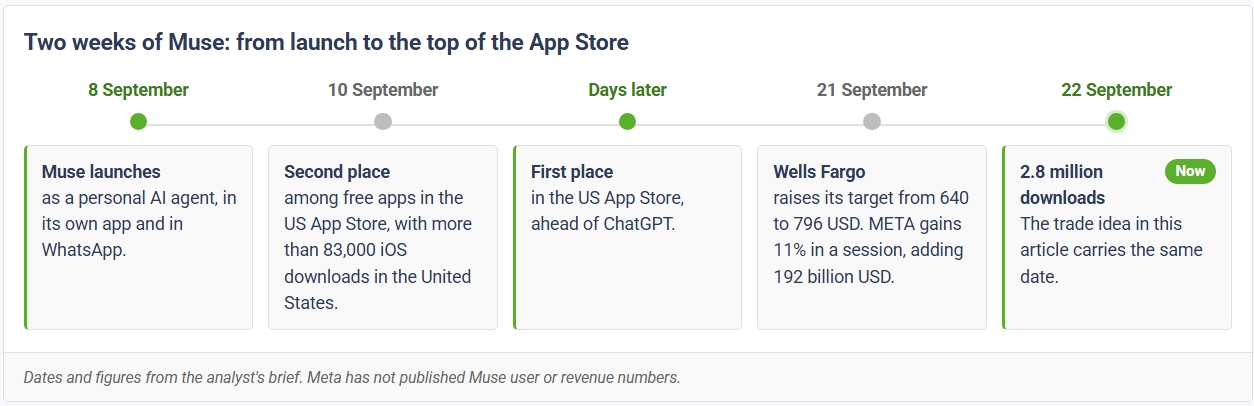
The immediate reason is Muse, Meta's personal AI agent, launched on 8 September. Two days later the app was second among free apps in the US App Store, with more than 83,000 iOS downloads in the United States. Muse then took first place, ahead of ChatGPT. By 22 September it had reached 2.8 million downloads.
The start also began to move analyst forecasts. Wells Fargo raised its target price for META from 640 to 796 USD and kept its Overweight rating, pointing at the strength of the Muse launch and better prospects for earning money from Meta's AI products. That revision was one of the main triggers behind the 21 September move, helped by Muse reaching first place in the US App Store.
What Muse Is and How It Works
Muse is Meta's personal AI agent. What separates it from an ordinary chatbot is that it can carry out actions on the user's behalf. It can:
send emails
fill in forms
book travel
make appointments
buy things
work with the calendar and other services
Muse is available through its own app and through WhatsApp, which gives Meta several channels to scale the service quickly. The company's own ecosystem is the bigger advantage, with billions of people on Facebook, Instagram and WhatsApp. If Meta can build Muse into those platforms, the agent reaches that user base and could become a new source of revenue through subscriptions and commercial services.
How Meta Platforms Could Earn Money from Muse
The central problem in the Meta Platforms investment case in 2026 is the size of its AI spending. The company expects capital expenditure of 130 to 145 billion USD for the full year. At the start of the year that guidance was 115 to 135 billion USD.
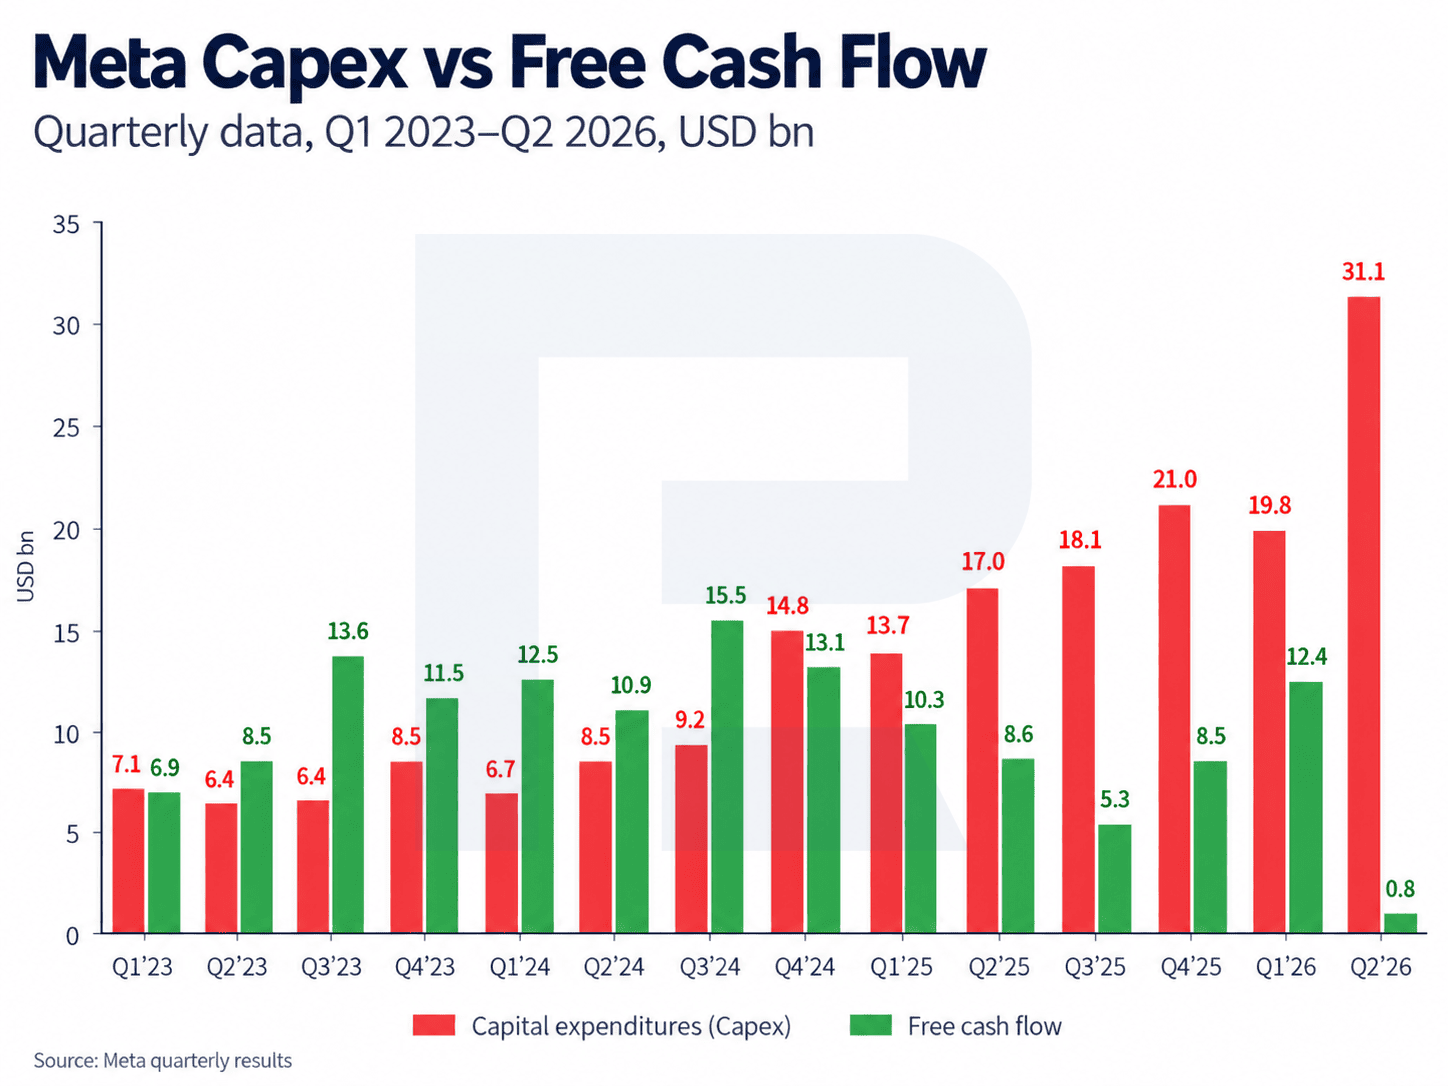
Meta Platforms capital expenditure against free cash flow, Q1 2023 to Q2 2026. Source: Meta quarterly results. Past results do not guarantee future performance.
The money goes into data centres, accelerators and Meta's own models. For a long time it stayed unclear how that spending would turn into extra profit, and the chart shows the cost of it: capital expenditure reached 31.1 billion USD in the second quarter of 2026 while free cash flow fell to 0.8 billion USD.
Muse gives the first clearer route to revenue. Meta can charge for AI in several ways at once:
paid versions of Muse
corporate access to its AI models
the agent built into WhatsApp, Instagram and Facebook
new commercial services
more user activity inside the Meta ecosystem
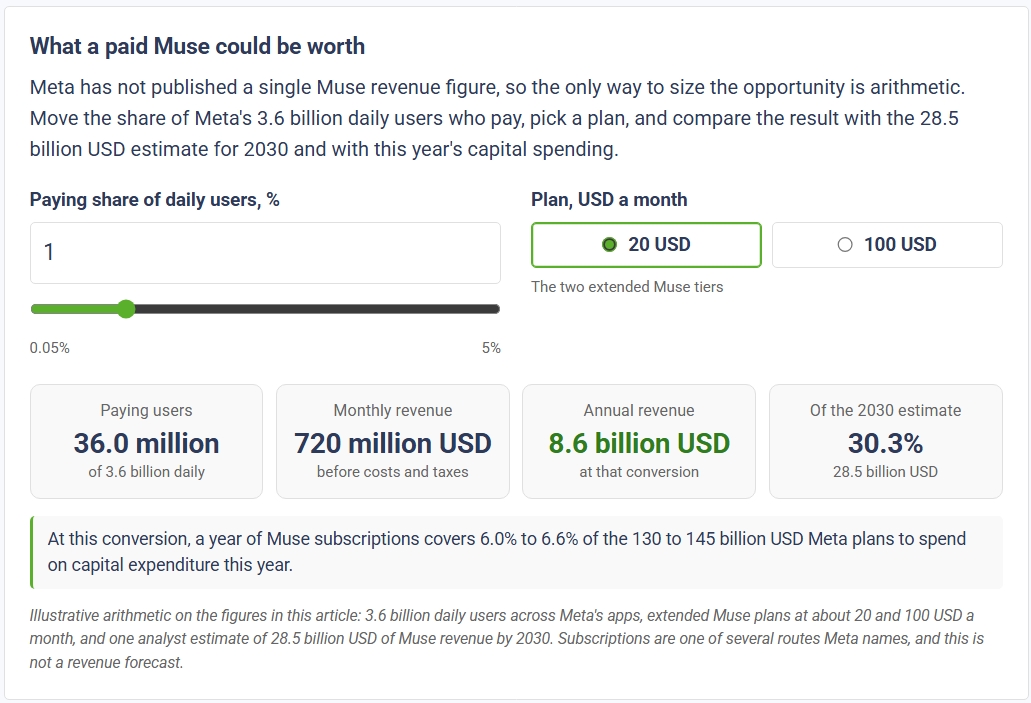
The subscription model matters most. Basic features are free, while the extended plans cost about 20 and 100 USD a month. Even a small share of Meta's audience converting to paid users would create a visible new business.
Some analysts are starting to price that in. One published estimate puts potential Muse revenue at around 28.5 billion USD by 2030.
What Muse Changes in the Meta Investment Case
For anyone analysing META stock, the change is that the market now has its first measurable signs of demand for a new Meta AI product. Until this, the investment case was built mostly around the scale of infrastructure spending, and the return on it could only be guessed at. The core business is already growing: revenue is up 28%, ad impressions 14%, ad prices 12%, and more than 3.6 billion people use the apps every day. A separate AI business with subscriptions, a corporate API and new commercial services could now sit on top of that.
Muse has no visible effect on Meta's financial results yet. The share price move after the launch mostly reflects expectations of revenue to come.
A better META stock prediction from here needs confirmation: a rising number of paying users, growing Muse revenue, and a visible contribution from the service to the company's results.
The Settlement Takes Legal Pressure off META
A second support under the stock is the settlement of a major dispute with US state attorneys general. Meta agreed to settle one of the largest legal cases of recent years, over the effect of Facebook and Instagram on teenagers. The agreement with 52 attorneys general provides for payments of about 18 billion USD over 10 years and additional limits for underage users.
The main terms:
Facebook and Instagram use by teenagers capped at two hours a day.
The apps blocked overnight, from midnight to 6 am, without parental permission.
Notifications limited during school hours.
Payments to the states and other parties spread over 10 years.
For META this removes a large legal risk and makes future costs more predictable.
META Analyst Ratings
As of September 2026, Barchart analyst ratings for META are positive. Of the 54 analysts tracked, 47 rate the stock a Buy and the other 7 a Hold. There are no Sell ratings.
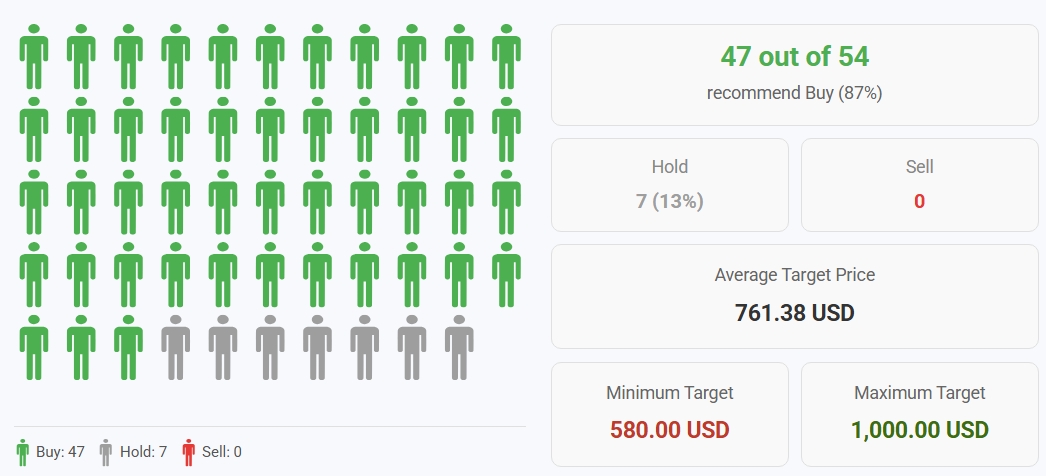
The average target price is 761.38 USD, the highest forecast is 1,000 USD and the lowest is 580 USD. That spread shows how differently analysts see the scale of further growth, while every published rating says Buy or Hold.
Worth noting for this idea: the 900 USD target below comes from the chart. It sits 18% above the analyst average and below the most optimistic forecast on the street.
META Technical Analysis and Stock Prediction
At the time of writing, META shares trade close to 737 USD.
On the news of the settlement and the Muse launch, META broke above its 200-period Moving Average and held there, which points to an uptrend forming. Since the start of September the stock has gained more than 30% with almost no pullbacks, and 11% of that came on 21 September alone. The Stochastic oscillator has moved into overbought territory, a sign of a short-term overheated market and a high chance of a technical pullback.
A triangle pattern completed on the chart at the same time. The break above its upper boundary is a strong bullish signal. Measured by the height of the figure, the classic projection for that pattern points to about 950 USD.
Given how overbought the stock is, the most likely near-term path is a retest of the broken upper boundary around 690 USD. A move like that would take some heat out of the rally and test whether the old resistance now works as support. If 690 USD holds, that area becomes a more attractive entry before any continuation toward 950 USD.
The trade idea for META is therefore a Buy Limit order at 700 USD, placed just above the expected touch so the order fills on the retest. The stop-loss goes under the 200-period Moving Average, which the chart reads at 625.11, at 620 USD. The take-profit sits below the pattern's measured objective, at 900 USD, to raise the chance of banking the move before the theoretical maximum.
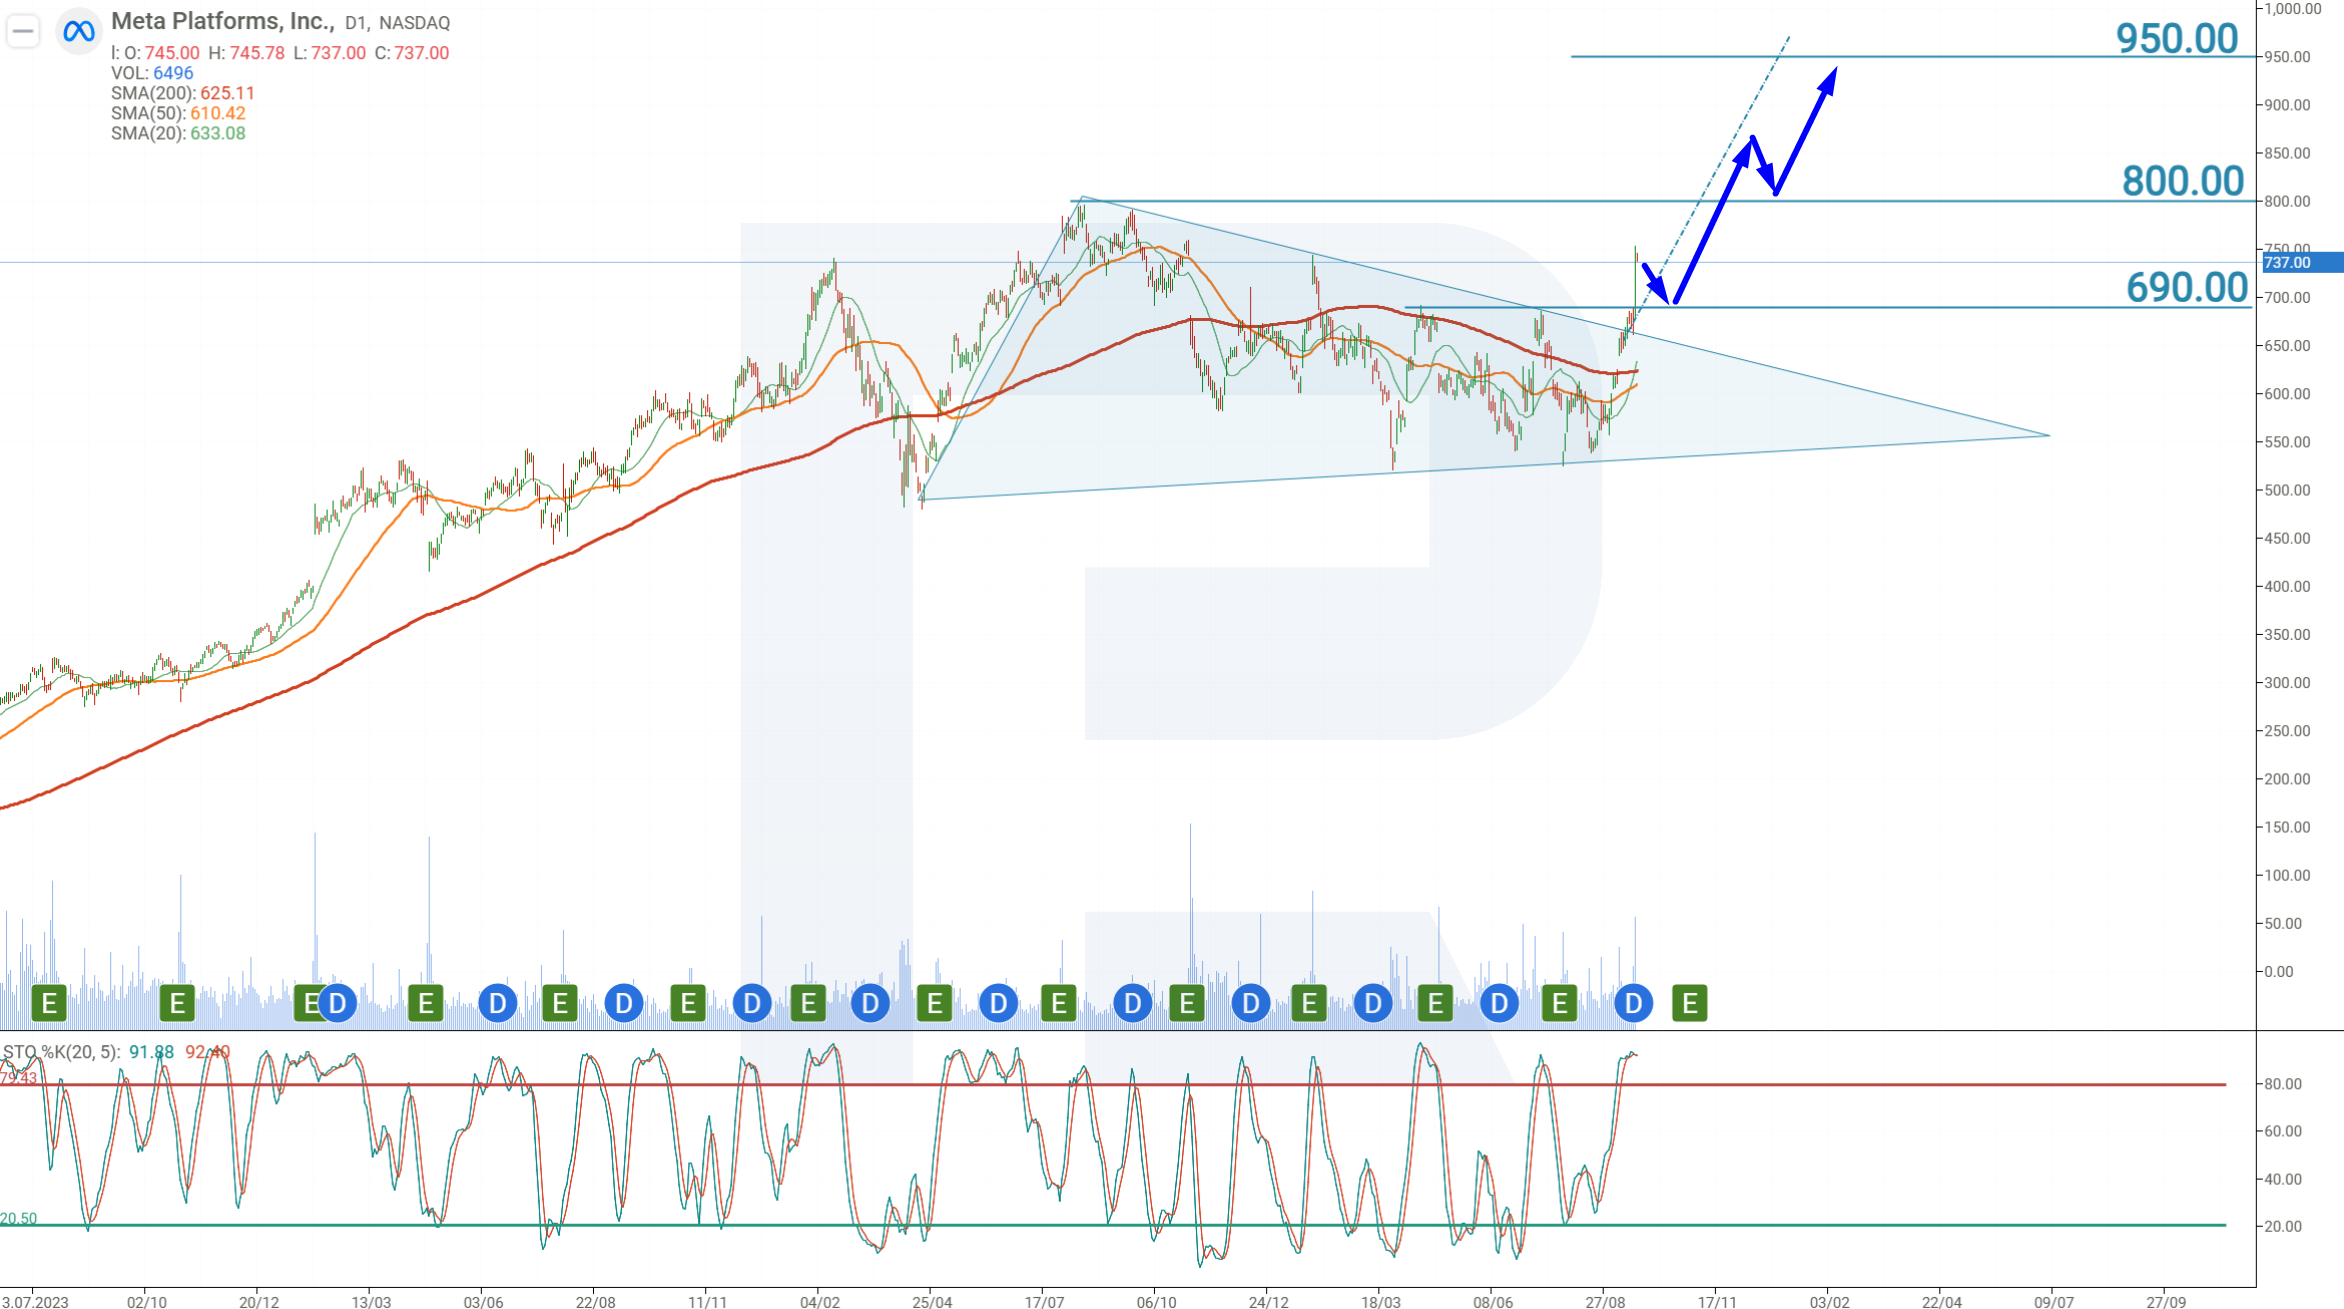
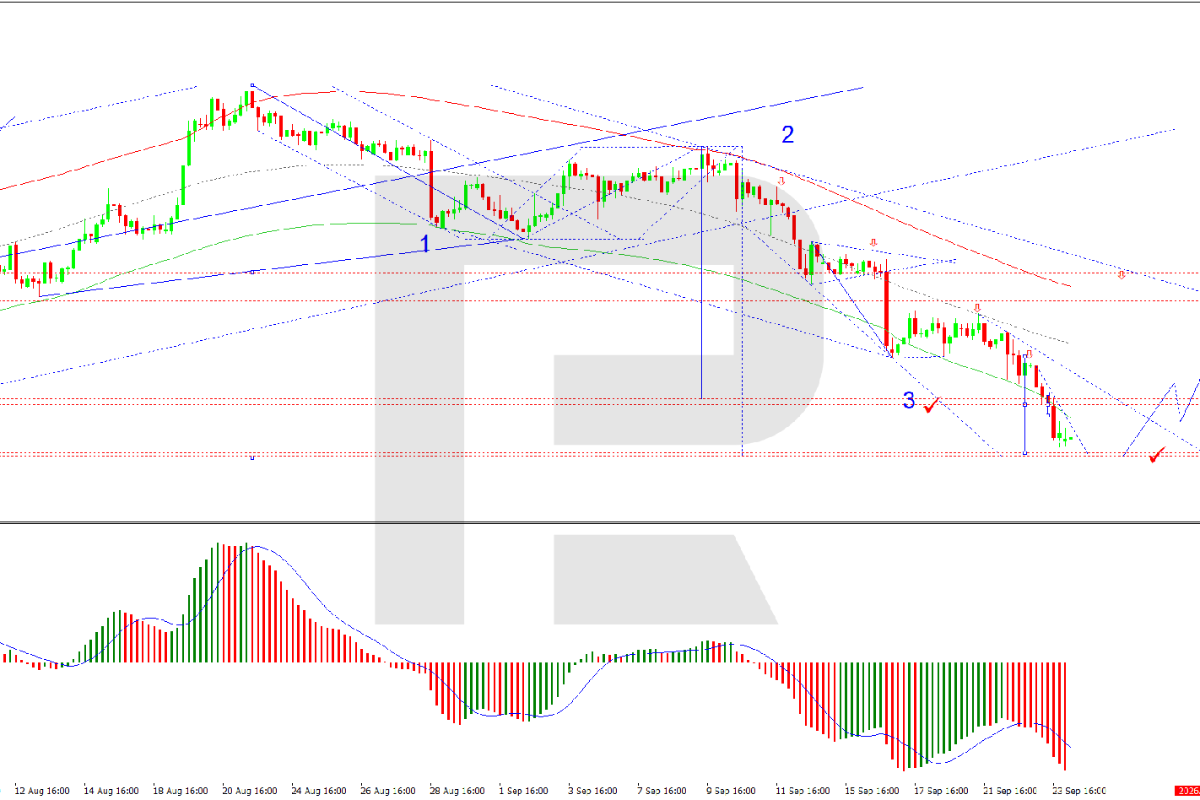
Meta Platforms Inc (META) stock technical analysis and forecast, daily chart. Past results do not guarantee future performance.
Price broke above the 200-period Moving Average and held there, which points to an uptrend forming.
Stochastic is in overbought territory, which shows the stock is overheated in the short term and raises the chance of a pullback before any further rise.
A Buy Limit order is the better option here, because the overbought reading makes an entry at the current price less attractive.
The triangle points to 950 USD for META if the classic scenario after an upper-boundary break plays out.
Position management rule
Once the price has covered 70% of the distance to the target, at 840 USD, the stop-loss moves to the entry level at 700 USD. From there it trails the price at a distance of 10% below it. Management continues until the position closes at the take-profit or the stop-loss, whichever is reached first.
Sample Trading Strategy for META Shares
Below is a sample trading strategy for META shares. This example is for educational purposes only and does not constitute investment advice. Investors should assess their own risk tolerance independently.
Position Size Calculator for META Shares
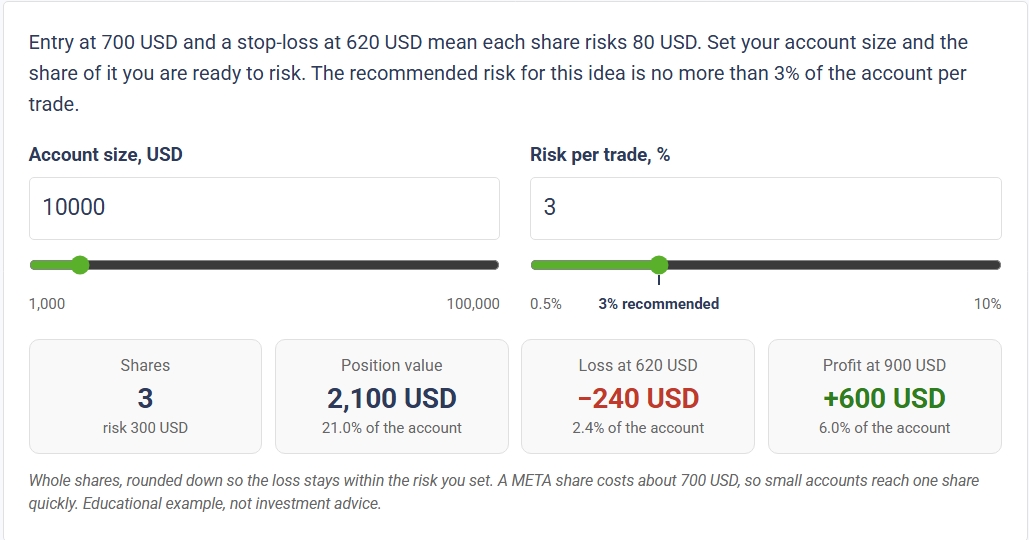
A risk/reward ratio of 1:2.5 means the potential gain is two and a half times the risk taken on. Keep in mind that markets are volatile: META shares can move both for and against an open position.
When This Idea Stops Being Valid
Three conditions end it.
The pullback never comes. META trades near 737 USD, so the Buy Limit at 700 USD needs a fall of about 5% to fill. If the stock keeps rising without that pullback, the order stays unfilled and the idea expires at the end of the three-month horizon, in late December 2026.
The price closes below 620 USD before the order fills. That would put META back under its 200-day Moving Average and inside the triangle it has just left, so the setup the entry is built on no longer exists. The pending order is cancelled.
The stop-loss is hit after entry. Once the position is open, a fall to 620 USD closes it with a loss of about 11% of the position value, and the case for a rise to 900 USD no longer holds.
One more condition sits outside the chart. If Muse downloads stall, or Meta reports another quarter of heavy spending with no sign of AI revenue, the story behind the rally weakens even while the price holds above 690 USD.
What Has to Go Right for META
Muse started fast, and the investment case still carries several real risks:
Muse is small next to the Meta ecosystem. Millions of downloads in two weeks is a strong start, and it stays small beside the billions of people using Facebook, Instagram and WhatsApp every day.
The revenue is not in the results yet. Fast download growth does not guarantee the same growth in paid subscriptions and revenue.
The agent depends on other companies' services. What an AI agent can do depends on access to outside platforms. Limits set by large internet companies would reduce what Muse can offer.
Capital spending is heavy. Meta spent 50.9 billion USD in the first half of 2026 against full-year guidance of 130 to 145 billion, which leaves 79 to 94 billion for the second half. Free cash flow fell to 0.8 billion USD in the second quarter. If AI revenue does not start covering that spending, Meta could go through a period of negative free cash flow.
Expectations are already in the price. After the rally the market is pricing successful monetisation in advance. Slower audience growth or revenue below expectations could bring a sharp correction in META.
Meta reports quarterly, so another set of results falls inside the three-month horizon of this idea. That report is where the download numbers meet the cash flow statement, and any of the points above can move the stock sharply on the day.
Should You Buy META Stock Now?
The Muse launch has visibly improved the Meta story. The company has its first mass consumer AI product, one that could bring in revenue through subscriptions, commercial transactions and access to its models.
After a rise of more than 30% since the start of September, buying at the current price is the aggressive version of that view. Stochastic is in overbought territory, the average analyst target sits only a little above the market, and Meta keeps raising capital expenditure, which is pressing hard on cash flow: free cash flow fell to 0.8 billion USD in the second quarter, and it could turn negative if spending keeps climbing. A deterioration like that rarely goes unnoticed for long.
The more conservative version waits. For traders the actionable level is 700 USD: a pullback into the retest area fills the Buy Limit and opens the long scenario toward 900 USD, while a daily close below 620 USD cancels the setup.
Comments
Log in or sign up to join the conversation.