
Early Meta Muse Data is Extremely Bullish
“Muse,” Meta Platform’s (META - Free Report) agentic AI offering, debuted in early September. In just over a month, Muse shot to the top of the Apple App Store rankings and became the fastest-growing consumer app in history outside OpenAI’s ChatGPT. Beyond the rapid user growth, the latest data from Meta’s earnings call revealed that each customer is more valuable than a typical AI customer. CEO Mark Zuckerberg explained:
"The most common use case for Muse is shopping. With more than a quarter of people who are using Muse engaging in this with an average purchase size of over $200, Plaid told us that they hadn't seen activity like they're seeing with their connector on any other service before. And in the first week, we had to work with Stripe to raise credit limits since the volumes were above what any of us expected. Beyond shopping, the most common connectors are for personal productivity and connecting Muse to your other services like email and calendar."
In other words, Muse users are premium, making it easier for Meta to monetize in the future.
Meta Retreats to the 10-week Moving Average
Most amateur investors focus too much on short-term time frames and suffer from recency bias from the latest price movements. Conversely, seasoned investors understand the value of analyzing higher time-frame charts (like weekly charts) to filter out the noise and size up the overall trend.
Although Meta dropped ~5% Thursday after its earnings, the overall price trend remains firmly higher. From late July to late September, Meta shares ripped from ~$524 to $780 in a straight line. Before earnings, shares digested the move and traded sideways. However, after earnings, Meta shares tagged the 10-week moving average for the first time since the breakout. Historically, such pullbacks are high-probability buy-the-dip opportunities for investors.
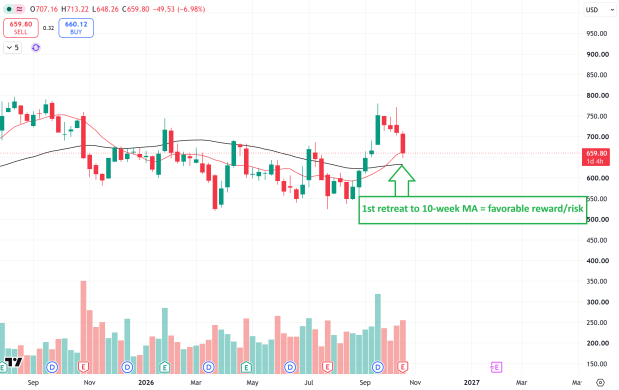
Image Source: TradingView
Meta is Extremely Cheap
With a P/E ratio of just 23x, Meta is the cheapest “Mag 7” name.
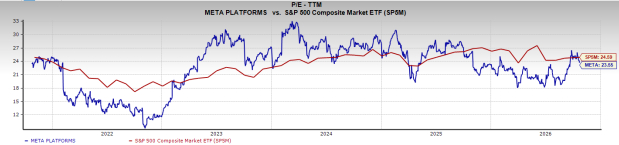
Image Source: Zacks Investment Research
Meta’s Top-Line Growth is Robust
Zacks Consensus Estimates suggest that Meta’s revenues will grow at 20% or more through next year. Considering the robust double-digit growth and reasonable valuation, Meta is sure to attract growth-at-a-reasonable price (GARP) investors.
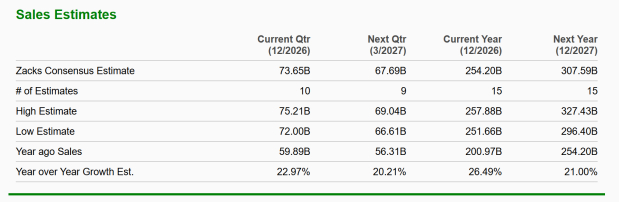
Image Source: Zacks Investment Research
AI Impact on Ad Revenues
While Muse garners the most attention for Meta’s AI efforts, its in-house AI optimization efforts are bearing fruit. In Q2, Family of Apps revenue rose 28% year over year to $60.4 billion as ad impressions increased 14% and average price per ad increased 12%.
Bottom Line
Early data confirms rapid adoption and strong monetization potential for its Muse AI platform. Meta Platforms continues to prove its leadership in agentic AI. Combined with robust top-line growth, double-digit gains in digital advertising revenue, and a highly attractive GARP valuation of just 23x earnings, the recent post-earnings dip to the 10-week moving average presents a compelling, high-probability entry point for long-term investors.
Comments
Log in or sign up to join the conversation.