
Oil is still swinging on US–Iran deal headlines. Brent is back above $110 after Tuesday’s spike. The US 10-year yield sits near 5.1%, which keeps pressure on AI-stock valuations. Weak US housing data (starts –5.2% m/m) pulled the dollar and yields lower.
Wall Street (Tuesday): Dow +1.0% to 52,496 | S&P 500 +0.3% to 7,713 | Nasdaq flat at 26,425. SpaceX and Super Micro beat expectations after the close.
Asia today:
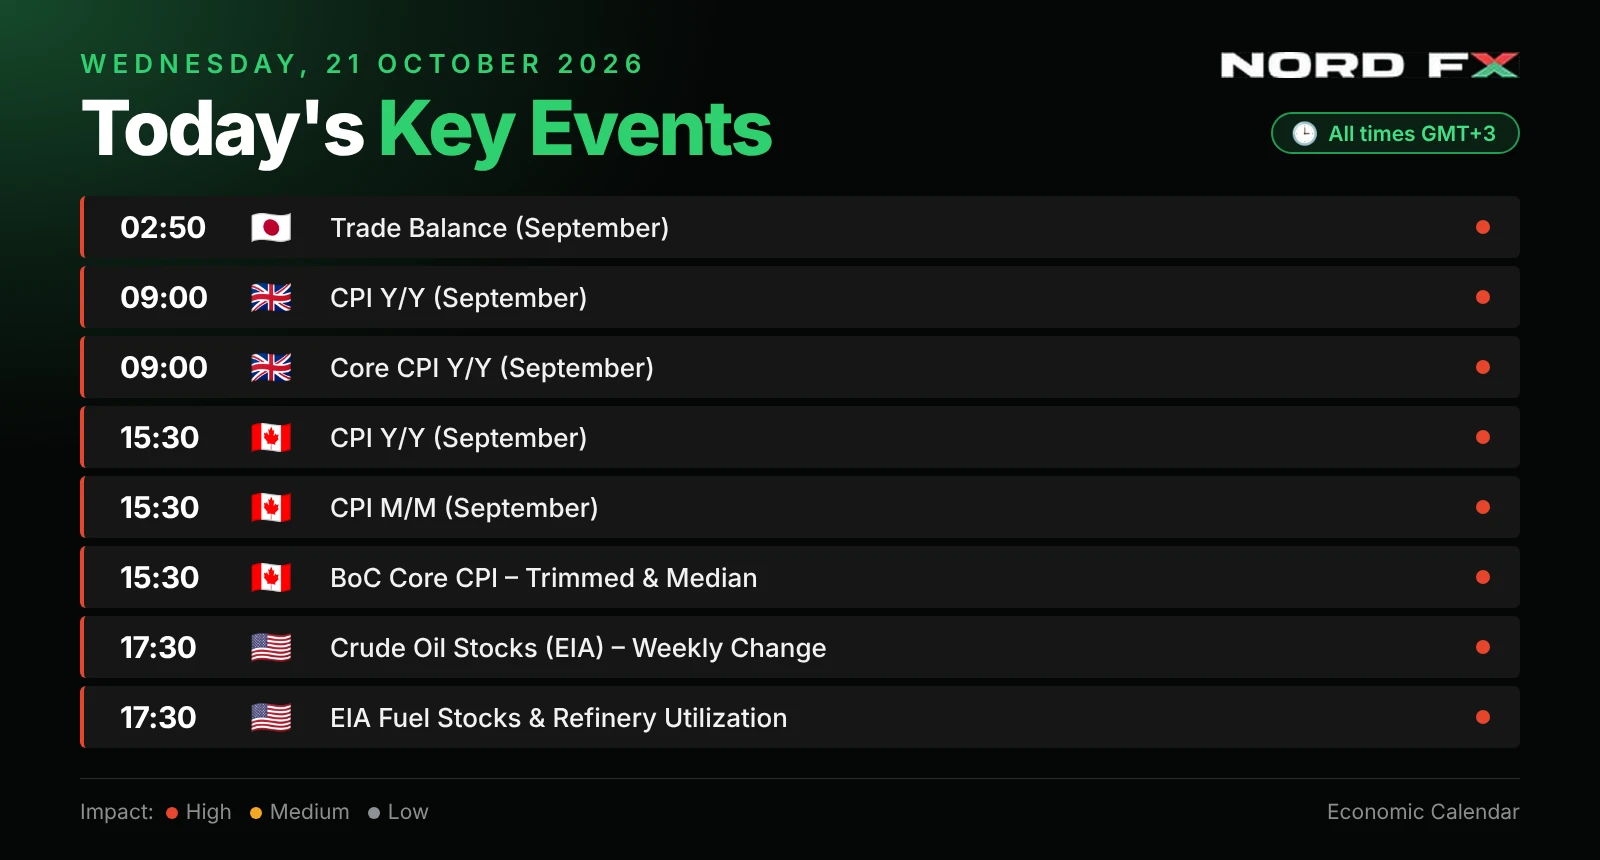
Nikkei 225: +1.15% (~64,813). Chip stocks led the gain, while Japan’s September trade deficit came in at ¥536.6B against ¥181B expected.
KOSPI: +2.8% (~5,709), rebounding after Tuesday’s sharp drop.
Hang Seng: –0.4% (~23,768)
Shanghai Composite: –0.3% (~3,724)
ASX 200: +0.2% (~8,831). RBA’s Hauser said the inflation outlook looks worse than forecast, which puts a November hike in play.
Nifty 50: +0.4% (~22,973)
Forex: EUR/USD ~1.1223 | GBP/USD ~1.3375 | USD/JPY ~158.17 | AUD/USD ~0.7017
Commodities: Gold ~$4,123 | Silver ~$57.46 | Brent ~$110.24 | WTI ~$99.01
Crypto: BTC ~$82,830 (+1.3%) | ETH ~$2,446 (+2.1%)
Today:
UK CPI is expected to rise toward the mid-3% area, and sterling is in focus after firm jobs data.
Earnings after the close: Tesla, Meta, IBM.
Comments
Log in or sign up to join the conversation.