
Macro theme: AI-spending doubts and Middle East tensions are driving a global risk-off move. Chip stocks are tumbling and Brent is near $114 on Iran strike reports and attacks on Saudi oil sites. Investors are moving into bonds.
Wall Street (Thursday close):
S&P 500: 7,663 (–1.21%)
Nasdaq: 26,009 (–2.60%), its worst day since June
Philadelphia semiconductors: –6.7%
Dow: 52,868 (+0.02%)
VIX: 19.0 (+14%)
US 10-year yield: ~4.97%, after its biggest drop in over two years
Europe (Thursday close):
DAX: 25,372 (–1.07%)
CAC 40: 7,811 (–1.39%)
FTSE 100: 10,725 (–0.26%) 📉
Asian markets (live):
Nikkei 225: 62,442 (–0.74%), after dipping to near-3-month lows
Kospi: 5,482 (–0.93%), chip names under pressure 💥
Shanghai Composite: 3,646 (–0.33%)
Hang Seng: 23,090 (+0.68%), rebounding from 3-month lows
ASX 200: 8,795 (+0.02%)
Markets (live):
Gold: $4,029 (–0.77%), after briefly dipping below $4,000
Silver: $54.13 (–1.61%)
Brent: $114.00 (+0.73%), highest in over five months
WTI: $100.38 (+0.91%)
EUR/USD: 1.1210
USD/JPY: 156.90
Bitcoin: $81,720 (–1.39%)
Ethereum: $2,400 (–1.59%)
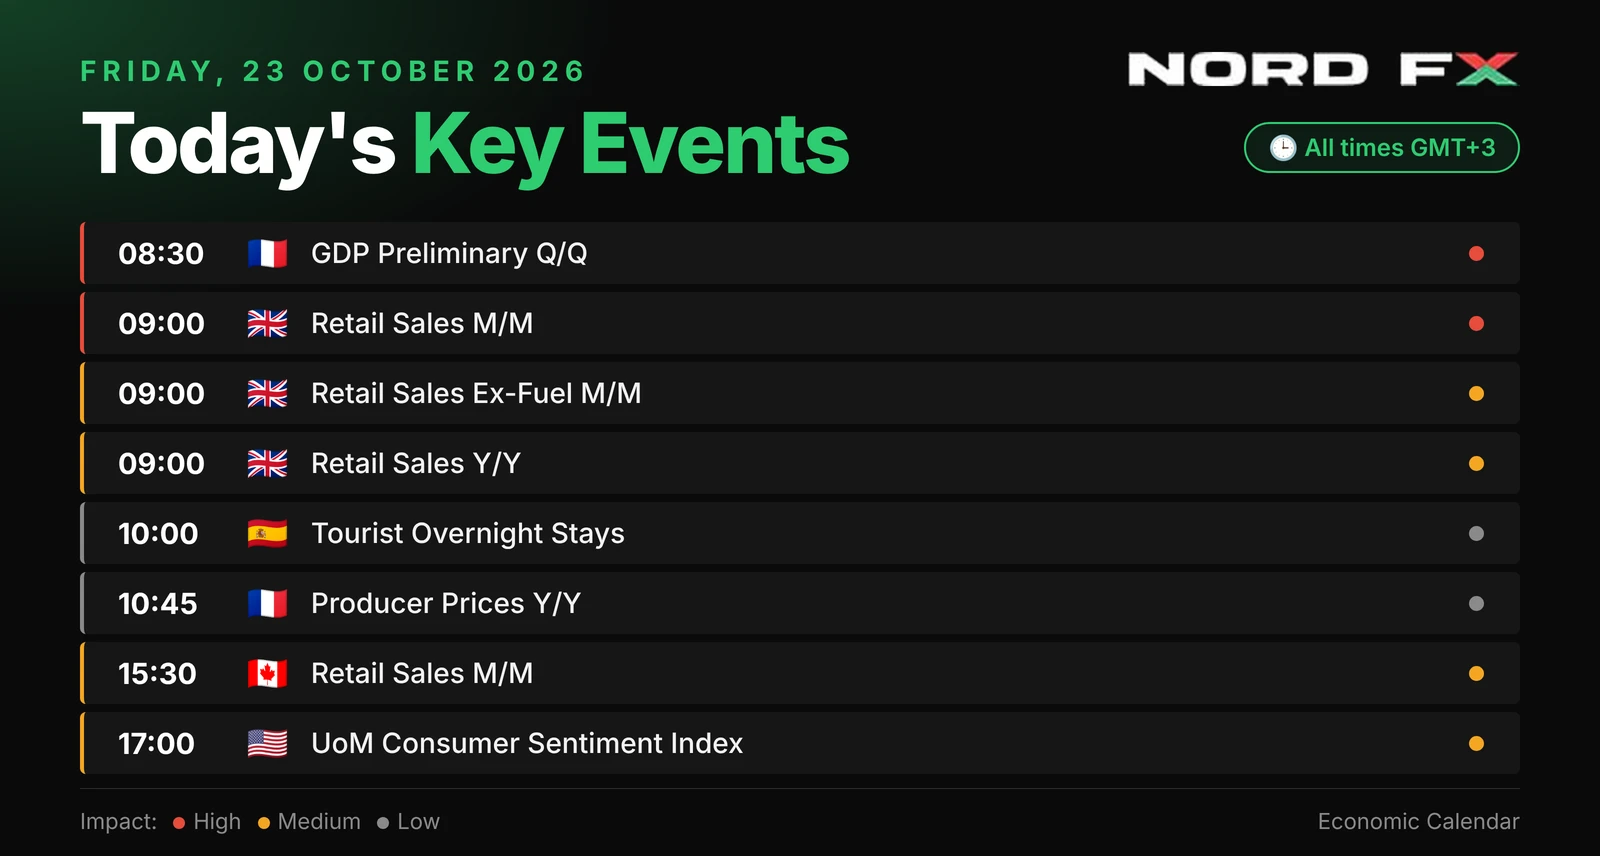
Today (GMT+3):
09:00 – UK retail sales (forecast –0.1% m/m)
10:30–11:30 – Flash PMIs: Germany, Eurozone, UK
13:30 – Bank of Russia rate decision (forecast 14.0%)
16:45 – US flash PMIs (composite forecast 57.6)
17:00 – Michigan consumer sentiment (forecast 46.3)
Watch the AI trade and oil headlines – they are setting the tone for everything else.
Comments
Log in or sign up to join the conversation.