
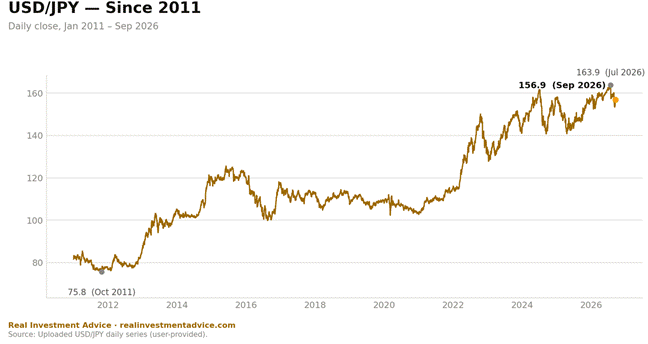
A dollar today buys nearly twice as many Japanese yen as it did fifteen years ago. Crude oil, in yen terms, is up roughly 70% year to date. Food prices are similarly elevated. Japan imports most of the energy and much of the food it consumes, paying for it in dollars that keep getting more expensive. Those facts alone should lead us to conclude Japan has an inflation problem.
As if those factors weren’t enough, add their debt overhang, with the narrative that mounting government debt is inflationary. If that logic holds in the US, it should apply with even more force in Japan, where government debt is nearly double ours as a share of the economy, and where the yen carries none of the dollar’s reserve-currency privilege to cushion its borrowing needs.
A collapsing currency, heavy import dependence, and the developed world’s heaviest debt load. Surely that’s a recipe for an inflation crisis. Instead, Japan’s latest data shows headline CPI at 1.9% and core at 1.7%, both below where the US sits today.
Let’s go to Japan and find out why an economy with seemingly every ingredient for runaway inflation has relatively tame inflation. The facts may change how you think about the relationship between government debt and inflation in the US.
The Data
From 1995 to the present, Japan’s CPI averaged a mere 0.50%, with deflation marking 13 of the 31 years shown below. Since the pandemic, inflation has been above its 2% target. As a result, the Bank of Japan (BOJ) has been slowly raising its policy rate. Today, the policy rate is 1.25%, a departure from zero and negative rates that presided over much of the period shown below.
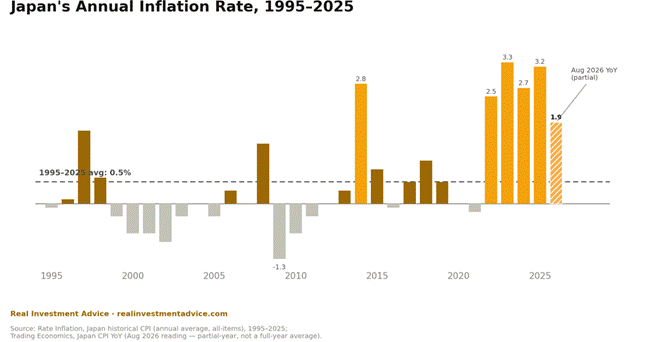
Japan’s recent inflation is certainly higher than the 1995-2020 experience, but it’s still running below America’s, where July CPI and Core CPI were 3.4% and 2.5%, respectively.
Measure | Japan | United States |
Headline CPI, YoY | 1.9% | 3.4% |
Core CPI, YoY | 1.7% | 2.4% |
Policy rate (hiked Sept. 16) | 1.25% | 3.75–4.00% |
A Setup Built for More Inflation, Not Less
Japan self-supplies only 16% of its energy and 37% of its food, meaning most of what heats Japanese homes, runs its factories, and feeds its people is bought abroad, in dollars. Run that through a currency that’s lost nearly half its value against the dollar since 2021 and oil that’s up over 50% year over year, and Japanese wholesale inflation has been affected. To wit, Japan’s corporate goods price index ran at 7.2% year-over-year in April, with import prices in yen up 29% versus 17.7% in the exporter’s own currency. That 11.3% gap is almost entirely related to the yen’s depreciation.
A 7.2% wholesale inflation rate on top of its currency and import exposure is the kind of setup that has produced double-digit consumer inflation in many other countries. Yet, Japan’s consumer inflation is less than 2%.
Some of the lack of inflation pass-through to consumers stems from subsidized energy prices and businesses still absorbing costs rather than passing them through. Aging demographics and a declining population also weigh on consumer demand and inflation. Furthermore, and maybe most importantly, government debt is presenting a strong headwind, as we will discuss next.
The Debt Question
If the “debt and deficits are inflationary” story were true, Japan should be the cautionary tale, not the United States. Its government owes 1.6 times as much, relative to the size of its economy, and finances almost all of it with domestic capital. Very few foreign investors own Japan’s debt, while foreign buyers absorb nearly a third of U.S. Treasuries.
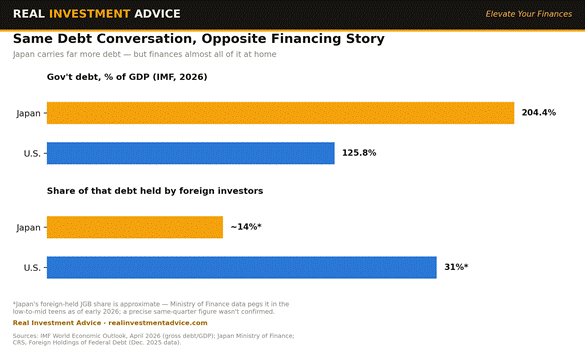
The level of debt does matter, and in Japan’s case it is very problematic, but not in the way most people think. Government debt isn’t free money injected into the economy. Instead, it’s a claim on capital today and when the debt gets serviced and rolled over in the future. Every yen or dollar used to fund the servicing and rollover of existing and new government debt is a yen or dollar a bank, insurer, or pension fund didn’t lend to a business building a factory, hiring workers, investing in R&D, or expanding capacity.
Economists use the term negative growth multiplier to describe the economic impact of most government debt. Because government spending tends to be unproductive, debt servicing typically offsets the initial benefits over time. In aggregate, government debt reduces economic activity and impedes an economy’s ability to become more productive.
This idea was made popular by Reinhart and Rogoff’s 2010 research on debt overhang. They concluded that when government debt exceeds roughly 90% of GDP, each additional dollar of debt-financed spending buys progressively less growth, not more.
Japan Crowds Out Economic Progress
Japan is a real-world test case for Reinhart and Rogoff’s theory. With banks, insurers, pension funds, individuals, and the Bank of Japan (BOJ) absorbing most Japanese debt, that capital isn’t chasing more productive private investment. Furthermore, with little economic growth for the past twenty years and a generally deflationary environment, the desire to invest in private Japanese ventures has been greatly curtailed
To wit, Japanese corporations sit on some of the largest cash hoards in the developed world rather than deploying it domestically. What Japan is witnessing is the crowding-out effect. The result of the government demanding large amounts of capital is not inflation or higher interest rates, but rather capital parked unproductively in Japanese debt instead of investments that can generate organic, demand-pull inflation and economic growth.
Debt, in other words, hasn’t been a demand-side accelerant in Japan. The US, with a lower debt ratio and a captive foreign bid for its debt, is not in the same boat as Japan. However, debt is crowding out investment into more productive uses, and rising interest rates will make the crowding-out effect a bigger drag. This should give pause to anyone claiming more debt equals more inflation.
TFP Tells The Story
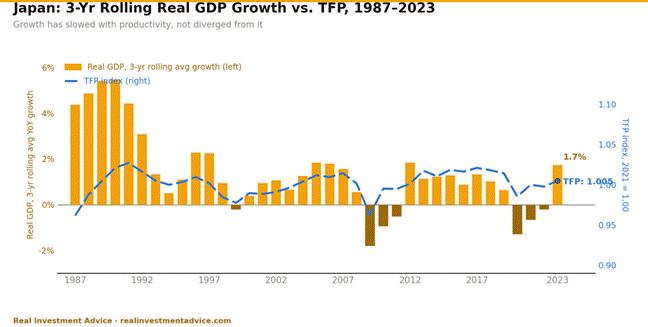
Total factor productivity (TFP) measures the output an economy gets beyond what capital and labor add. Think of TFP as the gains from technology, innovations, and smarter capital allocation. Over long-term horizons, TFP is the main driver of per-capita growth as labor and capital have limits. In Japan’s case, its aging population, strict immigration laws, and declining population mean that labor is negatively impacting economic output. Furthermore, as we have been discussing, capital is being misallocated toward the deficit. Thus, its limited TFP is the primary source of growth.
The chart below shows that Japan’s Total Factor Productivity (TFP) has been flatlining around 1%, as has its real GDP growth.
Summary
The simple deficits = inflation story being used to justify buying gold and bitcoin while shedding bonds at all costs is lacking. Instead, we must consider the longer-term implications of government debt and how too much debt inhibits economic demand and limits inflation by reducing investment in more productive uses.
Japan can thank its high debt loads and aging demographics for the inflation restraint. But bear in mind that the cost paid in stagnant growth and diminished prosperity for its citizens has been dear. We do not fear an inflationary spike in the US; instead, we are concerned that the economic doldrum that has infected Japan for over 25 years will slowly work its way here.
Comments
Log in or sign up to join the conversation.