
That was the subject of the daily afternoon email from Bloomberg, referring to what is happening in the treasury market as yields continue to work higher, sending prices lower.
I pulled up the following halfway through the trading day, thinking more like the pain continues for holders of long bonds more than thinking it was a meltdown.
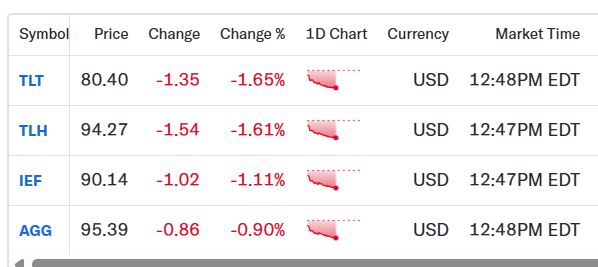
Bespoke tweeted out that since inception, TLT is down slightly on a price basis and that on a total return basis it is down going back to 2012. There's been a flood of pundits weighing in across the web about why longer bonds are now attractive, but the same or similar arguments were made at lower yields on the way up to the now current 5.11% on the ten-year Treasury.
I'm sure the textbook logic expressed in those opinions is correct, but yields still keep going up. It is correct that losses from 4% going up to 5% are different than losses from 1% up to 2% were because, as the price does its thing, investors are collecting 4% versus collecting 1% or less five years ago. That does nothing for the volatility or the risk that rates go higher from here. It is difficult to see the price inflation problem subsiding soon, and that certainly is relevant.
The way we have been framing this has been as a matter of adequate compensation. Forget all the textbook logic, what return do you find to be adequate compensation for the volatility of owning intermediate and longer-dated debt? For me, low fives don't do it. Maybe at 6% if it ever happens; not sure, but at 7% probably a little.
I've been repeating the above sentiment about 6 and 7%....if it ever happens for quite a while. I have no idea if it will ever happen, but I do know that 5+% is not adequate compensation.
Comments
Log in or sign up to join the conversation.