
DoorDash (DASH) is showing unusually large volume in out-of-the-money call options today. This follows reports that DoorDash may be interested in buying a competitor, Maplebear, Inc., dba Instacart (CART). Is DASH undervalued here? It looks like it could be. This article shows why and also discusses a potential merger with Instacart.
DASH is down slightly at $169.69, but it's now near 4-month lows. It was last at this level on July 23 ($169.77). That was just before Q2 earnings results. DoorDash is set to release its Q3 earnings next week on Nov. 4 (after market close).
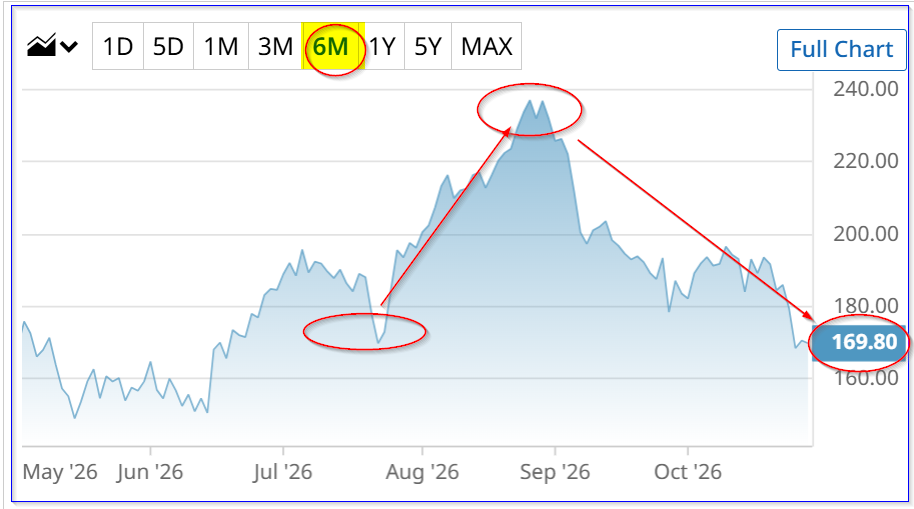
DASH stock - last 6 months - Barchart - Oct. 28, 2026
Investors seem skittish ahead of earnings, although the company is very strongly free cash flow (FCF) positive. Moreover, there is every indication this will continue.
So, can DASH handle a CART takeover? Are analysts positive on DASH as it stands? If so, that could be why there is so much heavy call option buying today.
Unusual Call Option Activity
This is shown in today's Barchart Unusual Stock Options Activity Report. It shows that over 12,500 call options at the $180 strike price expiring Jan. 15, 2027, have traded.
That volume is over 71 times the prior number of call options outstanding.
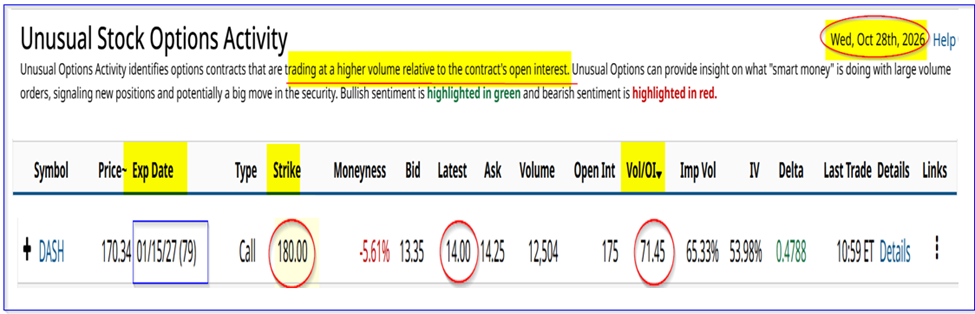
DASH calls expiring Jan. 15, 2027 - Barchart Unusual Stock Options Activity Report - Oct. 28, 2026
Moreover, the $14.00 premium paid by call buyers makes the all-in exercise price equal to $194. That's 14.3% above today's price. The good news for the call buyers is that there is almost one quarter (79 days) for this to work out for them.
On the other hand, short-sellers of these calls collect an immediate yield of 8.25% (i.e., $14/$169.69). If this can be repeated, the annualized rate is very high: 42.55% (8.25% x 4.6x/yr).
Moreover, even if DASH rises to $180, the total expected return to covered call sellers is attractive at 14.3%.
So, is DASH undervalued here, and can it handle a takeover of Instacart?
DASH Looks Cheap
Last quarter, DoorDash generated $883 million in free cash flow (FCF) on $4.454 billion in revenue, which grew 36% YoY. That represents a 19.8% FCF margin, which was higher than the prior quarter's 13.3% FCF margin, according to Stock Analysis.
Over the last year, it has generated almost $2.6 billion in FCF, or 16.33% of revenue.
Moreover, analysts expect revenue next year to rise by over 20.7% to $21.54 billion. So, if DoorDash can maintain a 19.8% FCF margin, FCF could rise to $4.265 billion. That's 78% higher than its TTM (trailing 12-month) $2.6 billion.
Assuming it could achieve at least $4 billion in FCF (i.e., an 18.6% FCF margin), and using a 4% FCF yield (i.e., 25x FCF):
$4b FCF x 25 = $100 billion fair mkt value (FMV)
That is 36% higher than its present $73.46 billion market cap. In other words, DASH has a price target (PT) of $230.78 (i.e., $169.69 x 1.36).
Analysts surveyed by Yahoo! Finance have an average PT of $257.37, and Barchart's PT is $260.08.
The bottom line is that DASH looks undervalued at today's depressed trading price. But could it handle a takeover of InstaCart?
InstaCart Takeover Possible?
Maplebear has a market cap of almost $14 billion, and there is talk of a $17 billion takeover price tag after the company put itself up for sale. Neither company has confirmed these talks.
Right now, DoorDash has just $5.347 billion in cash on its balance sheet, including marketable securities. So, any tie-up would likely involve taking on debt, issuing stock, or a combination of the two.
The good news is that Maplebear generated $481 million in FCF last quarter (a 46% FCF margin) and has produced $1.176 billion in FCF over the last 12 months, or 29.5% of revenue.
It's possible the combined company could make $26.25 billion in revenue ($21.54b DASD plus $4.71b CART). So, assuming some synergies, the combined company could generate $6.355 billion in FCF.
That could easily support a combined market cap of $127 billion, using a 5% FCF yield.
Therefore, if DASH's total share count increased by 23% (i.e., $17b/$74b), 433.3 million to 533 million (i.e., 23% dilution in a takeover at $17 billion), the fair value is still higher:
$6.355 billion / 0.05 = $127 billion FMV
$127b FMV / 0.533 b shs (post-merger) = $238.5 per share
That is 40% over today's price.
The bottom line is that if DASH issued shares at a $17 billion market cap to CART, i.e., a 23% dilution, the combined FCF could support a 40% increase in the DASH stock price.
So, this might be a good deal for DoorDash. That could be why investors are buying a large volume of call options today in DASH.
Comments
Log in or sign up to join the conversation.