
Yesterday the U.S. Fed raised interest rates for the first time in three years. This was not unexpected. What might it mean for medium-term gold and silver (“Ag”) prices? I don’t know about the short-term, but the medium-to-longer-term outlook remains bright.
Readers are reminded that Ag is increasingly used for industrial purposes, it’s not merely a precious metal like gold. The Silver Institute projects were in a sixth straight deficit year of 46.3M troy ounces, (widening from 40M last year), with cumulative shortfalls since 2021 of over 750M.
Bank forecasts for late 2026–2027 cluster around US$65–80/oz. UBS sees $70 at year-end, rising to $80 by Sept-2027; Commerzbank is calling for $80 next year. RBC forecasts $83, Citi says $90 is possible. BofA flags a short-term spike to $100 tied to a run in gold, then back to $75.
By contrast, silver bugs like Robert Kiyosaki, Jim Rickards & Peter Schiff talk of $200 as a crisis / monetary target. BMO ran a, “thought experiment” of ~$160 by late-2026 and $220 by late-2027. Eric Sprott is sometimes pegged around $200-$300.
Bottom line, virtually no one thinks Ag will fall below $50 (ever again, for an extended period). Major & mid-tier producers are far more worried about a return to triple-digit Ag than a decline to $40-$50… Metals & mining is the new Tech, it’s printing money.
In order to justify higher valuations, producers need to bolster pipelines with increasingly aggressive M&A strategies. An Ag-zinc company I continue to love just put out a much anticipated PEA.
Honey Badger Silver’s (TSX-v: TUF) / (OTC: HBEIF) PEA is attractive in several key respects. Using US$50/oz Ag (25% below the spot price cited in the PEA press release), the post-tax NPV(8%) is C$1.7B vs. upfront cap-ex of C$667M. That delivers an attractive 2.5x ratio of NPV to cap-ex.
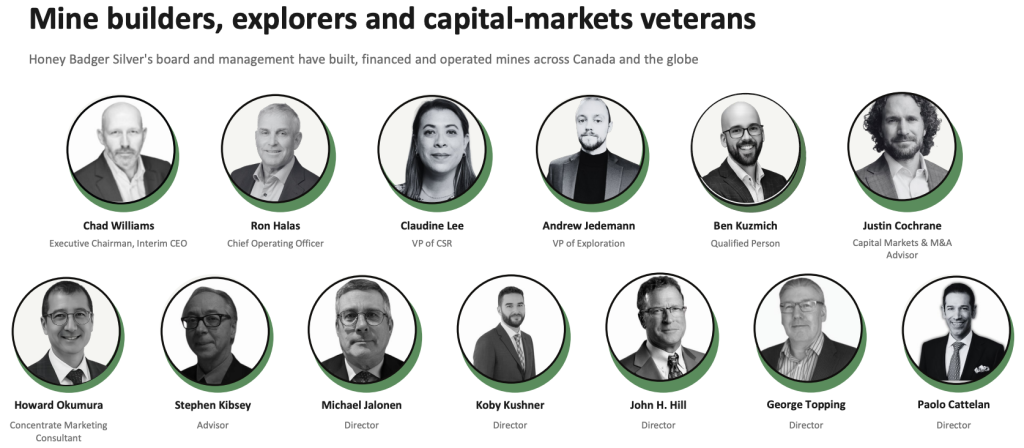
Exec. Chair Chad Williams commented,
“…we believe PC Silver is highly financeable with the potential to minimize further equity dilution. We have received inbound interest from major smelters and off-takers, debt providers, government agencies and infrastructure investors, as well as two unsolicited expressions of interest for complete turnkey project financing. With the PEA now complete, the Board has authorized us to immediately commence the next stage of engineering and advance directly toward a Feasibility Study, which we are targeting for completion in the second quarter of 2027.“
At the Ag price of $66.4/oz on August 31st, NPV rises to ~C$2.6B and the IRR to +38%. The base case payback period is 3.1 years. This will be a significant Ag-zinc mine, with a 22-year mine life producing 10.7M Ag Eq. ounces/yr., in years 1-7, and 7.9M oz/yr. for life of mine (“LOM”).
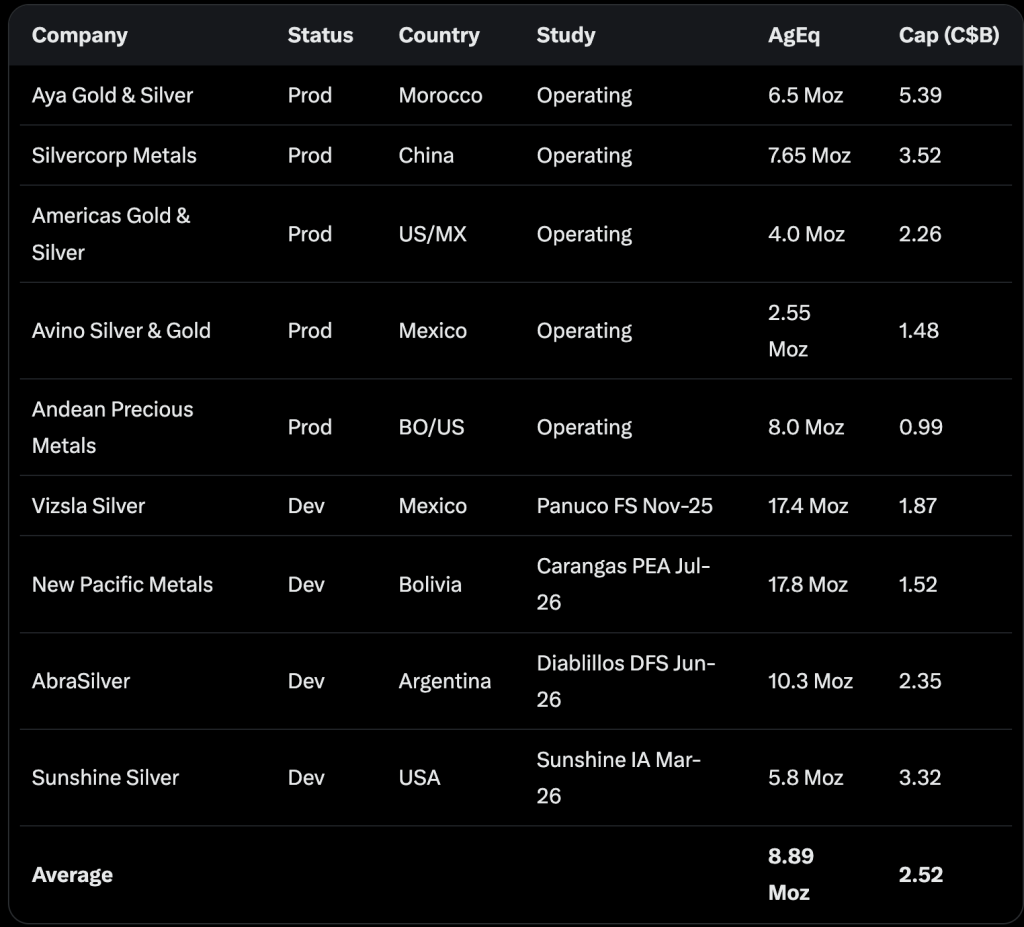
Compare that 7.9M/yr. LOM production to the average of the following producing + pre-production peers. Although about a third fewer ounces than the 8.9M oz/yr. average, Honey Badger’s market cap is ~90% lower than the peer average.
Note the locations of these comps; Morocco, China, Mexico, Bolivia, and Argentina. I prefer Canada. Admittedly, PC Silver is remote, in Canada’s NWT, but Agnico Eagle, Glencore, Teck Resources, South32, and B2Gold have mines/projects as (or more) remote across Nunavut & Alaska.
Newmont, AngloGold Ashanti & Gold Fields have remote assets in Australia. Kinross, Barrick & IAMGOLD in parts of Africa. Several S. American mines/projects in the high Andes and deep Amazon are more remote than PC Silver.
With Ag over $65/oz, arguably headed higher, remoteness is not a big problem, it’s a cost of doing business. The new resource estimate tied to the PEA shows ~292.5M Ag Eq. ounces at an average grade of 453 g/t Ag Eq. The resource total & grade is down, largely due to an increase in the assumed Ag price.
Notably, none of the potential economic value from germanium, antimony or tungsten, nor recent (new) Canadian tax incentives, are included in this PEA. However, antimony (“Sb”) is included in the resource estimate.
Regarding germanium, it would not take much of it to move the needle. It was valued in July, by Fastmarkets, (outside of China), at US$10,000 – $12,500/kg. Even modest recovery rates could make exploitation viable. Management is careful not to overstate the potential, but prospects look promising.
The following table depicts early-stage Ag-heavy juniors (large resources, averaging ~217M Ag Eq. ounces) with an average grade of 253 g/t Ag Eq. The EV/oz. ratio for these six is C$3.03/oz. By contrast, Honey Badger is valued at just C$0.47/oz.
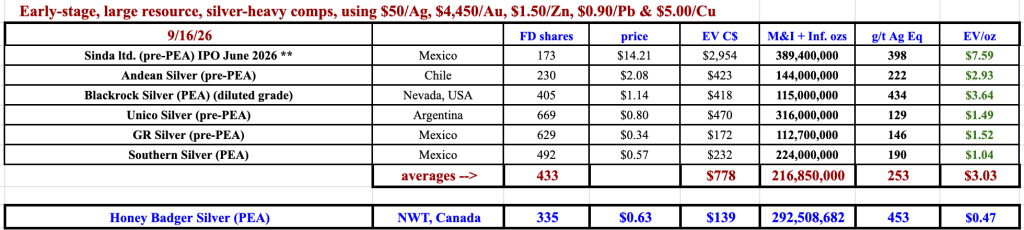
Honey Badger’s project in Canada is (in my opinion) as good or better than most Mexican and S. American jurisdictions. Switching gears to operating metrics, some might fear C$667M of upfront cap-ex, but again the ratio of NPV/cap-ex is good at 2.5x. Among juniors, a lower ratio of 1.0-1.5x is more common.
Thirty-one (31%) of cap-ex is allotted to a 170 km, C$205M road. This critical road will be built, the question is how much will third parties / government entities pitch in? Some believe a lot of the cost will get reimbursed. Even without free-money grants, tax breaks and low cost loans are likely.
All-in-Sustaining-Cost (“AISC“) on an Ag Eq basis is US$27/oz, but on a by-product basis the figure is negative $22/oz. Why negative? The contribution from zinc + lead is quite significant. Everyone knows Ag is up a lot in the past year. Did you know zinc is +34%? Net, net on AISC, the IRR is +29%.
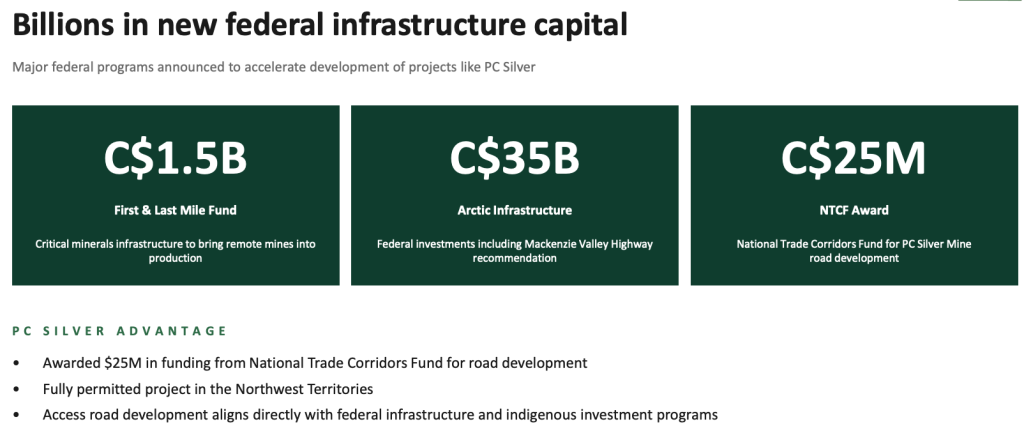
Importantly, management is talking about test milling a 20,000 tonne bulk sample next year, and initial commercial production as soon as 2H/2028 via a winter road, replaced by an all-season road in 2029.
The early-stage projects shown above include a wide-range of prospective production timelines. How many could be fast-tracked into commercial production by 2028? None of them. Only one, Andean Silver, has a mill, but it’s not permitted.
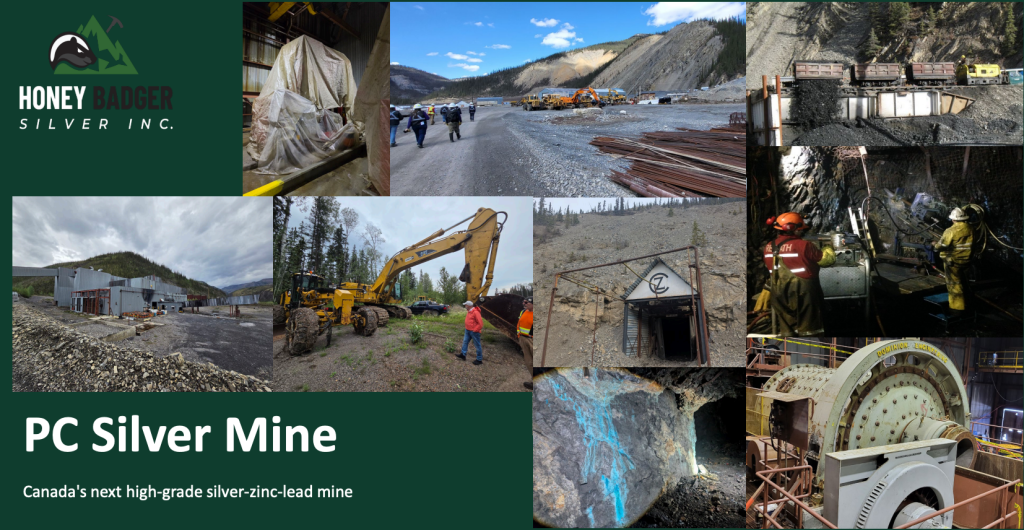
Honey Badger’s mill is largely permitted. It was built decades ago, but barely used, (never commercially operated). It has a replacement cost estimated at C$300M.
Management has engaged Tusk Automation Inc. to evaluate opportunities to accelerate and minimize the cost of restarting the extensive processing facilities in place at the 100%-owned PC Silver Mine.
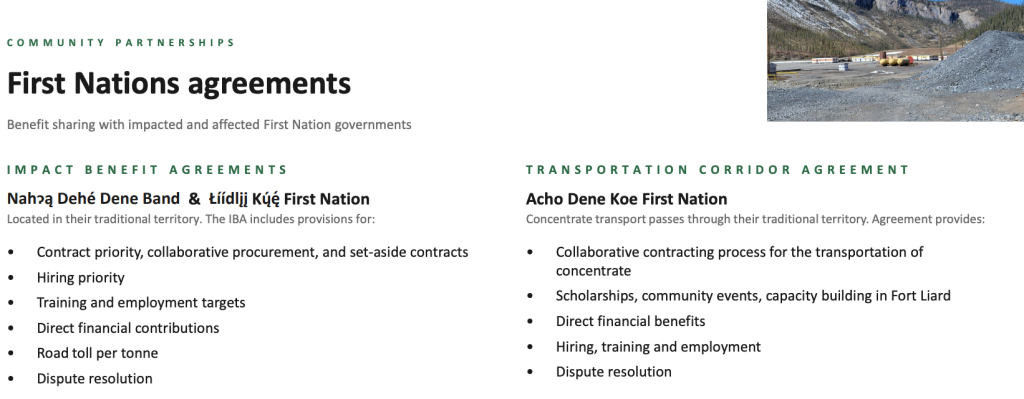
Exec. Chair Chad Williams commented,
“The PC Silver Mine is a high-value processing facility that was substantially completed in 1982, yet never commercially operated. We estimate replacement cost would be at least $300M, and take several years to complete…The entire site has been extremely well preserved because of its cold & dry climate. On-site work is expected to be completed by the end of September and Tusk’s report should be delivered by the end of November… Results will be of a high enough quality to be used in an upcoming Feasibility Study.“
It seems there’s real potential between financial assistance for the C$205M road, and capital outlay savings possibly identified by Tusk Automation, to reduce cap-ex, and/or spread it over a longer period (good for NPV/IRR calculations).
At the same time, if 1, 2 or 3 of antimony, tungsten, and especially germanium could be exploited alongside Ag-zinc-lead, future economic studies could look a lot better than this already good PEA.
To reiterate, none of the three may end up being viable, but the bar for economic recoveries & payables is lower whenever metal prices are higher.
Those critical materials aren’t going anywhere. Even if not exploitable initially, better technology and/or higher prices could make them viable in later years. Investors today get a FREE call option on those metals.
Disclosures/disclaimers: The content of this article is for information only. Readers fully understand and agree that nothing contained herein, written by Peter Epstein of Epstein Research [ER], (together, [ER]) about Honey Badger Silver, including but not limited to, commentary, opinions, views, assumptions, reported facts, calculations, etc. is not to be considered implicit or explicit investment advice. Nothing contained herein is a recommendation or solicitation to buy or sell any security. [ER] is not responsible under any circumstances for investment actions taken by the reader. [ER] has never been, and is not currently, a registered or licensed financial advisor or broker/dealer, investment advisor, stockbroker, trader, money manager, compliance or legal officer, and does not perform market-making activities. [ER] is not directly employed by any company, group, organization, party, or person. The shares of Honey Badger Silver are highly speculative, and not suitable for all investors. Readers understand and agree that investments in small-cap stocks can result in a 100% loss of invested funds. It is assumed and agreed upon by readers that they will consult with their own licensed or registered financial advisors before making investment decisions.
At the time this article was posted, Honey Badger Silver was an advertiser on [ER] and Peter Epstein owned shares in the company, acquired in the open market.
Readers understand and agree that they must conduct due diligence above and beyond reading this article. While the author believes he’s diligent in screening out companies that, for any reason whatsoever, are unattractive investment opportunities, he cannot guarantee that his efforts will (or have been) successful. [ER] is not responsible for any perceived, or actual, errors including, but not limited to, commentary, opinions, views, assumptions, reported facts & financial calculations, or for the completeness of this article or future content. [ER] is not expected or required to subsequently follow or cover events & news, or write about any particular company or topic. [ER] is not an expert in any company, industry sector or investment topic.
Comments
Log in or sign up to join the conversation.