
With everything from yields and fuel prices to populism rising with open elan as trust in U.S. leadership sinks to an historical nadir, most would agree that we are experiencing a palpable as well as intuitive feeling of what George Lucas might otherwise describe as a “disturbance in the force.”
Markets, led today by a narrow handful of tech juggernauts, continue their nervous melt-up despite openly embarrassing indicators of both over- and malinvestment, as yet another game-changing technological wave of AI dystopia seduces the retail plankton into a textbook setup for an historical meltdown.
In the interim, a small minority of early IPO participants and C-suite insiders with advantageous access to easy capital from the big, credit-extending banks will make fortunes.
Unfortunately, small businesses across the rest of the ignored landscape of the American nightmare just posted a 64% Year-over-Year increase in bankruptcy filings.
From Capitalism to Neo-Feudalism
Such trends, numbers, and “forces” are screaming indicators of what I have long described as an America whose superficial claims of “capitalism” are little more than terms of art masking the darker reality of the neo-feudalism now staining the façade of the so-called American dream.
As my son and I enjoyed yesterday’s football game (against Iowa) live from the University of Michigan’s impressive “Big House” stadium, that same university’s infamous consumer sentiment indicator just posted its worst numbers in its five-decade+ history.
Such data effectively confirms that a recession is not only off our bow, but it’s under our keel.
But hey, why worry? We can rename Lake Ontario to “Lake America”, and all will be well again, right?
And let’s not forget that the NASDAǪ 100 has given us five-year returns North of 100%, right?
Even Pam Bondi can remind us to focus on the DOW to keep our faith in American Exceptionalism forever flamed, right?
Hmmm…
The Hidden Crimes
But what few (so very, very few) have realized is that when measured in real money, namely gold, those so-called impressive returns reveal a loss of >20% rather than a gain of 100%.
In other words, if many still think a mythical stock market bubble is going to save us, it’s only because they still think measuring wealth in that melting ice cube, otherwise known as the nominal U.S. dollar, is an actual measure of anything.
For bonds, the story is far darker. Over the last 12 years, USTs, when measured in gold rather than dollars, have punished “safe investors” with a net loss of 90%. How’s that for wealth preservation?
That’s not a typo. It’s a crime.
Based on decades of monetizing trillions in budget deficits with trillions in magical money mouse-clicked at the Eccles Building, the so-called “experts” have been killing the
purchasing power of your currency (and hence wealth) in an incremental death by a thousand cuts.
This murder has now become so exponential that even Wall Street has finally given it a name: “The Debasement Trade.”
But there’s more to this Debasement Trade than its name.
The actual, sad, and oh-so dangerous reality of this trade is nothing more than an invisible tax on your wealth, which operates in actual (yet hidden) fact as unarmed robbery at an historical scale.
The Hidden Criminals…
If this engineered wealth transfer makes you angry, and it should, the natural reaction to such a crime is to better understand who committed it.
As usual, the best evidence trail for such questions and crimes is simple: Just follow the money…
And this trail, not surprisingly, begins and ends with the centralized power, centralized crimes, and centralized (yet hidden) motives of our centralized banks, whose real mandate was never controlling “inflation and employment.”
Their real motive was equally simple. It was simply to control your money.
The Not-So Federal Reserve
When the U.S. Federal Reserve (which is neither federal nor a reserve) was not so immaculately conceived on Jekyll Island and later birthed in 1913 in Washington, DC, by a cabal of private bankers, Woodrow Wilson signed his shaking pen to the greatest wealth transfer in the history of our nation.
Rather than allow the natural forces of supply and demand to determine the cost and supply of credit, a handful of private bankers took monopoly control of the same.
Banking Unveiled – Benefiting the Few at the Expense of the Many
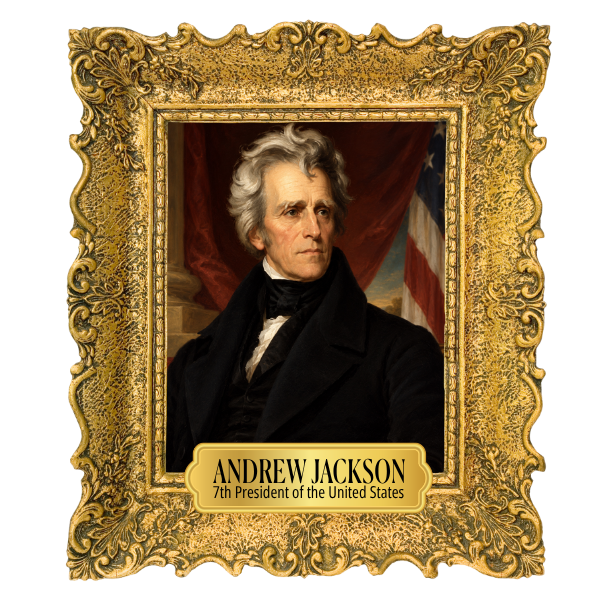
The net result has been precisely what our 7th President, Andrew Jackson, warned as far back as 1832, namely, that our financial system would be prostituted for the “benefit of the few at the expense of the many.”
Jackson knew this because long before this otherwise unconstitutional central bank made its ironic yet deliberate way to Constitution Avenue, he understood the history, tricks, and secrets of powerful banks and powerful bankers.
He knew, for example, that indebted princes, kings, presidents and even warlords of flag after flag and nation after nation never held the real power.
Real power, even the power behind armies and capitols, is nothing without the money to wield it, and that money begins and ends with banks and bankers.
He also knew that nations beholden to banks can also extract money from the masses, which is why it was no coincidence that in the very same year the Fed came into law in 1913, so too did the first Federal Income Tax legislation…
The Crazy Mechanics of Credit (and Money) Creation
Jackson further understood how banks actually operate, which is something almost no one is meant or taught to understand, and that’s because it’s so crazy that if they did, it would unmask the crime at the base of our so-called free society and free markets.
Banks, for example, are not just helpful little servants of Bedford Falls public trust who carefully manage depositor monies by judiciously re-lending one dollar of deposited cash for one dollar of wisely underwritten loans.
Oh no, not at all.
Instead, banks take a dollar of your depositor wealth and then add massive turns of leverage when they make their interest-carrying (typically risky) and bank-profiting loans of your money.
They then use very clever (and legalized) double-entry accounting tricks to hide the dirty little secret that whenever they are extending credit, they are actually creating money.
Such money creation via credit extension may seem academic, but when done at the scale of trillions and trillions, what was once academic just becomes inflationary, debasing, and- at levels this high – just plain criminal.
Credit Is Not Created Equal
By extending credit, leverage, and money creation (i.e., debasement), powerful banks are also extending privilege, and this privilege is not shared equally.
Big banks, you know—the kind that are too big to fail—hold balance sheets in the trillions (especially when you tack on their notional derivatives exposure ), which means they need to make big rather than small loans to move their money and extend their risk exposures.
Needless to say, small businesses and small citizens are not at the top of the priority list for these mega banks.
Instead, the big boys like to make deals with other big boys, which explains why access to capital is not created equal in the so-called land of the free.
Instead, the bigger loans are made to VC funds, mega tech monopolies, and pooled superstars in the private equity and private credit corners, temporarily profiting from “sea to shining sea” from Palo Alto to New York City, but largely bypassing the little guys in the flyover states.
The Big Boys Are Not the Smart Boys
But just because these loans and capital infusions are unfairly distributed to the big boys, this by no means implies that they are made to the smartest boys.
Bailing Out the Bad Boys
But power protects power, and the very credit (i.e., banking) system which triggers the next mega crisis in a nation already $40T in public debt will be once again rescued (“bailed out”) by the very bankers and Treasury Secretaries (i.e., former bankers) who systematically created the crisis.
Remember TARP? Remember the BTFP?
In fact, the very same year our TBTF banks broke the global economy in 2008, over 500 bankers received bonuses in excess of $1M each…
It is fascinating how exempt such a system can be from accountability when the criminals are also the judges…
When the Cure and the Sickness Are One & the Same
Of course, the amount of “stimulus,” “accommodation”, and “synthetic liquidity” required to “save” the next banking (and hence credit) crisis will be historically expensive and hence historically ruinous to paper currencies in general and the USD in particular.
Yes, there is theoretically no crisis a money printer can’t solve, and no market dip or even market implosion that a money printer can’t remodel into a V-shaped “recovery.”
But such “solutions” or “recoveries” are as sickening as the very crises they pretend to “cure,” as they can only be achieved by even greater debasement (and money creation) than the debasement and money creation crisis by which the banking system is inherently defined.
In short, the sickness and the cure are one and the same, and the patient zero is always (and I mean always) a bank.
Gold: The Only Honest Solution
The more honest solution, of course, is as obvious as it is ignored by the vast majority of investors, bankers, and even innocents of the ignored Main Streets.
That solution is now, and has always been, gold.
In crisis after crisis, bank disaster after bank disaster, and currency failure after currency failure, those families, institutions, and sophisticated investors who held gold rather than paper money in a crisis were always the same ones who prevailed rather than failed when their currencies were inflated away/debased into nothing.
But just because your banking system has failed to protect your deposits or dollars in gold, this doesn’t mean you can’t be smarter than your “experts.”
Once you understand their tricks, powers, and historical failures, it’s almost too easy. Gold is no longer a debate; it’s the solution.

Comments
Log in or sign up to join the conversation.