The authors look at the US high yield credits (US HY) and US equities to find out how starting valuations have historically predicted future returns, where current valuations are, and what they could imply for future returns.
Key findings include:
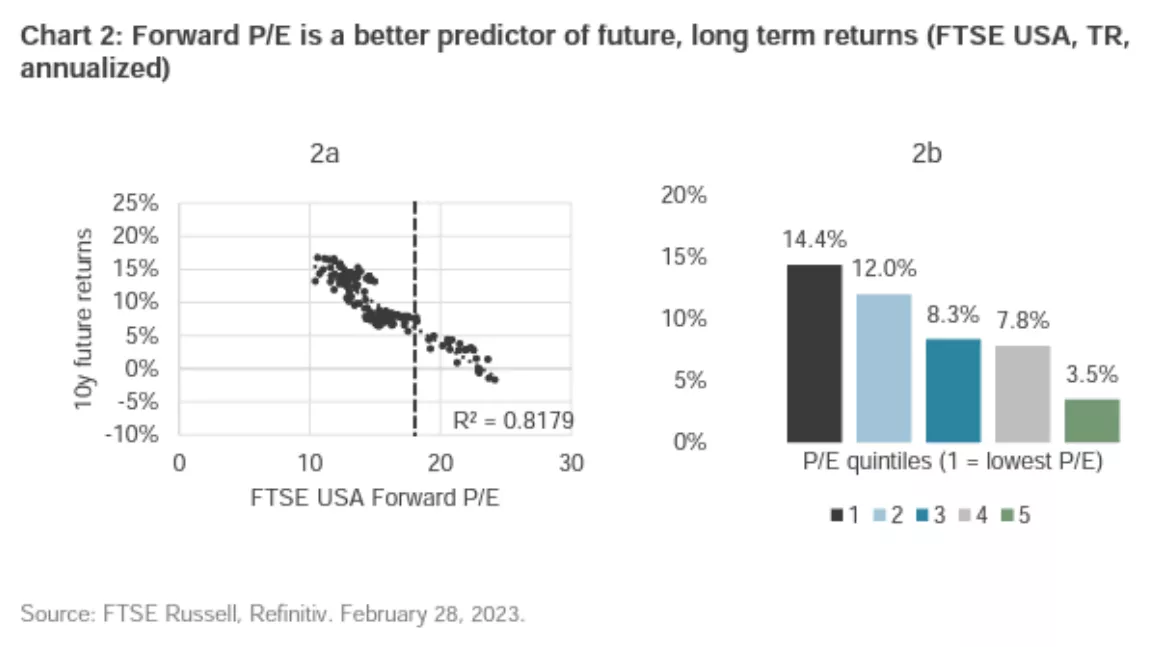
Valuations have a strong predictive relationship with future returns of risky assets like equities and high yields.
Using the monthly returns of the FTSE US High-Yield Market and Russell 1000 indices over the last five years, they found that the correlation between US equities and US high yield credits can be as high as 84% (end-February 2023).
Statistical results indicate that the predictive power of starting valuation is higher in equities for longer periods (i.e.,10yr) and for shorter periods (i.e., 3yr) in US HY credits. This result is in line with the economic intuition that the predictive power aligns most closely with the duration of risky assets.
Disclaimer:
These illustrations are not a solicitation to buy or sell any ETF.
Disclaimer:This and other personal blog posts are not reviewed, monitored or endorsed by
TalkMarkets. The content is solely the view of the author and TalkMarkets is not
responsible for the content of this post in any way. Our curated content which is
handpicked by our editorial team may be viewed here.




Comments
Log in or sign up to join the conversation.