
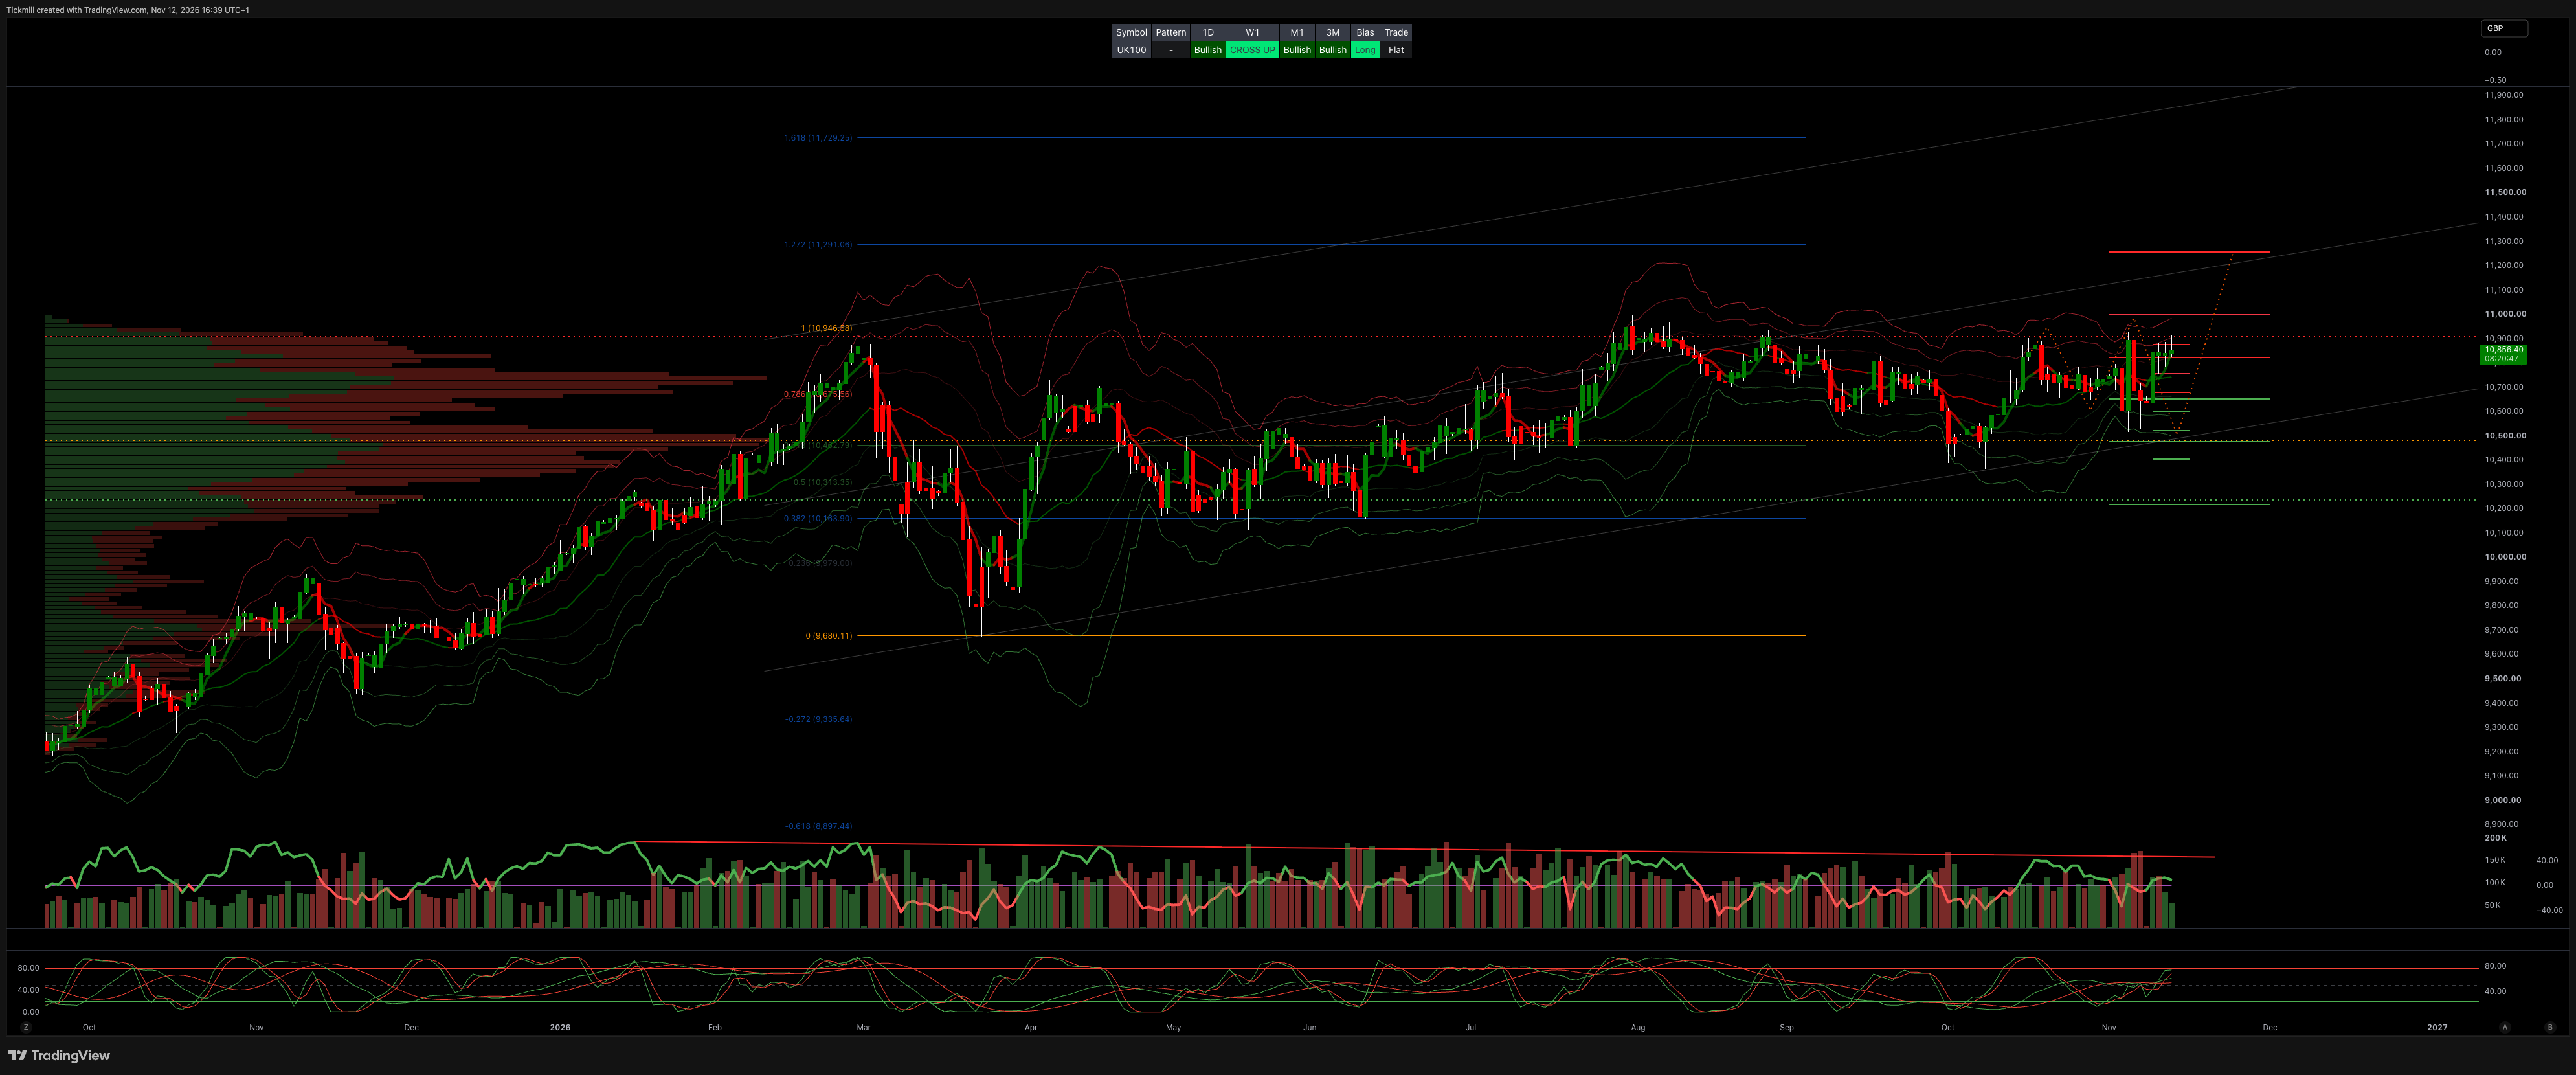
London's benchmark FTSE 100 climbed to a four-day intraday high of 10,886.06 on Thursday before paring much of its early advance into the afternoon, settling modestly higher around 10,848.65 (+0.12%). Strong corporate earnings updates, major share buyback announcements, and solid third-quarter U.K. economic growth buoyed early risk appetite, though heavy selling across mining and defence names capped broader upside into the close.
Retail, private equity, and industrial blue chips spearheaded the day’s gainers on the back of standout corporate updates. Luxury fashion house Burberry Group soared nearly 10% after reporting a 225% surge in first-half adjusted operating profit. Outside the top flight on the FTSE 250, discount retailer B&M European Value Retail zoomed more than 17% after beating first-half sales, margin, and profit forecasts. Private equity giant 3i Group climbed roughly 6% after unveiling a new £750 million share buyback programme and increasing its stake in its flagship investment. Homebuilders found renewed momentum, with Barratt Redrow advancing nearly 4% and Persimmon jumping over 6% on upbeat 2027 volume guidance. Rolls-Royce Holdings rallied nearly 3% after announcing an accelerated £1.5 billion share buyback and reaffirming full-year 2026 targets. Gains between 2.2% and 2.8% were registered by Weir Group, BT Group (BT.A), and Land Securities, while solid advances of 1.3% to 2.0% lifted Melrose Industries, Next, Lion Finance, Kingfisher, Imperial Brands, JD Sports Fashion, Rentokil Initial (RTO), National Grid, Balfour Beatty, Haleon (HLN), and United Utilities.
Conversely, natural resource producers and select defence contractors weighed heavily on the benchmark. Mining stocks fell sharply: gold miner Endeavour Mining dropped more than 6% after guiding full-year production toward the lower end of its range, while Fresnillo fell 2.1%, Antofagasta lost 1.6%, Anglo American Plc fell 1.1%, and BHP declined over 1% after appointing a former Macquarie banker as finance chief. BAE Systems declined 1.3% to lead defence profit-taking despite raising its free cash flow projection for the second time this year. Additional notable pullbacks hit ICG (-2.5%), Babcock International, Polar Capital Technology Trust, Coca-Cola HBC, Scottish Mortgage Investment Trust, and low-cost carrier Wizz Air Holdings (nearly -1%) after warning of higher costs alongside a two-thirds decline in first-half profit.
On the domestic macroeconomic front, official data from the Office for National Statistics (ONS) confirmed resilient economic momentum. U.K. real GDP grew 0.7% quarter-on-quarter in Q3—marking its fastest quarterly expansion in two-and-a-half years, accelerating from 0.5% in Q2, and matching consensus forecasts. On an annual basis, GDP expanded 1.9% in Q3, bolstered by a 0.2% monthly uptick in September following flat growth in August. Production-side figures showed services output rising 0.9% and industrial production edging up 0.1%, while construction contracted 0.7%. Expenditure data highlighted steady 0.6% increases in both household consumption (driven by transport and housing) and government spending. Separately, trade figures showed the U.K.'s visible trade deficit widening to £22.3 billion in September from £19.6 billion in August, bringing the overall goods and services shortfall to £5.13 billion (versus £2.57 billion prior) and 1.3% of nominal GDP for the third quarter.
Finish Line: U.K. equities extended their recovery into a second session as blockbuster results from Burberry and B&M, major capital returns from Rolls-Royce and 3i, and resilient Q3 GDP growth outweighed a broad slump in mining shares. While afternoon profit-taking trimmed the benchmark's early surge toward 10,890, strong corporate fundamentals and steady domestic expansion kept the FTSE 100 comfortably above the 10,800 threshold.
Comments
Log in or sign up to join the conversation.