
Image: Bigstock
Cybersecurity leader Fortinet (FTNT - Free Report) saw its shares plunge 20% on Thursday despite reporting better-than-expected third-quarter results and raising its full-year guidance.
The sharp selloff comes after FTNT had rallied over 100% year-to-date heading into its earnings release on Wednesday evening, as investors grew increasingly optimistic about artificial intelligence-driven cybersecurity demand.
With Fortinet competing against industry heavyweights Palo Alto Networks (PANW - Free Report) and CrowdStrike (CRWD - Free Report), the correction raises an important question: Is FTNT stock now an attractive buy-the-dip opportunity?
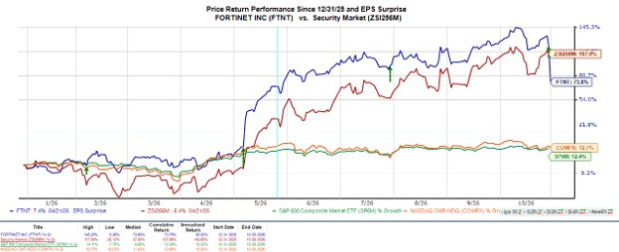
Image Source: Zacks Investment Research
Fortinet's Q3 Results: What Caused the Selloff?
Fortinet reported adjusted Q3 earnings of $0.91 per share, beating expectations of $0.85 and climbing 23% year over year. Revenue increased 20% to $2.08 billion, exceeding estimates of $2.06 billion.
Billings, which measure the value of business billed to customers during a period, rose 29% to $2.34 billion, reflecting healthy demand for Fortinet's cybersecurity solutions.
However, investors were disappointed by slowing product revenue growth, which moderated to 37% from 52% in Q2. More concerning, service revenue increased just 13% year over year, prompting management to lower its full-year service revenue forecast to $5.15-$5.17 billion from $5.18-$5.22 billion.
With expectations elevated following FTNT's massive rally, signs of slowing growth triggered aggressive profit-taking.
That said, it’s noteworthy that the cybersecurity leader has now exceeded the Zacks EPS Consensus for a remarkable 35 consecutive quarters, posting an average earnings surprise of 17.74% in its last four quarterly reports.
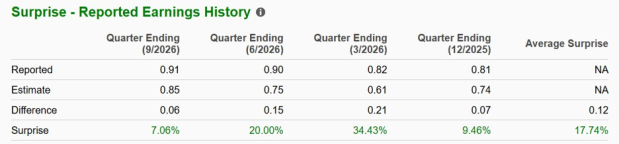
Image Source: Zacks Investment Research
Fortinet's Growth Outlook Remains Encouraging
Encouragingly, Fortinet raised its FY26 revenue outlook to $8.125-$8.215 billion, implying approximately 20% annual growth at the midpoint.
Management also increased its full-year billings forecast to $9.57-$9.72 billion, representing 28% annual growth at the midpoint. Plus, Fortinet expects adjusted earnings of $3.54-$3.58 per share, implying over 28% growth from EPS of $2.76 in FY25.
Demand for next-generation firewalls, secure networking, and AI-driven cybersecurity solutions should remain important growth catalysts as enterprises strengthen their digital infrastructure.
Furthermore, Fortinet expanded its share repurchase authorization by $1.2 billion, providing additional support for shareholder returns.
Bottom Line: Time to Buy the Dip in FTNT?
Fortinet's post-earnings plunge appears to present an intriguing buying opportunity for long-term investors, particularly as FTNT now trades at a more reasonable 37X forward earnings multiple, down from roughly 50X before its earnings release.
This also represents a steeper discount to its Zacks Security industry average of 56X, making Fortinet's valuation increasingly attractive given its strong cybersecurity growth prospects.
For now, FTNT sports a Zacks Rank #2 (Buy), although slowing service revenue growth remains a concern that investors should monitor.
Comments
Log in or sign up to join the conversation.