
Domino's Pizza (DPZ) delivered strong positive free cash flow (FCF), but its FCF margin was slightly lower. But DPZ is still worth over $402 per share, almost one-third higher. Two plays are shorting out-of-the-money puts and put credit spreads.
DPZ closed at $303.09 on Thursday, Oct. 15, well off its Aug. 8 peak of $367.63. This is slightly below where it stood before the Oct. 13 Q3 earnings release ($310.90 on Oct. 12). However, DPZ is treading water near its 3-month lows and could spring higher over the year.
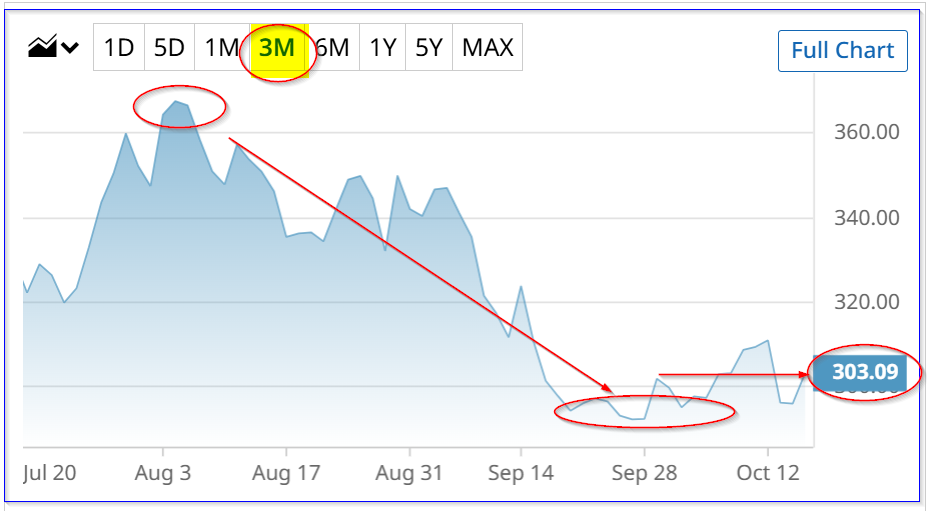
DPZ stock - last 3 months - Barchart - Oct. 15, 2026
Strong FCF and Margin Forecasts
Here's why. People are still buying pizza despite higher fuel costs, and Domino's is still generating strong revenue growth and high FCF margins. Moreover, revenue is forecast to move higher next year. That will push FCF higher.
For example, in Q3, revenue rose +3.4% YoY to $1.185 billion, $13 million higher than expectations, according to Seeking Alpha. Moreover, for the 9 months, revenue was up +3.7% YoY. On a trailing 12-month (TTM) basis, it rose to $5.066 billion, up 4.5% YoY and higher than last quarter's TTM revenue.
In addition, net income was up 9.2% in Q3, and earnings per share (EPS) rose 12.7% due to share buybacks. For the 9 months, EPS was up 4.7%.
However, free cash flow (FCF), although positive, dipped 10.85% in Q3 to $146.18 million from $163.96 million a year ago, according to Stock Analysis. However, over the TTM period, FCF rose slightly (+0.66%) from $631.5 million last Q3 to $635.7 million this year, according to Stock Analysis.
Nevertheless, since revenue rose 4.5%, the TTM margin fell slightly from 13.03% to 12.55%. That affects my FCF forecast and the price target valuation.
Valuing DPZ Stock Using FCF Margins and FCF Yield
For example, analysts now project 2027 revenue will be $5.27 billion. So, assuming the company keeps making a 12.55% FCF margin, FCF could rise to $661.39 million.
And, assuming the market values DPZ at least at a 5% FCF yield:
$661.39m / 0.05 = $13.23 billion market value
That is 32.7% higher than today's market cap of $9.97 billion, according to Yahoo! Finance's market cap calculation.
In other words, DPZ stock could be worth almost ⅓ more:
$303.09 DPZ price x 1.327 = $402.20 price target (PT)
Other analysts see higher PTs as well. Yahoo! Finance's survey is at $356.69, and Barchart's survey is $359.48. Those PTs are 18% higher on average over today's price.
So, what is the best play here?
I discussed this in my previous Oct. 11 Barchart article - shorting out-of-the-money puts and also doing a put credit spread.
Shorting OTM DPZ Puts and Put Credit Spreads
For example, on Oct. 11 I pointed out that the Nov. 20 expiry $290 strike price put option offered a $7.60 premium to short-sellers. That worked out to a 2.62% one-month expected yield (i.e., $7.60/$290.00).
Today, that premium has drifted down to $5.95 (i.e., benefiting short-sellers), but that is still an attractively high expected yield: 2.052% (i.e., $5.95/$290.00).
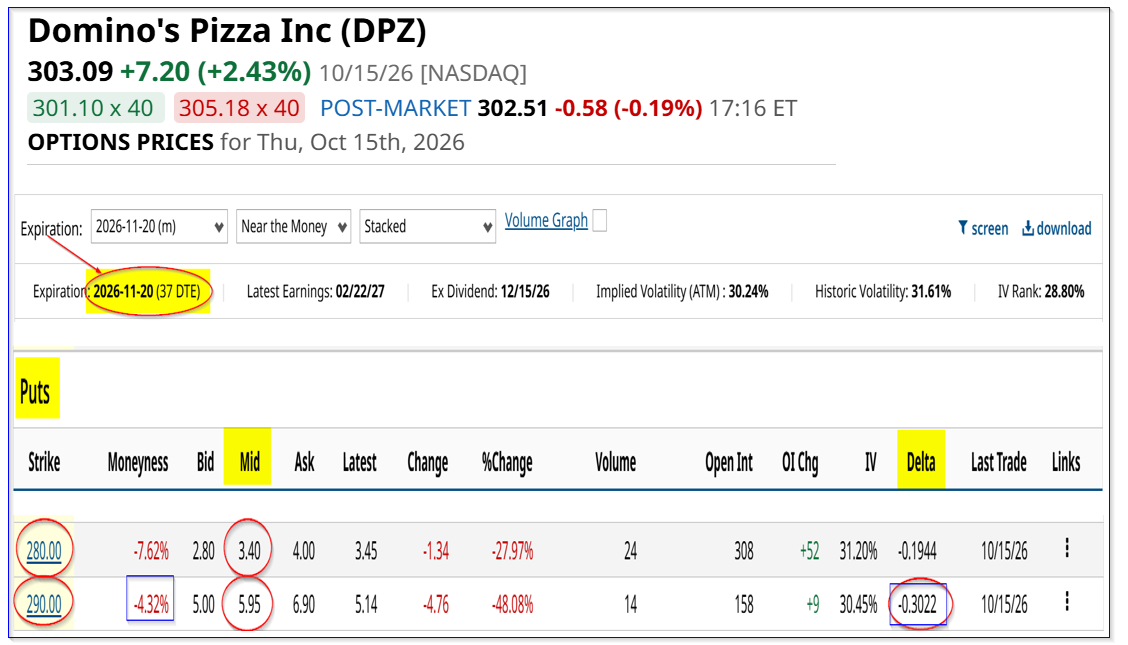
DPZ puts expiring Nov. 20 - Barchart - As of Oct. 15, 2026
I also discussed doing a $280 (long) - $290 (short) put credit spread play. That produces a net credit spread of:
$595 (short income) - $340 (long buy) = $255
That is slightly higher than the $240 original spread, but the expected return (ER) is higher as well:
$244 / ($1000 collateral - $255) at risk amount = $255 / $745 = 34.2% ER
This play has a lower collateral requirement ($1,000) compared to the $29,000 short-put play. But investors could lose a total of $745 if DPZ drops to $280.
Nevertheless, doing 2 put credit spreads provides a similar income amount ($510) compared to the $595 short put play. But the $2,000 collateral is less than 10% of the $29K required for the short-put play.
The bottom line is that investors willing to take on more risk can consider doing a DPZ put credit spread.
Comments
Log in or sign up to join the conversation.