
The odds of an October Fed rate hike have roughly halved since Monday, and the Dollar Index has risen on every one of those days. It trades near 102.10, its highest since April 2025. The index is moving with Crude Oil and the Euro rather than with the odds for the Fed's next meeting.
Close to four hikes still priced, and only October in doubt
The Fed raised its rate to 3.75-4.00% on September 16, and Fed Chair Warsh said inflation had been too high for too long. New York Fed President Williams said on Tuesday there was no need for urgency in raising it again, though he expects another increase this year.
Job openings and consumer confidence both came in soft the same day, and core Personal Consumption Expenditures (PCE) prices rose 0.2% in August, less than forecast. Minneapolis Fed President Kashkari said on Thursday he has no strong view on October and still expects more hikes. His own projection has one more quarter-point this year and another in 2027.
Futures put the chance of an October hike at about 70% on Monday and under 40% after the PCE release. They still price another hike this year and close to four by the end of 2027, so the market has moved the next hike rather than cancelled it. President Williams asked for no urgency, and traders applied that to October and to nothing after it.
The 10-year Treasury yield set a 24-year high above 5.30% on Wednesday, with the 30-year at 5.65%. Every step higher pays foreign buyers more to hold Dollar assets. Factories reported paying more in September too. The Institute for Supply Management (ISM) prices index jumped to 77.9, close to the 78.3 it recorded in March at the start of the war, and readings like that keep the later hikes in the price.
Europe buys more of its Crude Oil and fuel from the US than from anyone else
The Euro fell below 1.1300 against the Dollar on Thursday for the first time since May 2025, its fourth straight loss, and it makes up 57.6% of the Dollar Index. Worries over French government debt have added to the selling. It's possible that hotter September inflation in Germany, France, Italy and Spain will push the European Central Bank (ECB) to act, though the Euro fell on the day all four were published.
The European Union imports 96.6% of the Crude Oil and fuel it uses, and the US supplied 16% of those imports in 2024, more than any other country. Japan, 13.6% of the index, has almost no Crude Oil of its own, so the economies behind 71.2% of the basket face the same bill.
The US now exports more Crude Oil and fuel than it imports, a record 5.8 million barrels a day net in April. Each rise in Crude Oil is a cost for Europe and Japan and income for US exporters, which moves the Dollar Index whatever the Fed decides.
Crude Oil rose on Thursday on China's fuel export halt and on the Pentagon report of a third carrier group, and the Dollar Index set its session high on the second. Both stories add to the import bill in Europe and Japan, and neither depends on what the Fed does at its next meeting.
Pay has trailed prices for five months, and Friday is expected to add another
Nonfarm Payrolls (NFP) for September are due on Friday at 12:30 GMT, forecast at 94K after 162K in August, with the unemployment rate forecast at 4.1% for a third month. Average hourly earnings are forecast to rise 0.3% on the month. Payroll firm Automatic Data Processing (ADP) counted 90K private jobs on Wednesday against a 70K forecast, and announced layoffs fell to about 43K in September, down 18% from August.
The euro area's first estimate of September inflation comes out earlier the same day. A strong payroll number puts October back in play before the Fed decides on October 28, and a weak one pushes the next hike to a later meeting. For an index pricing the destination rather than the date, that is a choice between a hike and a hike.
Levels and bias
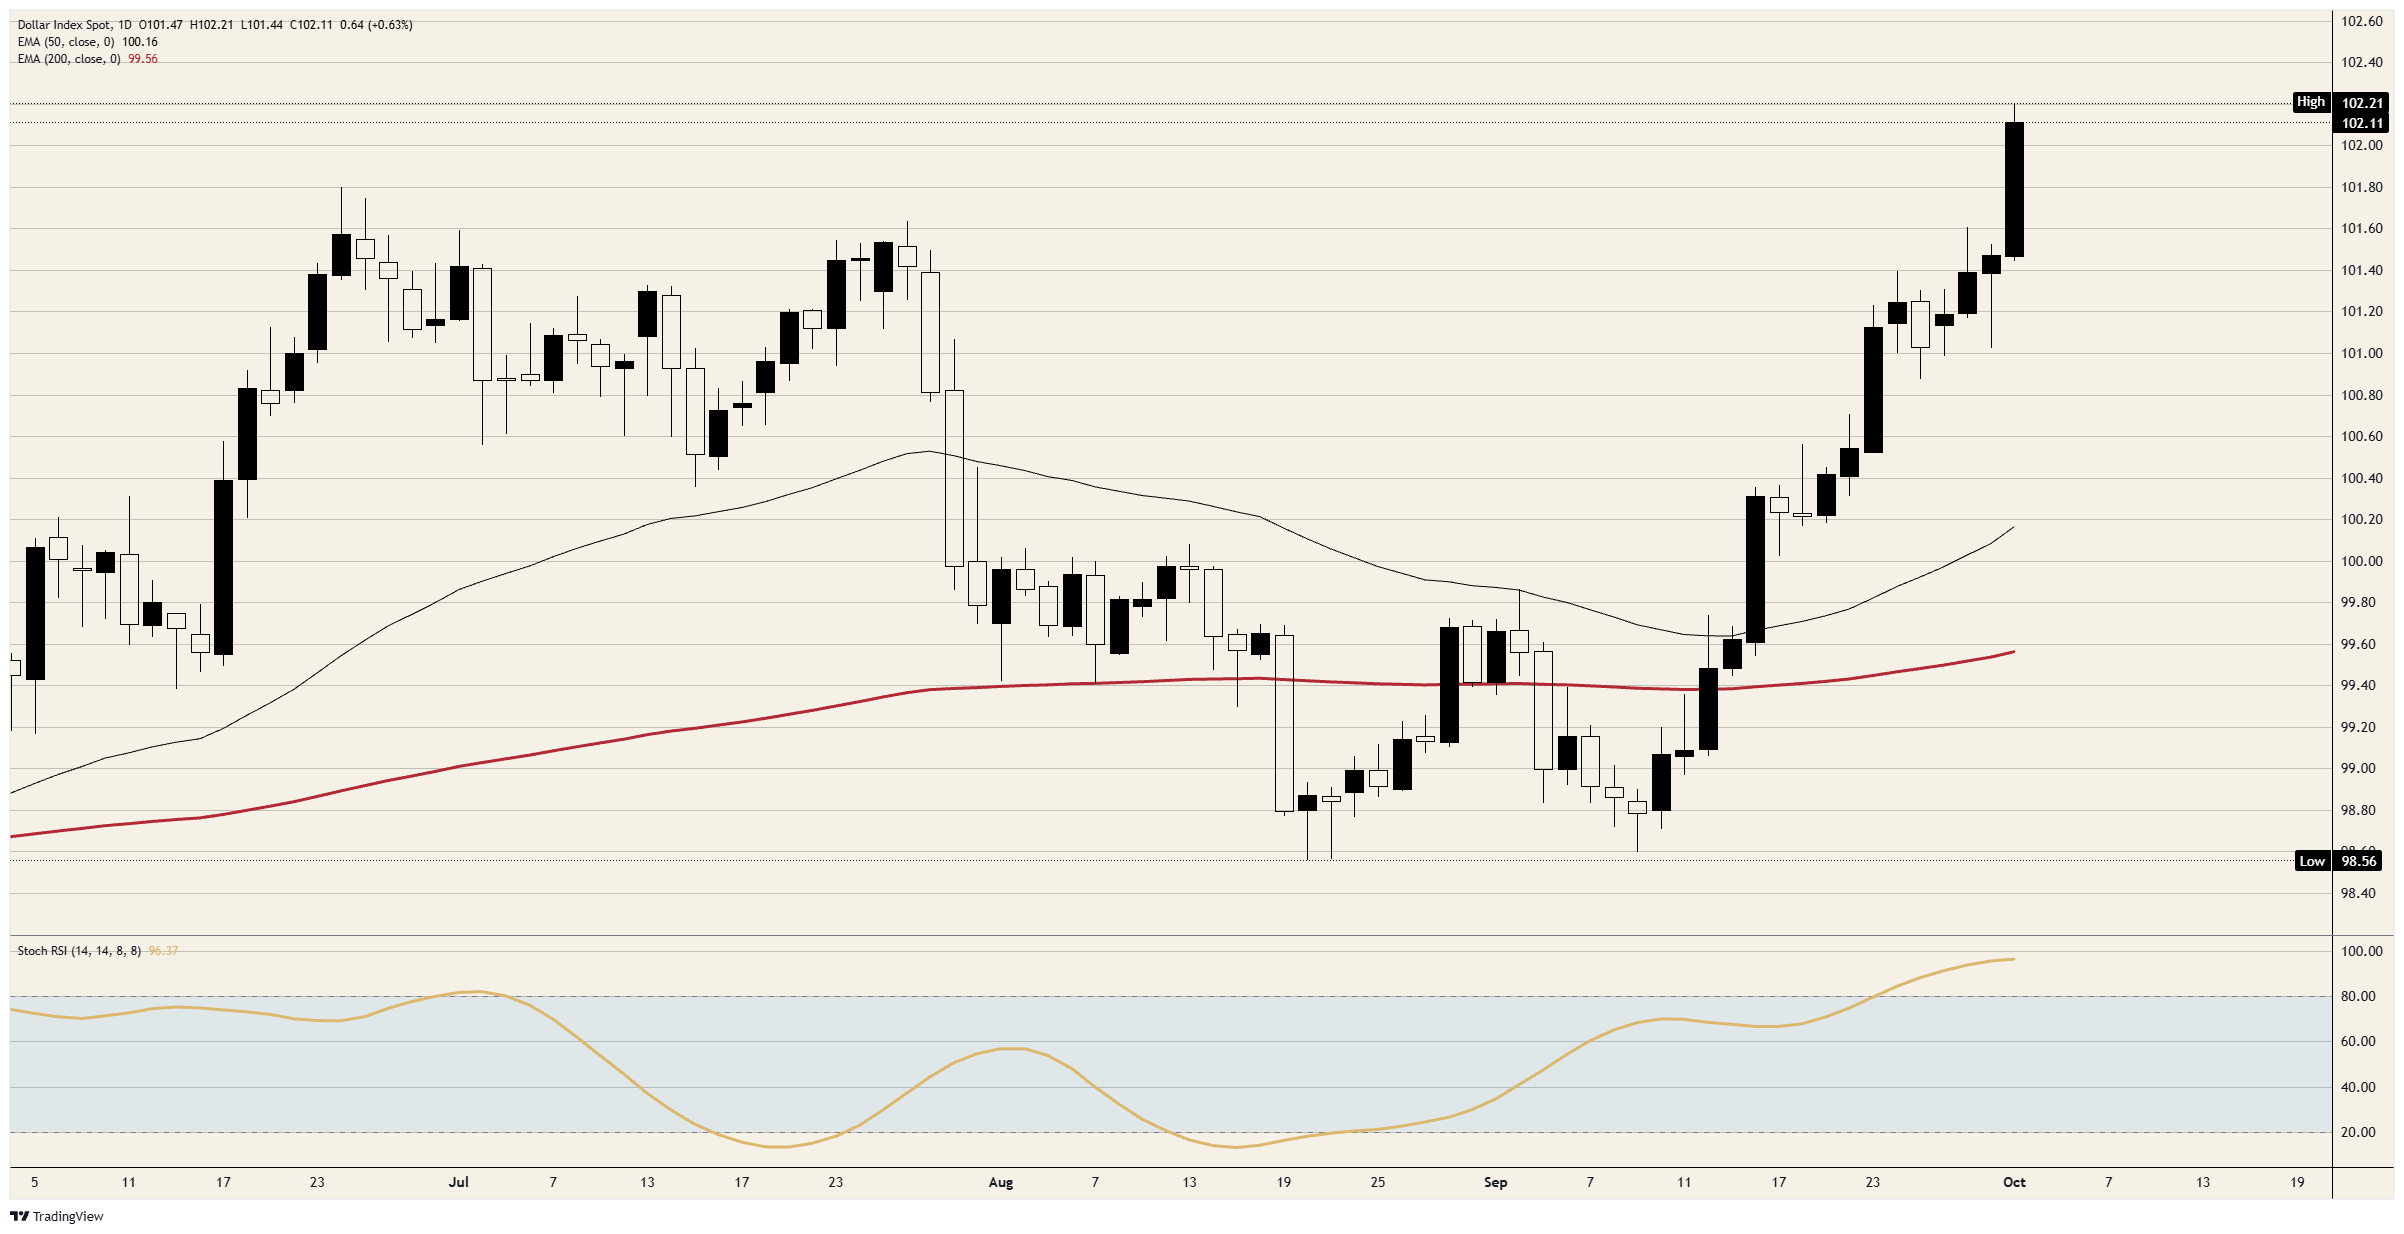
Resistance: Thursday's high just above 102.20 is where the push on the carrier report stopped. Above it, 102.50 and 103.00 are round levels the index hasn't traded since April 2025.
Support: 102.00 has held since Thursday's break above it. Below it, the June peak near 101.80 capped the index from June 24 until Thursday, then Wednesday's high near 101.50, where Thursday's run started.
Bias: The lean is long above 101.80, with 102.50 the first objective and 103.00 after it. Momentum on the daily Stochastic Relative Strength Index (Stoch RSI) is near 96 as the index heads for a fourth straight gain, so a dip toward 102.00 could come without breaking the run. A daily close back under 101.50 takes the index back into its late-September range and ends the trade.
DXY daily chart
Comments
Log in or sign up to join the conversation.