
Global risk assets found firmer footing on Wednesday as robust technology earnings revived confidence in the AI trade, triggering a sharp recovery from last week's chip sector drawdown. Asia led the rebound, with South Korea’s Kospi advancing 2.6% and Taiwan’s Taiex gaining 0.9%, boosted by outsized after-hours gains in US tech leaders. MSCI’s Asia Pacific Index snapped a two-day losing streak to rise 0.9%, while Nasdaq 100 futures added 0.7%. However, market appetite is becoming increasingly discerning: investors are actively penalising execution risks and CAPEX burdens while demanding concrete evidence of revenue delivery, cash flow generation, and return on capital.
Energy markets simultaneously pushed back to the centre of the global macro matrix. Brent crude surged past $110/bbl following fresh attacks on commercial shipping vessels near the Strait of Hormuz, alongside drawdowns in US crude inventories. Persistent $110+ oil presents a direct threat to global disinflation, especially as European natural gas futures climbed toward four-year highs. The ongoing energy spike is filtering into producer input costs, logistics, and longer-term inflation expectations, severely narrowing the scope for central bank monetary easing.
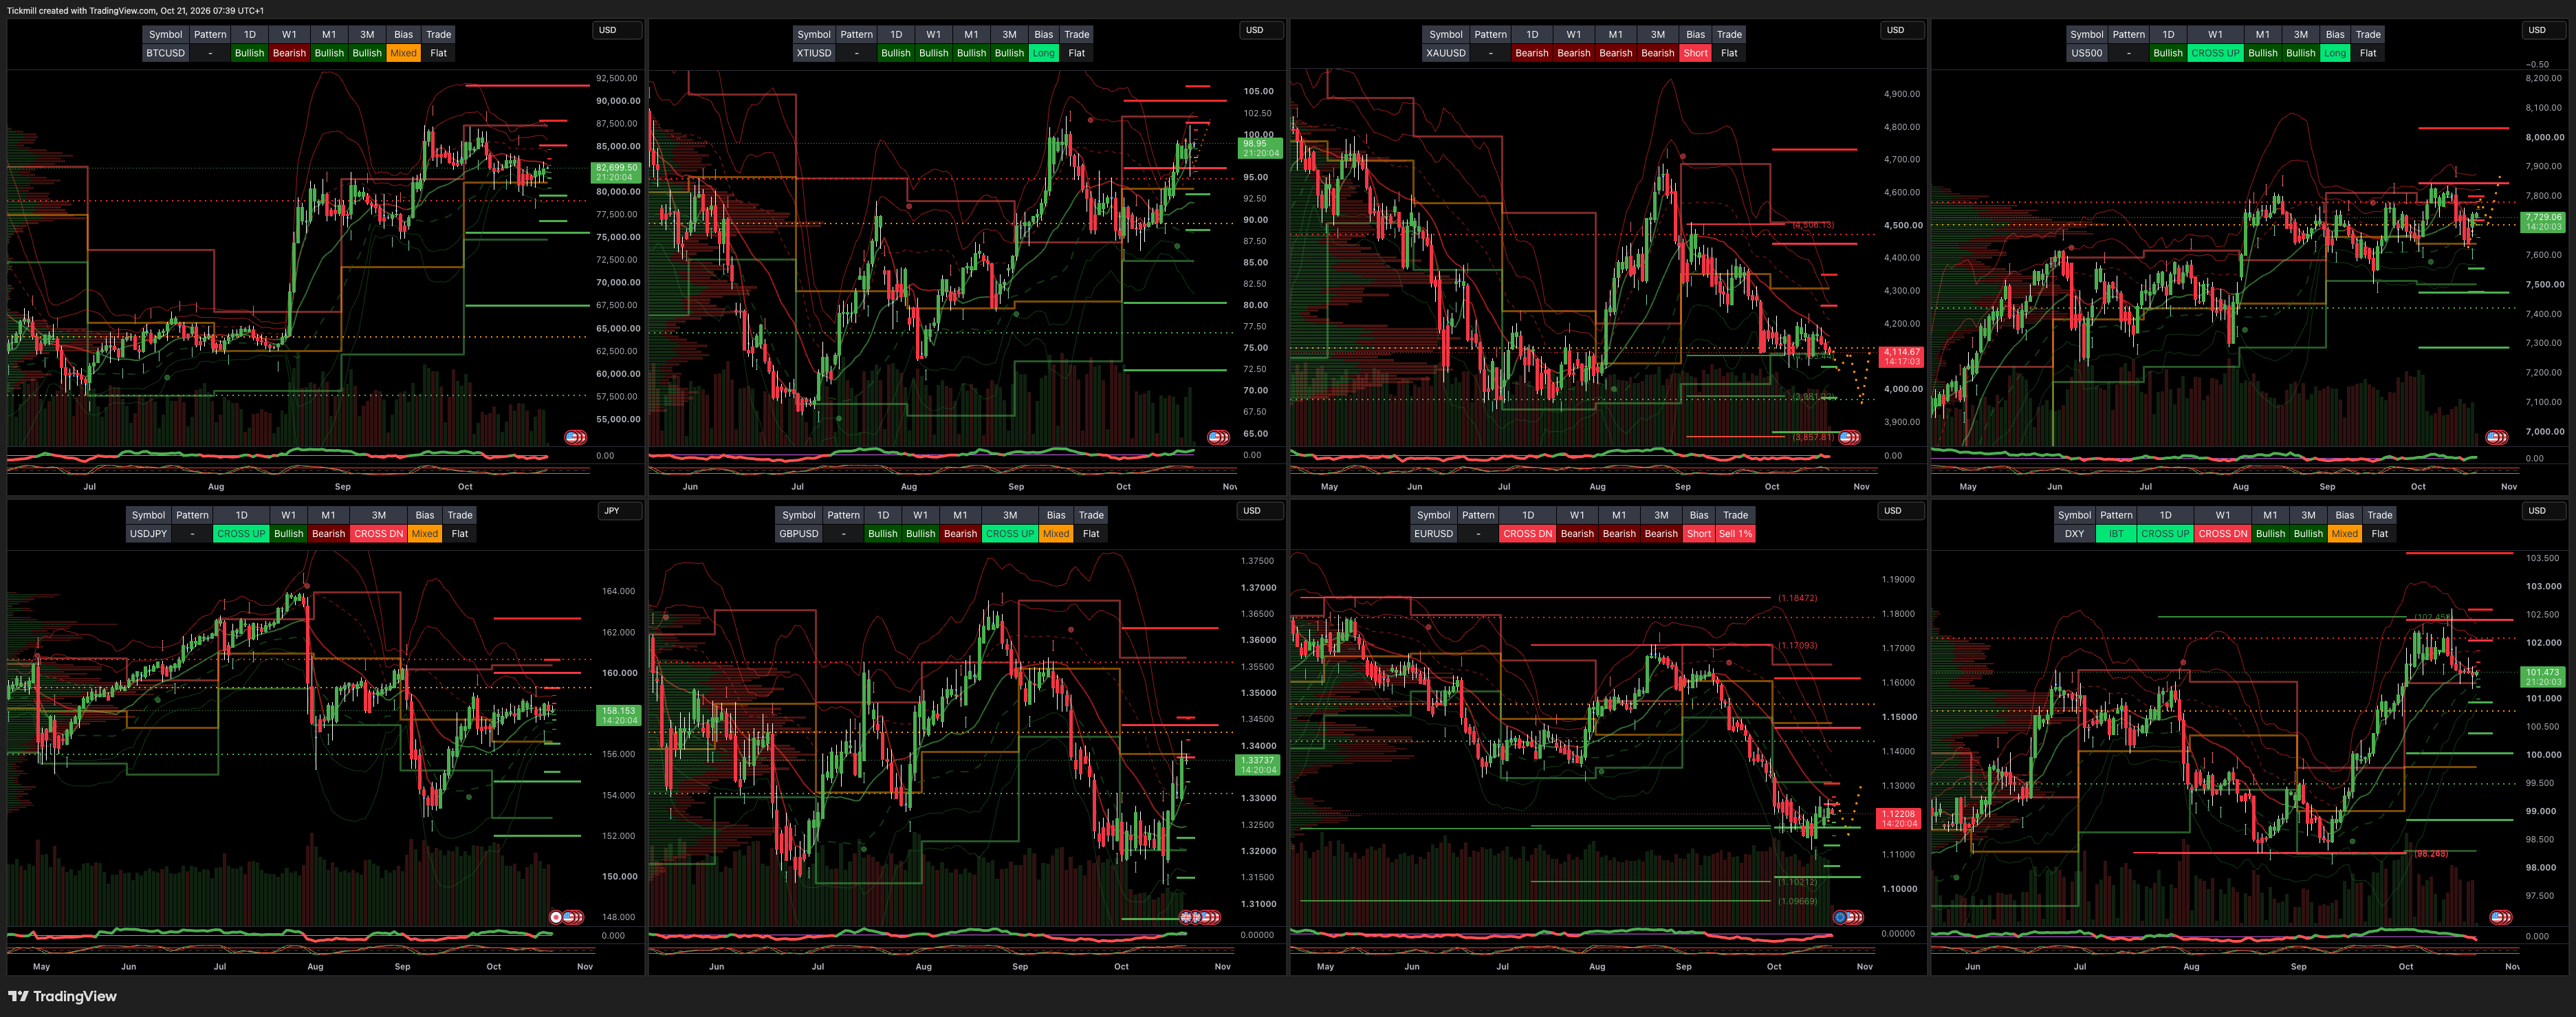
In foreign exchange and fixed income, the US Dollar Index traded with a softer tone as markets balanced improved risk sentiment against the tightening of financial conditions caused by recent equity volatility. Benchmark US Treasury yields edged lower as duration desks weighed growth headwinds against energy-driven price risks. Elsewhere, spot Gold traded defensively near $4,115/oz, capping upside momentum under the weight of resilient real yields and unwinding safe-haven flows.
In the UK, September inflation metrics reinforced a hawkish setup for the Bank of England ahead of its November decision. Headline CPI accelerated to 3.5% y/y (vs. 3.4% consensus), driven by a sharp 29.8% y/y spike in motor fuels that pushed transport inflation to 6.6%. Crucially for the Monetary Policy Committee, core CPI ticked up to 2.8% y/y while services inflation accelerated to 3.7% y/y. Paired with resilient employment growth, falling unemployment (4.7%), and sticky wage growth, the pickup in underlying services pressure cements expectations for an extended period of restrictive BoE policy.
UK public finances presented a parallel challenge for the Treasury. September Public Sector Net Borrowing (ex-banks) printed at £24.5bn—£1.9bn above OBR forecasts—driven by record September debt interest payments of £10.9bn tied to index-linked gilts. Cumulative FY26 borrowing now stands at £97.8bn (£6.0bn above OBR projections), eroding fiscal headroom ahead of the upcoming Budget and raising the prospect of expanded gilt issuance estimates. Meanwhile, official approval of the North Sea Jackdaw gasfield provided a localized energy security headline, though offering no immediate buffer against global wholesale energy price pressure.
Macro to Micro: Financial markets are attempting to rebuild risk appetite on tech earnings delivery, but crude holding above $110/bbl restricts global monetary flexibility. With UK CPI accelerating to 3.5% and US Treasuries balancing growth and inflation friction, central banks remain firmly locked in a restrictive posture. For traders, the key markers remain AI guidance execution, Brent crude dynamics, UK front-end rate repricing, and gilt issuance expectations leading into the UK fiscal statement.
Overnight Headlines
Witkoff To Present Putin Peace Proposal After Zelenskyy Talks
Iran FM: Strait Of Hormuz Remain Closed Until Agreement Is Reached
Israeli PM Netanyahu Pushes To Resume Israeli Strikes Against Iran
ECB's Lane: Greater Global Euro Use May Help ECB Control Inflation
BoE’s Greene Calls For Nov Hike As UK Wage Pressures Persist
UK Employer Pay Awards Edge Higher To 3.1%, Brightmine Says
BoJ Seen Raising Rates To 1.50% In Dec, Maintaining Quarterly Pace
Japan’s Sep Export Growth Slows To 16.7%, Missing Estimates
RBA Deputy Gov: Inflation Outlook Has Worsened Despite Tighter Policy
Goldman Now Sees RBA Raising Rates By 25bps To 4.85% In Nov
Tech Credit Risk Hits Fresh Highs On Fears Of Coming Debt Wave
Citadel’s Griffin Says AI Is ‘Almost Certainly’ In A Bubble
Super Micro Jumps After Preliminary Results Top Estimates
Netflix Revenue Growth Slows As It Overhauls Programming Units
Capital One Profit Beats As Lender’s Revenue Rises More Than 6%
Tesla And SpaceX Form Committees To Explore Potential Merger
SpaceX Profit Beats Estimates On Big Jump In AI Business Revenue
Boeing Wins Approval For Largest 737 MAX Variant
United Airlines Forecasts Q4 Profit Below Estimates As Fuel Costs Bite
CATL’s Slower Profit Growth Fans Fears For China Battery Rivals
FX Options Expiries For 10am New York Cut
(1BLN+ represents larger expiries and is more magnetic when trading within the daily ATR.)
EUR/USD: 1.1265 (EU3.13b), 1.1480 (EU1.62b), 1.1375 (EU984.6m)
USD/JPY: 159.00 ($969.2m), 158.00 ($535m), 157.00 ($410.8m)
AUD/USD: 0.6940 (AUD373.9m), 0.6900 (AUD341.3m), 0.6970 (AUD313.5m)
USD/CAD: 1.4200 ($497.3m)
EUR/GBP: 0.8800 (EU318.4m), 0.8600 (EU302.3m)
USD/CNY: 6.6600 ($355m)
USD/MXN: 17.95 ($490m), 17.82 ($328.1m)
USD/BRL: 5.8485 ($780.4m), 5.1200 ($663m)
CFTC Positions as of 16/10/26
Equity fund speculators trim S&P 500 CME net short position by 5,804 contracts to 390,896
Equity fund managers raise S&P 500 CME net long position by 8,186 contracts to 912,542
Speculators trim CBOT US 5-year Treasury futures net short position by 83,327 contracts to 1,080,204
Speculators increase CBOT US 10-year Treasury futures net short position by 91,621 contracts to 988,102
Speculators increase CBOT US 2-year Treasury futures net short position by 58,675 contracts to 911,579
Speculators increase CBOT US UltraBond Treasury futures net short position by 45,258 contracts to 321,597
Speculators increase CBOT US Treasury bonds futures net short position by 6,626 contracts to 126,438
Bitcoin net long position is 2,534 contracts
Swiss franc posts net short position of -22,078 contracts
British pound net short position is -106,964 contracts
Euro net short position is -137,573 contracts
Japanese yen net long position is 50,207 contracts
Technical & Trade Views
Comments
Log in or sign up to join the conversation.