
Asian equities slipped on Wednesday as Wall Street’s record-setting rally failed to generate sustained regional momentum. MSCI’s Asia-Pacific index fell 0.7%, led by technology drawdowns in South Korea and Hong Kong, while US equity futures trimmed early gains. Equity sentiment remains constructive at the index level, but narrow market breadth and multi-decade sovereign yields leave little room for positioning errors.
The primary macro drag came via energy and rate markets. Brent crude jumped 1.0% to near $101.60/bbl following renewed Iranian drone and missile attacks on commercial tankers in the Strait of Hormuz. The energy spike pushed US 10-year Treasury yields up 3 bps to 5.31%, reopening the debate around term-premium expansion and persistent supply-side inflation. Global duration remained under pressure, with French OAT futures continuing to lag German Bunds as investors digest Paris's unresolved fiscal path.
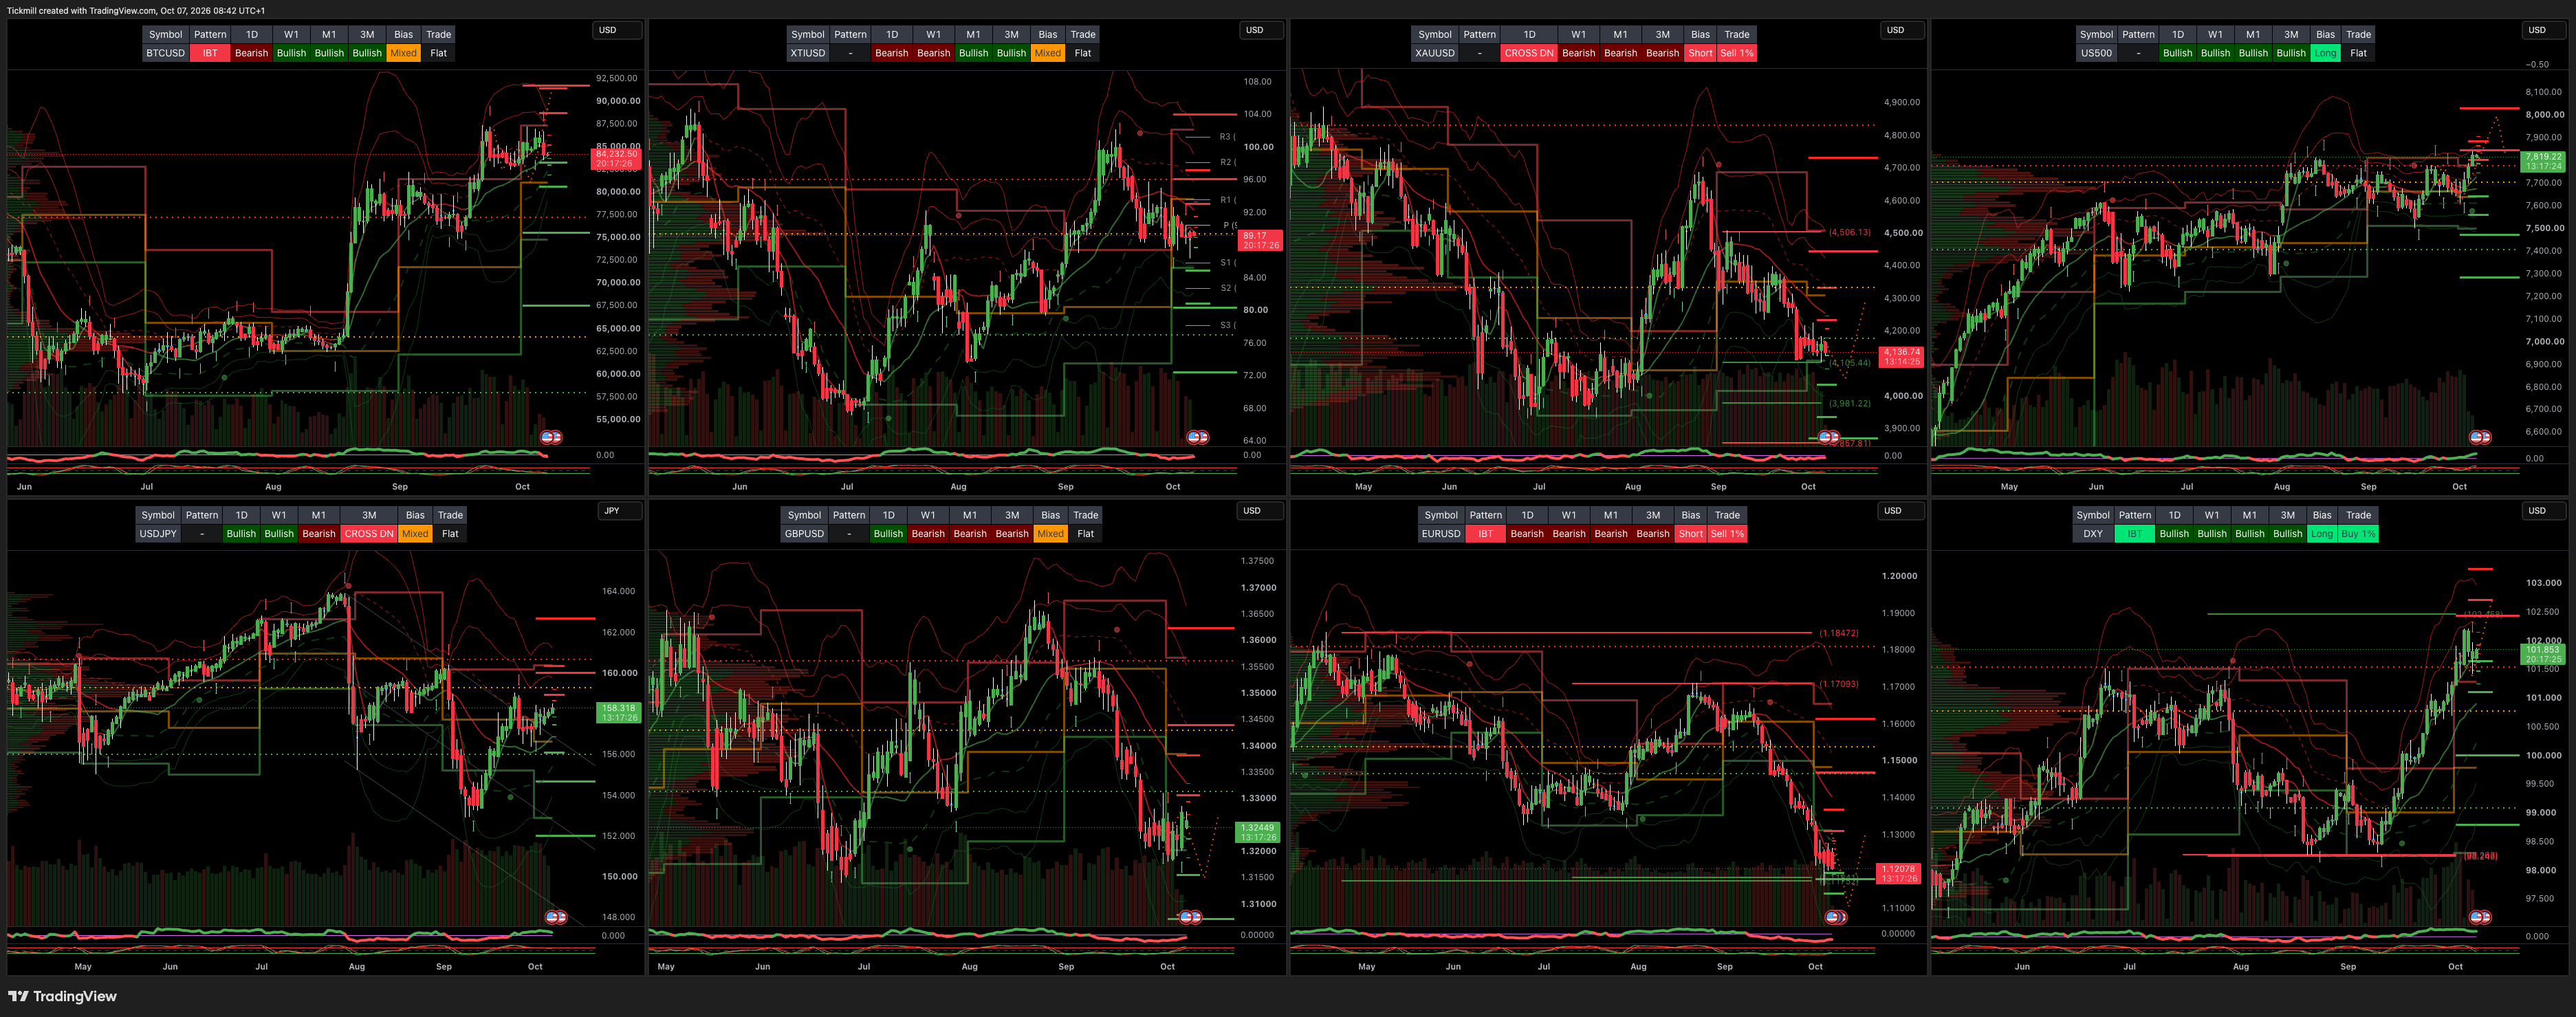
The US Dollar Index pressed to fresh 17-month highs, underpinned by widening rate differentials and attractive carry. Open-interest data shows leveraged funds adding short Euro and Sterling positions, while broad Dollar positioning remains far from crowded levels. In alternative assets, Bitcoin fell 1.7% to $84,100, illustrating how high real yields continue to cap high-beta speculative appetite.
In regional markets, the performance gap between Taiwan and South Korea widened to 23 percentage points over the past quarter, reflecting starkly divergent exposure to the AI hardware supply chain. Attention turns to Samsung Electronics’ preliminary earnings on Thursday; a strong quarterly print is vital to prove that AI-driven memory demand is broadening beyond niche chipmakers. Meanwhile, the Reserve Bank of India delivered its first interest rate hike in nearly four years, shifting to a calibrated tightening stance as elevated crude threatens external balances.
In Europe, French sovereign paper caught a modest technical bid, but long-term credibility remains fragile. Marine Le Pen’s proposal for a "golden rule" debt brake and €140bn in savings by 2032 directionally targets fiscal discipline, yet implementation faces steep constitutional hurdles. For fixed income desks, hedged OATs offer an attractive 77 bps pick-up over 10-year gilts, though political volatility keeps the entry point tricky.
Looking to the US session, the release of the September FOMC meeting minutes stands as the main macro catalyst. Traders will dissect the minutes for details surrounding last month's rate hike and gauge whether Fed officials viewed rising bond yields as a substitute for further monetary tightening ahead of the upcoming November decision.
Macro to Micro: Global risk assets are grinding higher on megacap tech strength, but the macro runway is narrowing. With Brent back above $101/bbl and 10-year Treasuries holding at 5.31%, central banks remain locked in a hawkish posture. For traders, the key focus centers on today's FOMC minutes, DXY resistance at 17-month highs, and Samsung's earnings preview as a barometer for broad tech health.
Overnight Headlines
US VP Vance Says Iran Must Cut Nuclear Enrichment To End War
Iran Ramps Up Ship Attacks In Hormuz As Oil And Gas Flows Climb
Trump Resists Deeper US Role In Saudi Arabia-Houthi Conflict
Two Houthi Missiles Target Aden International Airport In Southern Yemen
Aramco Weighs Its Options For Saudi Arabia’s Growing Gas Surplus
Zelenskyy: Intelligence Shows Russia Is Preparing Massive Attack
Russian Hostile Activity Costs UK Up To £2.5B A Year, Report Warns
BoJ’s Dovish Dissenter Signals Support For Future Rate Hikes
Japan Real Wages Rise For Eighth Month, Aided By Takaichi Relief
Japan Manufacturers’ Tankan Index Hits Near Five-Year High
JPM: Deeply Distressed US Loans Rise To Highest Level Since Pandemic
Brussels Looks To Capture Big Tech Through Tax On Large Corporations
HSBC Plans Sweeping Job Cuts Across UK Wealth Business In AI Push
Dalio Says We’re Nearing Point Where AI Bubble May Burst
SpaceX To Raise $40B To Buy Nvidia Chips In Financing Led By Apollo
Anduril Plans Shipyard To Manufacture Parts For US Navy Submarines
Paramount Wraps Up Merger To Create Hollywood Powerhouse Skydance
FX Options Expiries For 10am New York Cut
(1BLN+ represents larger expiries and is more magnetic when trading within the daily ATR.)
EUR/USD: 1.1100 (EU800m), 1.1125 (EU570m), 1.1200 (EU850m), 1.1240 (EU542m), 1.1245 (EU545m), 1.1250 (EU1.0b), 1.1255 (EU1.5b), 1.1260 (EU771m), 1.1270 (EU1.1b), 1.1300 (EU3.6b)
USD/JPY: 158.00 ($731m)
AUD/USD: 0.6935 (AUD609m), 0.6940 (AUD730m), 0.7050 (AUD705m)
NZD/USD: 0.5550 (NZD615m)
CFTC Positions as of 1/10/26
Bitcoin net long position is 2,465 contracts
Swiss franc posts net short position of -24,617 contracts
British pound net short position is -91,075 contracts
Euro net short position is -63,256 contracts
Japanese yen net long position is 55,440 contracts
Speculators increase CBOT US 5-year Treasury futures net short position by 114,848 contracts to 995,701
Speculators increase CBOT US 10-year Treasury futures net short position by 88,863 contracts to 900,615
Speculators trim CBOT US 2-year Treasury futures net short position by 115,041 contracts to 792,024
Speculators trim CBOT US UltraBond Treasury futures net short position by 10,289 contracts to 326,436
Speculators increase CBOT US Treasury bonds futures net short position by 31,070 contracts to 186,875
Equity fund managers cut S&P 500 CME net long position by 33,658 contracts to 901,255
Equity fund speculators increase S&P 500 CME net short position by 575 contracts to 355,697
Technical & Trade Views
Comments
Log in or sign up to join the conversation.