
Global equities remained under pressure on Tuesday as a fresh wave of US export restrictions on advanced artificial intelligence chips heightened anxiety ahead of Nvidia’s pivotal quarterly earnings. The MSCI All Country World Index slipped 0.2% to mark its fourth consecutive decline, while Asian bourses fell 1.5%, led lower by semiconductor-heavy Taiwan and South Korea. Following Monday’s 1.9% drop in the S&P 500 (7,417) and a ~2.6% slide in the Nasdaq Composite, European equity futures pointed down ~0.7% into the open, though Nasdaq 100 contracts staged a tentative bounce from a three-day losing streak.
The immediate catalyst centers on Washington’s new interim rule requiring government licenses for datacenter operators across third-party jurisdictions—specifically targeting cloud loopholes in Southeast Asia—to supply advanced US AI compute to foreign clients. The tightening regulatory perimeter rattled Chinese AI developers and dragged the CSI 300 to its lowest level since July 2025, even as domestic Chinese chipmakers rallied on import-substitution bets. Across Asia-Pacific, South Korea’s Kospi lost nearly 2.0%, Japan’s Nikkei 225 shed ~1.2%, and TSMC weighed heavily on Taipei as dealing desks priced in higher compliance costs, licensing delays, and geopolitical friction into the global hardware supply chain.
Tonight’s Nvidia earnings—its first report following CEO Jensen Huang’s abrupt resignation—are now the focus. After sliding another 4% on Monday, Nvidia faces a high-stakes credibility test rather than a routine beat-and-raise. Interim CEO Colette Kress must prove that hyperscaler order books remain capacity-constrained rather than policy-constrained, while providing clear assurances on succession, gross margins, and China licensing exposure. Later this week, Anthropic’s landmark IPO will serve as the critical private-market counterpoint to gauge whether institutional appetite for frontier AI models survives higher hurdle rates.
Fixed income and currency markets continue to apply pressure on long-duration assets. While WTI ($85.40/bbl) and Brent (~$92.00/bbl) softened at the margin, sticky core services and intermediate producer inflation keep the Federal Reserve locked in a hawkish stance. The benchmark US 10-year Treasury yield held near 5.13%, while short-term rate expectations (1y1y USD OIS) converged with the 5y5y forward benchmark—signaling that money markets are pricing outright restrictive policy tightening (~three hikes by spring) rather than mere neutral normalization. Higher real yields continue to underpin the US Dollar, keeping USD/JPY pinned near intervention-sensitive thresholds ahead of today’s US retail sales print and Thursday’s high-stakes Trump-Xi-Putin summits.
Across the Atlantic, UK labor market data failed to settle the December versus February Bank of England rate-hike debate. Q3 unemployment dipped to 4.6% (below the 4.7% consensus) alongside a 155k three-month employment gain, yet timelier October HMRC payrolls contracted by 34k. With HMRC median pay ticking up to 4.6% y/y against a softer 3.1% BoE core private-sector measure, tomorrow’s October UK CPI—measured against the BoE’s 3.7% y/y staff forecast—and Governor Andrew Bailey’s speech will dictate whether December becomes an active tightening meeting. Meanwhile, ECB President Christine Lagarde speaks Friday, with markets leaning toward a 25 bps December rate hike followed by an extended pause.
Macro to Micro: Risk appetite is being squeezed by a three-front collision of tighter US semiconductor export controls, Nvidia’s post-Huang credibility test, and a rates curve pricing genuinely restrictive Fed policy. While softer crude oil provides marginal headline relief, rising real yields and politicized AI supply chains leave little room for valuation errors. For traders, immediate tactical focus centers on Nvidia’s datacenter guidance and succession messaging, US retail sales resilience, 1y1y vs. 5y5y OIS rate convergence, tomorrow’s UK CPI surprise risk, and Thursday’s geopolitical summits between Trump, Xi, and Putin.
Overnight Headlines
German ZEW Investor Outlook Set To Edge Higher After Oct Drop
US Intel Indicates Iran Planning To Bomb Washington DC
UKMTO Reports Tanker Attacked Near Oman In Strait Of Hormuz
US VP Vance: Iran War Will Not Become Long-Term Commitment
Finland Urges European Leaders To Engage Putin Directly
US Envoy Kushner Reports Progress In Ukraine Peace Negotiations
Japan Protests After Suspected Russian Aircraft Violate Its Airspace
Trump Advisers Divided Over China Policy Ahead Of Xi Summit
US Moves To Restrict China's Remote Access To Advanced AI Chips
Canada And China Expand Tariff Relief As Carney Meets Xi
Fed's Hammack Reiterates Case For Slow, Steady Rate Hikes
RBA Minutes: Majority Backed Hike As Inflation Risks Remain Elevated
NZ Two-Year Inflation Expectations Rise To 2.36% In Q4
Japan To Postpone Launch Of New Floating-Rate Govt Bonds
Dollar Erases 'Liberation Day' Losses As 'Sell America' Fears Fade
Anthropic IPO Draws $5B Investment From Altimeter's Brad Gerstner
California Sues OpenAI Over Alleged Loss Of Control Of AI Models
Chevron Nears $5B Acquisition Of Blackstone-Backed Beacon
Roche's Breast Cancer Pill Wilserdly Wins US Regulatory Approval
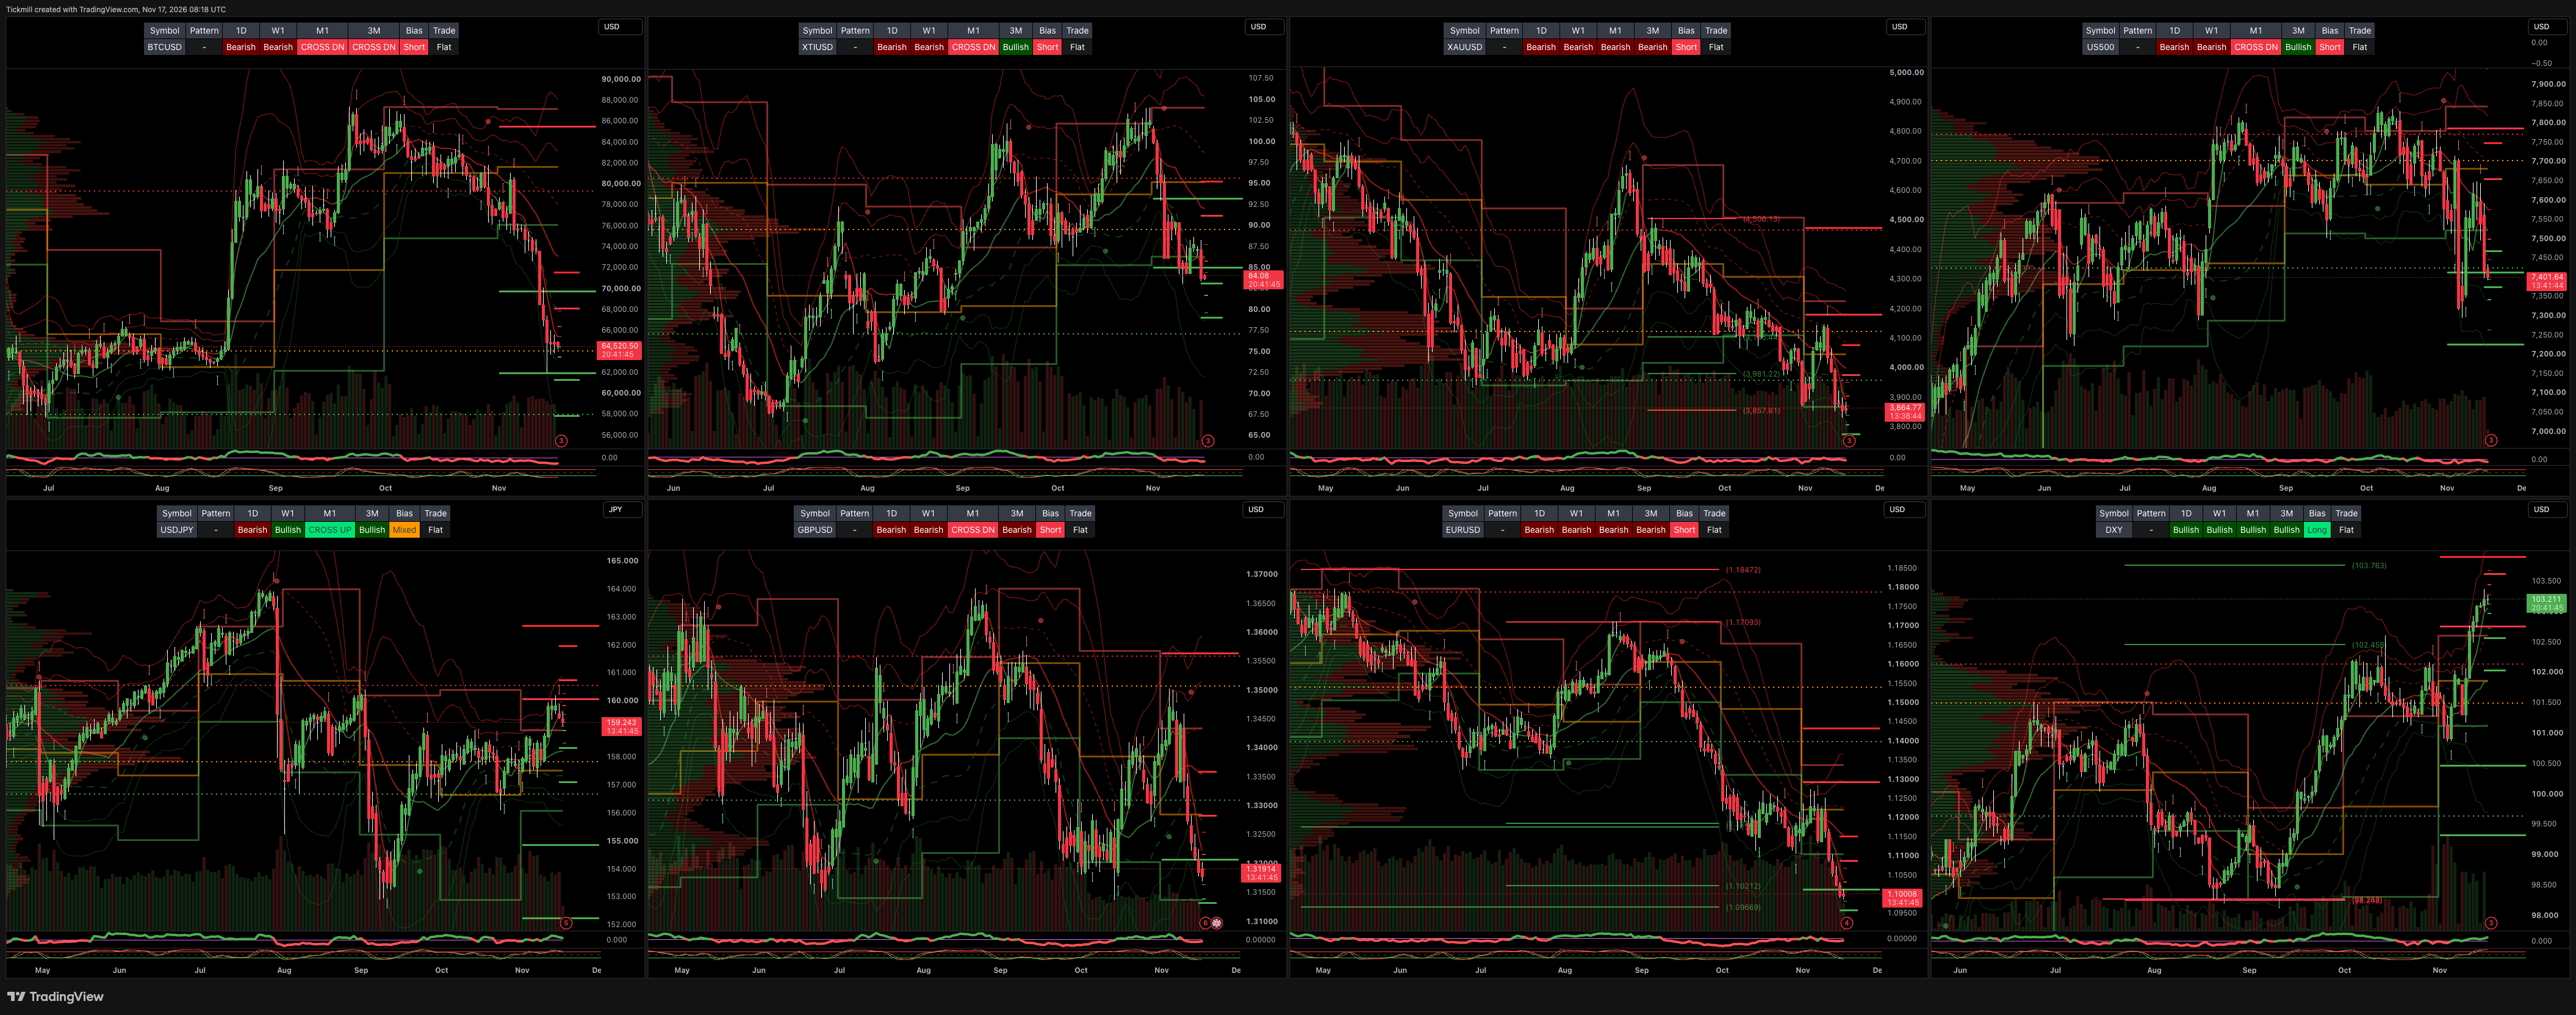
Technical & Trade Views
Comments
Log in or sign up to join the conversation.