
In 1964, Russ Williams in Odessa, Texas, needed a place to store his fishing equipment. In what was likely an “aha” moment, the self-storage industry was born.
Americans have a lot of stuff. There are 50,000 self-storage facilities across the country covering 2.2 billion square feet, with more than 50 million square feet of new storage being delivered every year.
If you’re around people as you’re reading this, look to your left and look to your right. Chances are one of the three of you uses self-storage.
CubeSmart (NYSE: CUBE) is the third-largest owner of self-storage space in the U.S., with 1,500 properties.
It is set up as a real estate investment trust (REIT), which means it must pay out at least 90% of its taxable income as dividends.
As a result of that requirement, REITs typically have strong dividend yields. CubeSmart is no exception, with a solid 5.4% yield.
Can investors rely on this dividend?
REITs use a measure of cash flow called funds from operations (FFO).
Last year, CubeSmart saw FFO dip from $601 million to $590 million. This year, it is forecast to increase slightly to $595 million.
That $595 million estimate, while higher than the 2025 total, is below the $615 million achieved in 2023.
The Safety Net model considers one- and three-year results and the estimate for the current fiscal year. The fact that 2025’s number was below the previous year’s and 2026’s estimate is below 2023’s figure causes the stock’s Safety Net rating to be penalized.
Last year, CubeSmart paid shareholders $478 million in dividends, or 81% of FFO. This year, the payout ratio is forecast to inch up to 83%.
Because REITs are required to pay out so much of their profits, I’m comfortable with payout ratios of up to 100%.
CubeSmart has also raised its dividend for 16 straight years, which gives the stock a one-point upgrade.
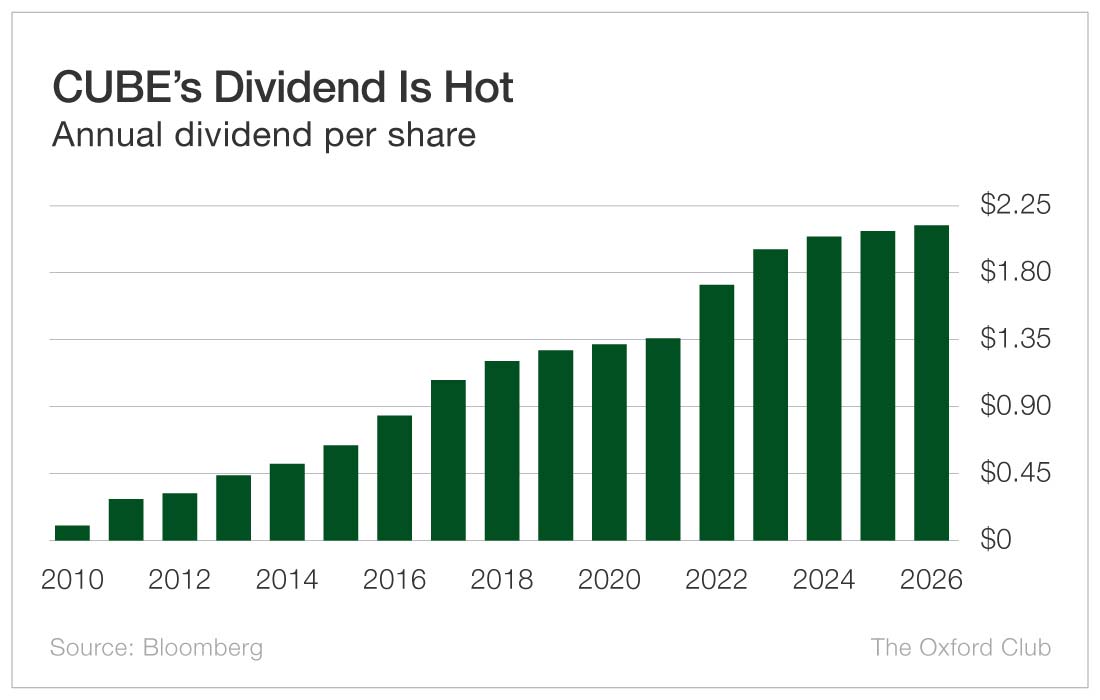
There is a slight concern that CubeSmart is having a tough time growing FFO. If that doesn’t improve and the dividend continues to increase to the point that it eats up more than 100% of cash flow, it will become a problem.
But the company likely has a long runway before that happens.
Furthermore, CubeSmart’s management has shown that it takes its dividend seriously, having grown it every year for more than a decade and a half.
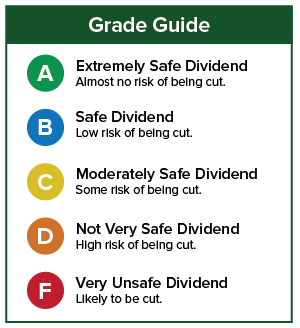
At this point, there is a low risk of the dividend being cut.
Dividend Safety Rating: B
Comments
Log in or sign up to join the conversation.